


Palantir Just Reported Another Blowout Quarter, and the Stock Sank. Here’s Why.
Key Points
Palantir’s total contract value growth slowed to 6% from 49% a quarter earlier, but several shorter-duration sovereign AI contracts help explain the dip.
U.S. commercial revenue jumped 148% to $984 million and surpassed U.S. government revenue for the first time.
At 96 times forward earnings, Palantir leaves little room for error if contract growth stays sluggish.
- 10 stocks we like better than Palantir Technologies ›
Palantir Technologies (NASDAQ:PLTR) isn't for everyone; I'll grant you that. While I've been bullish on Palantir for a long time, many of my peers continue to blanch over its valuation. And some investors balk at the stock because of its controversial role in the federal government, where it's supporting U.S. Immigration and Customs Enforcement (ICE).
But this much is indisputable: Palantir is growing revenue and profits at an impressive pace, helping to drive the company's stock price up more than 700% in the last three years.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Palantir reported third-quarter revenue of $2.31 billion, up 96% from a year ago, and raised its full-year revenue forecast to approximately $8.53 billion -- representing annual growth of 91%. But the stock dropped following its Nov. 2 earnings announcement and has been down more than 8% since then.
The concern centers on Palantir's total contract value (TCV), which measures the value of contracts signed during a reporting period. While second-quarter TCV was up 49% year over year, Palantir saw that growth rate shrink to just 6% in the third quarter.
Given that Palantir stock is already priced to reflect expectations of extraordinary growth, investors are increasingly cautious about Palantir's long-term growth story.
Here's why I think the naysayers are wrong.

Image source: Getty Images.
Palantir's commercial business is taking off
I thought Palantir had a great quarter. Its U.S. commercial revenue jumped 148% year over year to $984 million, surpassing the company's U.S. government revenue for the first time.
Palantir also reported $1.22 billion in adjusted free cash flow, representing a 53% margin. And its net dollar retention rate reached 165%, meaning existing customers are spending substantially more with Palantir than they were a year earlier. The company closed 212 deals worth at least $1 million during the quarter, including 64 valued at $10 million or more. Its remaining U.S. commercial deal value reached $6.52 billion, up 79% from a year earlier.
That last figure is particularly interesting. The remaining deal value represents contracted revenue that Palantir hasn't yet recognized. While new contract growth slowed, the company still has substantially more commercial business under contract than it did a year ago.
Why contract growth matters
I think it would be a mistake to call Palantir's $2.92 billion in third-quarter TCV a disappointment. It's actually higher than the company's $2.31 billion in quarterly revenue. But for some investors, the 6% year-over-year growth raises questions about whether the company can continue to expand its revenue base significantly.
But here's the context: Palantir signed several large contracts with shorter-than-usual durations as customers began adopting the company's sovereign AI offerings -- a major point of the company's sales pitch in the quarter. Shorter contracts can reduce reported TCV even when customer demand remains healthy.
"Despite being only at the very beginning of the sovereign AI revolution, we already see how it is transforming the size of the market," Palantir’s chief revenue officer Ryan Taylor said.
Still, investors shouldn't dismiss the slowdown. If contract growth remains sluggish over several quarters, it could eventually translate into weaker revenue growth.
And Palantir's premium valuation leaves little room for disappointing results. Palantir stock trades at a forward price-to-earnings ratio of 96 times, and a forward price-to-sales multiple of 46 times.
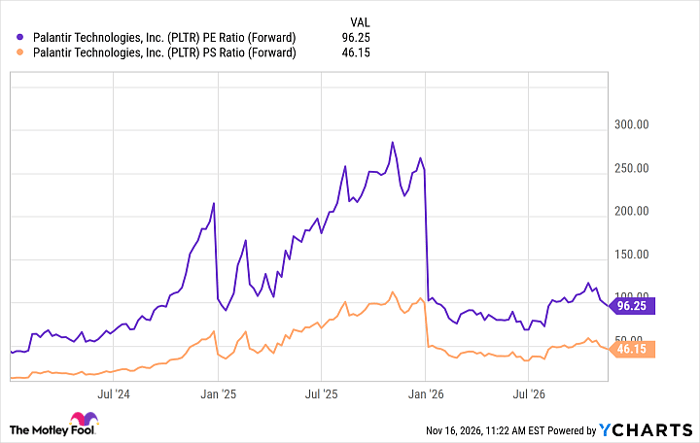
PLTR PE Ratio (Forward) data by YCharts
Why I'm still bullish on Palantir
While Palantir has been an important government contractor for decades, I think its most interesting opportunity is in the fast-growing commercial business. It's one of the best companies that I know that can help businesses figure out how to use artificial intelligence effectively.
While virtually every company has access to powerful AI models, many lack the ability or expertise to turn those models into tools that actually improve operations, reduce costs, or help employees make better decisions. Palantir's Artificial Intelligence Platform (AIP) connects AI models to the client's existing data and operating systems to build applications that address real operational problems.
Palantir's AIP bootcamps give prospective customers hands-on experience using the software to solve their own business challenges. Rather than spending months discussing hypothetical applications, companies can see what Palantir's technology can accomplish.
I believe these programs are an important reason Palantir's commercial business is growing so quickly. The company makes it easier for customers to understand the software's value and move toward broader adoption.
Palantir's third-quarter contract numbers deserve attention, especially given the stock's valuation. But with U.S. commercial revenue growing 148% and existing customers substantially increasing their spending, I don't see evidence that Palantir's growth story has run its course.
Should you buy stock in Palantir Technologies right now?
Before you buy stock in Palantir Technologies, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Palantir Technologies wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 17, 2026.
Patrick Sanders has positions in Palantir Technologies. The Motley Fool has positions in and recommends Palantir Technologies. The Motley Fool has a disclosure policy.
Recommended Articles


