


Cisco Raises Its AI Target to $9 Billion, but CSCO Still Faces $102.71 Resistance
TradingKey - Cisco Systems (NASDAQ: CSCO) rose 1.24% to $102.01 on Thursday, November 12, ahead of its fiscal first-quarter report after the close. Cisco beat estimates and raised its full-year outlook, yet the stock slipped about 1% after hours, and overnight trading sits at $100.95.
The stock is up about 32% this year, against 9% for the Nasdaq, but it fell sharply in early November before this week's rebound.
A Beat and a Raise
Revenue rose 24% to a record $18.5 billion, above the $18.1 billion LSEG consensus. Non-GAAP EPS, which excludes items such as stock-based pay, rose 40% to $1.40 against $1.33 expected. Product revenue grew 32% to $14.7 billion, and networking revenue jumped 43% to $11.1 billion.
Cisco raised its fiscal 2027 revenue guide to $74.8 billion to $75.8 billion, from $72.2 billion to $73.4 billion, and its non-GAAP EPS guide to $5.47 to $5.53, from $5.05 to $5.11. That implies about 19% revenue growth for the year. Cisco also lifted its hyperscaler AI infrastructure revenue target to $9 billion, more than double fiscal 2026. CEO Chuck Robbins said the company is "in the very early stages of a multi-year networking supercycle."
Why the Stock Did Not Jump
The beat did not lift the stock, because the details were weaker than the headline numbers. Non-GAAP gross margin, the share of revenue left after production costs, fell to 65.6% from 68.1%, and product margin dropped to 63.7% from 67.2%. CFO Mark Patterson said the drop was "primarily driven by higher hardware mix and elevated memory costs," and that Cisco is comfortable with a full-year margin just under 65%.
Total product orders grew 21%, down from 35% in the fourth quarter, though orders excluding hyperscalers rose 14%. And Cisco stopped disclosing hyperscaler AI orders, switching to revenue because orders are "going to be lumpy." That makes it harder to check Morgan Stanley's November 5 warning that customers ordered early ahead of price increases.
Cheap, With Less Visibility Ahead
Patterson also warned of "tougher compares and a little bit less visibility" in the second half. At $102.01, by my calculation, Cisco trades at about 18.5 times the midpoint of its new fiscal 2027 EPS guide, low for a company growing revenue 24%. The market wants proof that margins can hold before it pays more.
Cisco Technical Analysis: Daily Close Above $102.71 Could Open $112.23
That hesitation shows clearly on the daily chart. Buyers have lifted the stock steadily off last week's low near $93.36, and CSCO is now testing $102.71, the old support level that broke in early November. The falling trendline from the October high, a line drawn across its lower highs, sits just above it, so this area is a tough double barrier. The results came after Thursday's close, and the muted overnight reaction leaves the stock right at that barrier.
RSI, a momentum gauge that runs from 0 to 100, has climbed to about 45 and is now above its signal line. The MACD, another momentum indicator, is still negative, but its bars are shrinking, which shows selling pressure is fading.
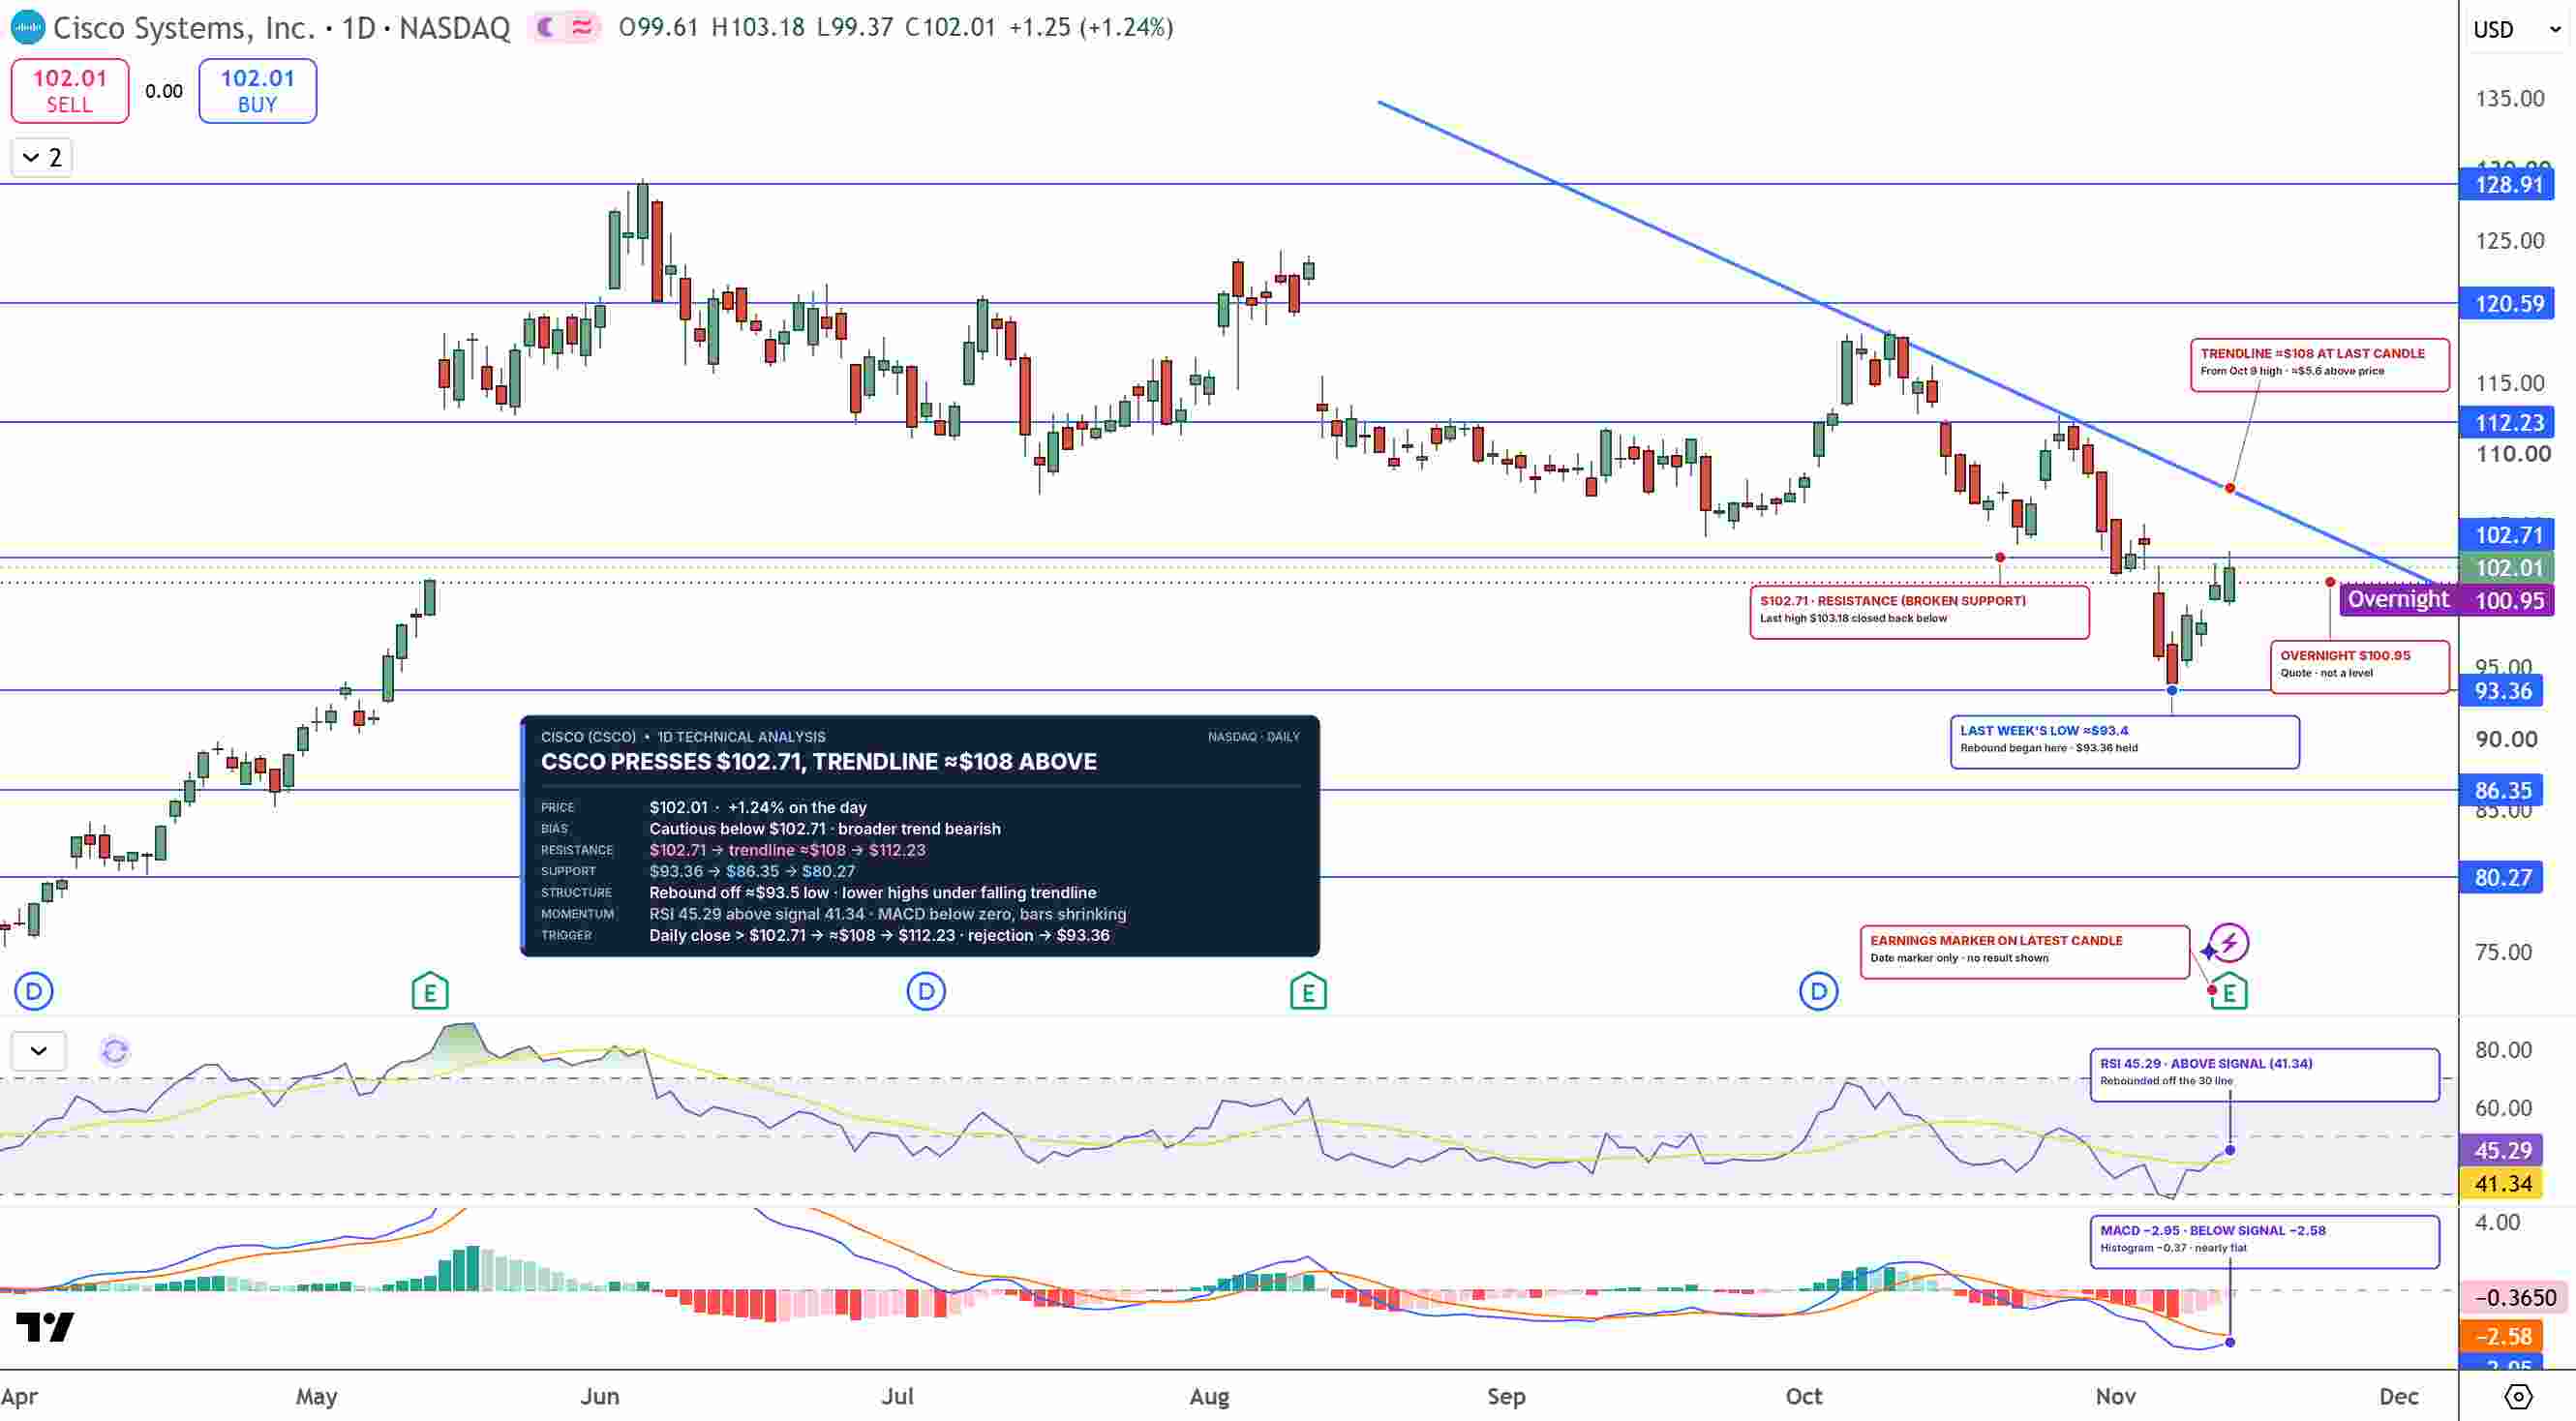
CSCO Price Chart - Source: Tradingview
A daily close above $102.71 and the trendline could open $112.23, followed by $120.59. A rejection here, however, could send CSCO back toward $93.36, with $86.35 below that.
I'm cautiously neutral while CSCO trades below $102.71, and a breakout above that level would turn the outlook bullish.
Key Levels
- Last close: $102.01, up 1.24% on Thursday, November 12 (overnight: $100.95)
- Support: $93.36, $86.35
- Resistance: $102.71, $112.23, $120.59
- RSI: 45.29
- Bullish trigger: Daily close above $102.71
- Bearish trigger: Daily close below $93.36
FAQs
Why didn't Cisco stock rise after earnings?
Cisco beat estimates and raised its fiscal 2027 guidance, but gross margin fell to 65.6% on memory costs, product order growth slowed to 21%, and Cisco stopped disclosing hyperscaler AI orders.
What is the Cisco stock forecast now?
The bias is cautiously neutral below $102.71 on the daily chart. A daily close above $102.71 and the trendline targets $112.23 and $120.59, while a rejection could send CSCO back toward $93.36.
Bottom Line
Cisco delivered a strong beat and raise, but memory costs and slower orders kept buyers cautious. The level that matters is $102.71. In my view, a daily close above it and the trendline would open $112.23, while a rejection would put $93.36 back in focus.
Recommended Articles


