


Tesla Stock Forecast: Cybercab Shift Puts $338.30 Support in Focus
TradingKey - Tesla’s (NASDAQ: TSLA) weekend outlook centres on a change in factory priorities: Cybertruck production in Texas is set to give way to more Cybercabs. When markets reopen Monday, investors will be weighing that autonomy strategy against weak operating profitability and a damaged daily chart.
The latest verified completed close at the research cutoff was $343.69, according to historical trading data. Friday’s session had not finished, so this is a pre-weekend reference rather than the final weekly close. The immediate chart test is whether buyers can defend $338.30.
Cybercab Must Justify the Factory Shift
Reuters reported that Elon Musk plans to wind down Texas Cybertruck production around mid-2027 to accommodate increased Cybercab output. He did not establish whether Cybertruck production would move elsewhere or end altogether.
Reusing factory capacity could improve returns, but only if the replacement programme generates enough paid demand. Investors need evidence on utilisation and running costs before treating the shift as an earnings upgrade.
Flat Revenue Leaves Little Room for Higher Costs
Tesla’s third-quarter update reported revenue of $28.05 billion, essentially unchanged annually. GAAP diluted EPS fell 44% to $0.22, compared with adjusted EPS of $0.48. Operating margin declined to 2.6% from 5.8%.
That leaves a narrow profit base to support expensive new programmes. I would give more weight to sustained operating-margin recovery than to production ambitions alone. Higher output helps shareholders only when the revenue covers manufacturing, development and commercial costs.
Tariff Refunds Complicate the Margin Improvement
The quarterly filing showed automotive gross margin rising to 18.5% from 17.0%, helped by $260 million of tariff refunds reducing automotive sales costs. Regulatory-credit revenue fell 73%, making the underlying vehicle economics particularly important.
Energy revenue declined 16% to $2.88 billion, although gross margin reached 33.1%. Energy costs benefited from another $526 million in tariff refunds. These benefits should not be projected forward as recurring cost savings.
Tesla also reported record energy-storage order rates and backlog. That supports future demand, but orders still have to become installations and collections. The gap between strong bookings and lower recognised revenue makes delivery timing and customer pricing important checks on the growth case.
Positive Cash Flow Needs a Spending Check
The company’s cash-flow summary showed $6.26 billion in operating cash flow and $4.73 billion of capital expenditure, leaving $1.53 billion in free cash flow.
Reuters’ earnings report said Tesla cut its annual capital-spending forecast to approximately $20 billion from more than $25 billion, without identifying every area receiving less investment.
Lower spending can reflect efficiency or postponed projects. Both support current cash flow, but delays could push future revenue further away. The next results need to show that cash preservation is compatible with delivering the new product plans.
Robotaxi Progress Is Separate From Supervised FSD
Tesla’s operational update said Cybercabs began providing Austin Robotaxi rides on September 3. Separately, FSD (Supervised) attachment exceeded 75% of new North American vehicle deliveries. Tesla explicitly states that this supervised product requires active driver supervision and does not make vehicles autonomous.
The distinction prevents software adoption from being mistaken for driverless-fleet scale. Paid rides, servicing expenses and regulatory permissions will provide better evidence of commercial progress than a growing fleet alone.
SpaceX Talks Add an Unresolved Valuation Question
Reuters’ merger coverage confirmed that both companies formed special committees, but transaction terms had not been agreed and a combination might never happen.
Potential benefits cannot be valued sensibly without exchange terms and governance arrangements.
Next Week’s Test Is Confidence in Execution
The Cybertruck announcement gives investors a fresh decision to assess when trading resumes. Clarification of factory timing and Cybercab economics would help distinguish a practical capacity shift from another programme requiring substantial upfront investment.
Beyond next week, fourth-quarter deliveries and earnings are the next major operating checkpoints. Tesla’s investor calendar did not establish a confirmed next reporting date at the research cutoff. Margin quality and cash conversion will matter alongside vehicle volumes.
Tesla Technical Analysis: $338.30 Holds the Immediate Downside Test
Tesla’s supplied daily chart shows a triangle breakdown, with price falling through the pattern’s rising lower boundary to the $343.69 reference close. The selloff reached $338.15 before buyers recovered some ground, leaving $338.30 as the immediate support test for the next regular session.
I remain bearish while rebounds fail beneath the broken triangle. A daily close below $338.30 would confirm further weakness towards $316.57, with $297.32 the next marked support. Holding the first level may produce a bounce, but does not by itself repair the breakdown.
RSI, a momentum gauge, stands at 35.81 and signals weakness without being oversold. MACD has crossed below its signal line and shows a negative histogram, supporting the bearish reading. The first recovery barrier is $373.49, followed by $391.92.
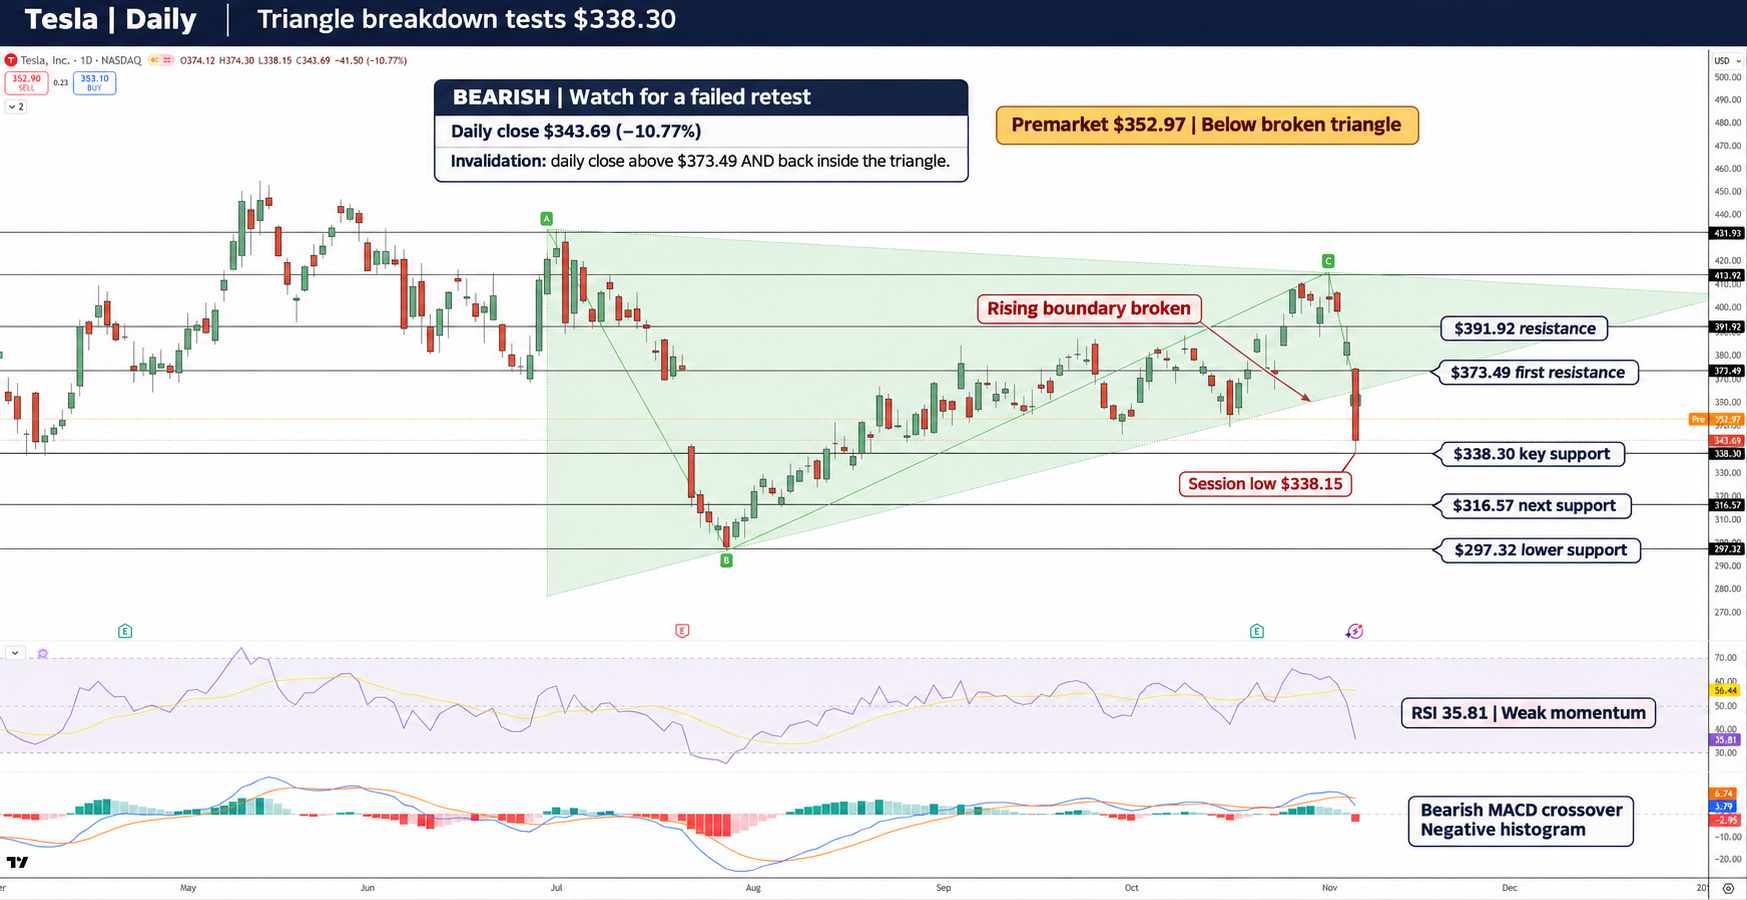
TSLA Price Chart - Source: Tradingview
A daily close above $373.49 and back inside the triangle would invalidate the immediate breakdown view. Monday’s opening price and any retest should be assessed against these conditions, rather than treating a temporary rebound as confirmation that buyers have regained control.
Key Levels
- Latest verified completed close: $343.69 at the pre-weekend research cutoff
- Immediate resistance: $373.49
- Upside recovery target: $391.92
- Immediate support: $338.30
- Downside targets: $316.57 and $297.32
- RSI: 35.81, weak but not oversold
FAQ
Is Tesla ending Cybertruck production entirely?
The announced plan concerns winding down Texas production around mid-2027. Relocation or a complete discontinuation remains unconfirmed.
What would improve Tesla’s technical outlook?
A daily close above $373.49 and back inside the triangle would invalidate the immediate bearish setup.
Bottom Line
Cybercab offers a growth opportunity, but recurring margins and cash returns must support it. The chart remains bearish beneath $373.49; a daily break below $338.30 would favour $316.57 next.
Recommended Articles


