


American Express vs. PayPal: Which Financial Stock Is a Better Buy for 2027?
Key Points
American Express maintains a premium brand position with high-spending customers and a closed-loop payments network.
PayPal offers massive global scale through its two-sided network of over 400 million active consumer and merchant accounts.
Which payments stock is the better choice for your portfolio heading into 2027?
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
The payments landscape is evolving rapidly as traditional financial giants face off against digital-first innovators. Investors must decide if the premium resilience of American Express (NYSE:AXP) or the digital reach of PayPal (NASDAQ:PYPL) offers better value today.
American Express caters to high-net-worth individuals and corporate clients through a unique integrated model. PayPal remains a leader in online transactions and mobile payments, processing trillions in volume. Comparing their growth and risk profiles helps clarify which fits a 2027 investment horizon.
The case for American Express
American Express operates a unique integrated payments model, acting as both the card issuer and the network operator. This closed-loop system allows it to capture the full value of every transaction while gathering proprietary data on high-spending consumers and businesses. A key pillar of its growth strategy is its partnership with Delta Air Lines (NYSE:DAL), which serves as its largest strategic partner. Customer concentration like this adds a layer of risk to the business, but it also provides a steady stream of premium, loyal cardholders.
Financial performance remains robust as the company expands its merchant network and refreshes its card offerings. In fiscal 2025, revenue reached nearly $80.5 billion, representing growth of approximately 8.4% compared to the prior year. The company reported net income of roughly $10.8 billion for the period, resulting in a net margin of 13.5%. These figures highlight a consistent ability to generate profit from its high-fee credit products and merchant discount revenue.
The balance sheet reflects the specific requirements of a large financial institution. As of Amex’s December 2025 balance sheet, the debt-to-equity ratio -- which measures total debt divided by shareholder equity -- was roughly 1.7. Its current ratio, a metric that tracks the ability to cover short-term debts with short-term assets, was approximately 0.3. In fiscal 2025, the company generated roughly $16 billion in free cash flow, which is cash from operations minus capital expenditures.
The case for PayPal
PayPal maintains a massive two-sided network that connects roughly 439 million active accounts across more than 200 global markets. The company provides essential digital tools for both consumers and merchants, including its namesake checkout service and the popular Venmo app. It is a dominant player among fintech stocks, focusing on making digital money movement simple and personalized. Its merchant solutions include branded and unbranded checkout options that help businesses of all sizes accept global payments.
Top-line growth has continued as the company prioritizes high-margin transaction services and cost discipline. In fiscal 2025, revenue reached approximately $33.2 billion, reflecting nearly 4.3% year-over-year growth. The company delivered net income of close to $5.2 billion, achieving a net margin of roughly 15.8%. While its revenue growth rate is lower than some younger competitors, its high net margin indicates a mature and profitable business model.
PayPal maintains a healthy liquidity position to support its global operations. According to its December 2025 balance sheet, the company carried a debt-to-equity ratio of approximately 0.5. Its current ratio was roughly 1.3, suggesting a comfortable cushion for meeting its immediate financial obligations. For fiscal 2025, the company produced close to $5.6 billion in free cash flow, providing ample capital for share buybacks or further product innovation.
Risk profile comparison
American Express faces intense global competition from other payment networks like Visa (NYSE:V) and Mastercard (NYSE:MA), as well as emerging alternative payment providers. It deals with significant dependence on key business partners, particularly its co-branded relationship with Delta Air Lines. Geopolitical instability and trade wars also pose risks, as these events can disrupt global travel and reduce the billed business volume from its premium cardholders. Additionally, as a highly regulated financial institution, it must manage ongoing compliance costs and strict data protection requirements.
PayPal must navigate a landscape of sophisticated cybersecurity threats and potential system outages that could damage its reputation and lead to financial loss. The company faces stiff competition from established tech giants like Amazon (NASDAQ:AMZN) and new disruptive technologies that could change how consumers pay. Extensive global regulatory and licensing requirements add complexity to its operations, particularly regarding anti-money laundering laws. Furthermore, its credit product offerings expose the company to potential borrower defaults and legal challenges regarding how it manages those receivables.
Valuation comparison
PayPal currently appears significantly cheaper than American Express based on both earnings and sales multiples, suggesting the market is pricing in slower growth for the digital payment pioneer.
| Metric | American Express | PayPal |
|---|---|---|
| Forward P/E | 17.5 | 10.2 |
| P/S ratio | 2.5 | 1.4 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
Which stock would I buy for 2027?
PayPal's valuation is clearly lower than Amex's; investors evidently don't see the former growing much from here. While I don't think historical stock performance necessarily dictates future stock performance, I kind of understand why investors are willing to give American Express a premium valuation relative to PayPal.
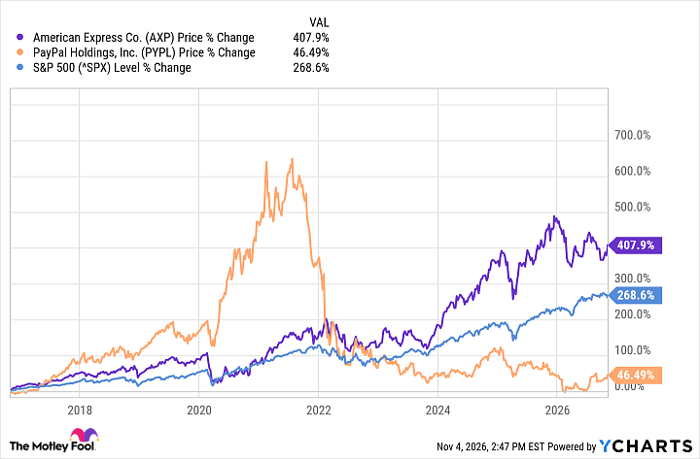
AXP data by YCharts
Over the past 10 years, Amex has outperformed PayPal by more than 250 percentage points. Worse yet, PayPal hasn't even kept pace with the broader market, trailing the S&P 500 badly in that time frame. Indeed, PayPal's returns barely outpaced inflation over the past decade. The payments specialist has been a pretty terrible investment.
I concede that Amex's single-digit revenue growth is not super exciting in and of itself. Its net margin is also just fine. But I will take a good-enough company over a stagnating stock any day. American Express gets my vote for 2027.
Should you buy stock in American Express right now?
Before you buy stock in American Express, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and American Express wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $342,020!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,270,017!*
Now, it’s worth noting Stock Advisor’s total average return is 885% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 5, 2026.
American Express is an advertising partner of Motley Fool Money. Erin Kennedy has positions in Mastercard and Visa. The Motley Fool has positions in and recommends Amazon, American Express, Mastercard, PayPal, and Visa. The Motley Fool recommends Delta Air Lines and recommends the following options: short December 2026 $62.50 calls on PayPal. The Motley Fool has a disclosure policy.
Recommended Articles


