


Ford's Next Growth Engine Could Already Be in Your Driveway
Key Points
While Q3 vehicle sales dropped 6.6%, active subscriptions jumped 40% year over year.
The Detroit-area automaker's software and services revenue set a quarterly record.
Rival GM gives a little more transparency with similar services, OnStar and Super Cruise.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
For Ford Motor Company (NYSE: F) investors, the exciting part of selling a truck used to be, well, selling the truck for the juicy margins that it hauled. Then the customer drove away, and everyone hoped they would return when it was time for another one.
Ford increasingly wants the relationship to last beyond those purchases, and it could help change the narrative about operating in a low-margin industry by boosting the high-margin services Ford is hoping to grow. Software subscriptions and connected services give the automaker more ways to earn money after the initial sale, and as mentioned, these often come with much higher software-industry-like margins.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Its latest results suggest that opportunity is becoming more than something management puts on an earnings presentation. Rival General Motors (NYSE: GM) offers an encouraging example of what it could become.
The sale isn't the finish line
Ford reported more than 1.7 million active paid software subscriptions through September, increasing more than 40% year over year. Meanwhile, its U.S. Q3 vehicle sales declined 6.6%, emphasizing the growth opportunity beyond the sale. The figures measure different activities, but the contrast is useful in showing that software growth doesn't have to move in lockstep with new U.S. vehicle sales.
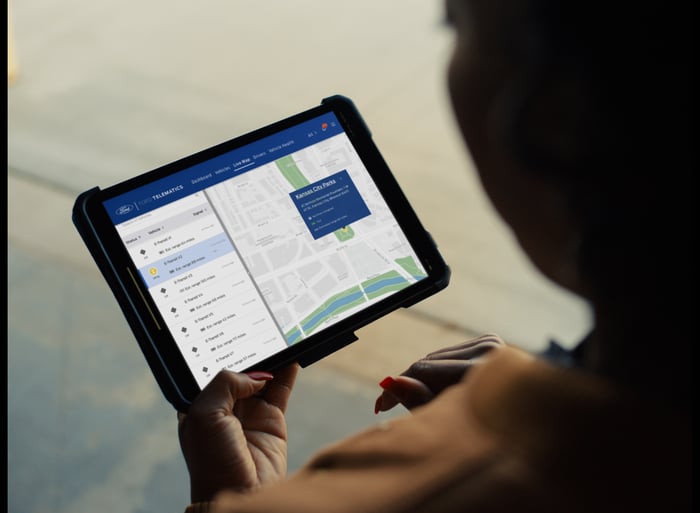
Ford Pro has been a driver of its services and subscriptions. Image source: Ford Motor Company.
Ford also reported record quarterly software-services revenue, with BlueCruise and connectivity leading that business's revenue growth, although it didn't disclose specific revenue numbers. However, that still matters because Ford can sell useful services throughout a vehicle's ownership period. It doesn't need to manufacture another lucrative F-150 every time it wants to sell another month of service subscription. GM, on the other hand, did disclose more specific numbers to consider.
GM shows the money!
GM's OnStar business generated more than $800 million in recognized revenue during Q3, increasing 15% year over year. Within that business, Super Cruise revenue grew approximately 60%, with management targeting roughly $400 million for the full year. That's real revenue, rather than another shiny technology that executives promise will eventually make money.
There's more revenue waiting in the wings. GM ended Q3 with $6.8 billion in deferred revenue from OnStar services, including Super Cruise, up roughly 40% year over year. That represents revenue it hasn't earned yet because it still needs to deliver the services. For example, when a vehicle purchase includes several years of the service, GM allocates part of the sale to those services and recognizes that revenue over time. It gives investors better visibility into future revenue, although the costs of providing those services still have to come out.
Ford's subscription count isn't directly comparable with GM's broader OnStar base. But the investment opportunity is similarly focused on earning more from vehicles already in customers' driveways. This opportunity has the potential to grow alongside the adoption of electric vehicles (EVs), which are typically far more advanced in software, technology, and over-the-air update capabilities.
What it all means
Nobody needs another subscription just because they already own an expensive truck. We all have a seemingly ever-increasing number of subscriptions. These services have to earn their keep through convenience, useful features, or helping businesses keep vehicles working. Ford hasn't disclosed a stand-alone software profit margin in these results, either. Developing and maintaining those services costs money.
Still, growing paid subscriptions at Ford and rising digital revenue at GM give investors something concrete to watch. It also helps Ford and GM slowly change the narrative that the automotive industry is forever a low-margin business, but these services will have to substantially grow over the next decade to expand not only their contribution to the automakers' top and bottom lines, but to expand into a larger piece of overall fleets on the road. It will take years to increase the penetration of these services.
Look for continued growth, customers renewing after introductory periods, and evidence that the additional revenue supports stronger profits and hopefully higher overall margins. The truck sale still matters, but what happens after the customer takes the keys should matter more and more going forward.
Should you buy stock in Ford Motor Company right now?
Before you buy stock in Ford Motor Company, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Ford Motor Company wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $342,020!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,270,017!*
Now, it’s worth noting Stock Advisor’s total average return is 885% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 4, 2026.
Daniel Miller has positions in Ford Motor Company and General Motors. The Motley Fool recommends General Motors. The Motley Fool has a disclosure policy.
Recommended Articles


