


【US Pre-Market】Three Major Index Futures Rebound; SpaceX and Tesla Fall Over 5%; Gold Reclaims $4,000 Ahead of ADP Data
TradingKey - On November 4, US Eastern Time, the three major US stock index futures rebounded after overnight losses. Following the Democrats winning control of both houses of Congress, market concerns over stricter AI regulation and data center construction constraints temporarily drove Nasdaq 100 Index futures down by as much as 2.4% intraday. Subsequently, Trump accepted the election results, easing market fears of escalating political confrontation.
As of press time, Dow futures were up 1.58%, S&P 500 futures rose 0.83%, and Nasdaq 100 Index futures gained 0.21%.
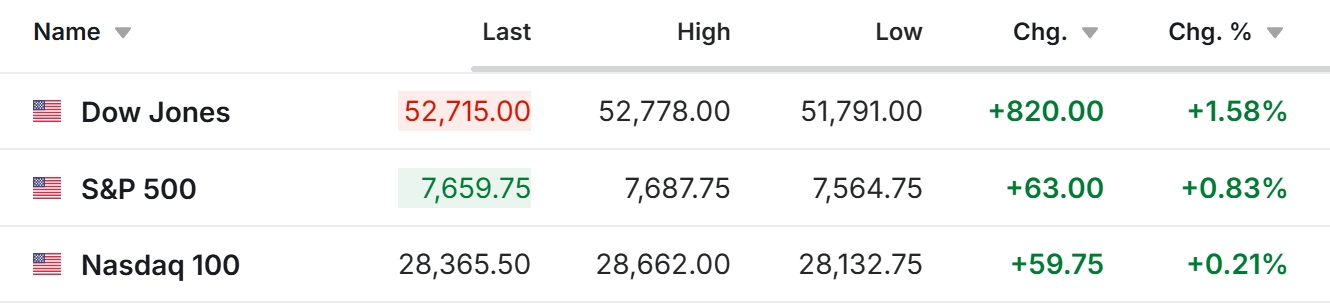 [Source: Investing]
In commodities, a weaker US dollar and declining US Treasury yields pushed gold (XAUUSD) up by about 3%, now rising to around $4,041/oz. The 10-year US Treasury yield fell to around 4.93%. Brent crude (UKOIL) fell about 1.4% to $101.20/barrel, and WTI crude (USOIL) also retreated, now at $94.51/barrel. Bitcoin (BTCUSD) is currently trading near $78,590.
Market Moves
Tesla (TSLA) and SpaceX (SPCX) both fell over 5% in pre-market trading.
Following the US midterm elections, market concerns grew that Congress might step up scrutiny of government contracts for Elon Musk's companies, and Texas data center approval policies could also change. In addition, a potential merger between Tesla and SpaceX could face stricter regulatory scrutiny, sending shares of both companies down over 5% in pre-market trading.
AMD (AMD) surged over 6% in pre-market trading at one point, with Q4 revenue guidance reaching $17 billion.
AMD's third-quarter revenue grew 45% year-over-year to $13.377 billion, with non-GAAP EPS of $2.09. Data center revenue reached $8.5 billion, up 97% year-over-year. The company expects fourth-quarter revenue to be approximately $17 billion, plus or minus 3%, and projects overall revenue growth of about 80% in 2027. Strong performance and growth guidance pushed AMD's stock price up in after-hours trading.
Amdocs (DOX) plunged over 40% after hours as a T-Mobile contract dispute weighed on its earnings outlook.
Amdocs expects fiscal 2027 reported revenue to fall 14.3% to 17.9% year-over-year; adjusted constant-currency revenue is expected to decline 7% to 11%, and adjusted EPS is projected to decrease 26% to 30%. Both parties allege that the other breached relevant agreements and may seek to terminate the contract or resolve disputes through arbitration, raising market concerns that this could further impact company revenue and profits.
Skyworks Solutions (SWKS) fell over 15% after hours on weak post-merger performance guidance.
Skyworks' fourth-quarter fiscal revenue reached $1.046 billion, and non-GAAP EPS was $1.28, slightly above market expectations. However, for the first quarter following its merger with Qorvo, the company expects revenue of $1.8 billion to $1.9 billion, with a midpoint EPS of $1.25. The market remains focused on integration costs, financing expenses, and margin improvements.
Duolingo (DUOL) rose over 12% in pre-market trading, with daily active users up 29%.
Duolingo's third-quarter revenue grew 14% year-over-year to $309 million, with daily active users reaching 64.9 million and paid subscribers reaching 13.1 million. The company stated that its main financial metrics for the third quarter exceeded expectations. However, adjusted EBITDA fell 2% year-over-year to $78.7 million, and free cash flow dropped 3% to $75.3 million, with ongoing attention needed on whether user growth can convert into higher profits.
Curis (CRIS) surged over 70% in pre-market trading, with attention focused on a reverse stock split vote and clinical data expectations.
Curis jumped about 70.7% in pre-market trading, with its stock price reaching around $1.22. The company plans to hold a shareholder meeting on November 18 to consider a 1-for-5 to 1-for-25 reverse stock split to meet Nasdaq's minimum bid price requirement. In addition, the company expects to release preliminary clinical data for its drug candidate emavusertib in treating chronic lymphocytic leukemia before year-end. A low public float could amplify stock price volatility.
Market News
Democrats Win Both Houses of Congress, Posing Policy Shifts for AI Data Center Construction and Tech Regulation.
Results from the U.S. midterm elections on November 3 show that Democrats have won control of both the House of Representatives and the Senate. In the Texas gubernatorial election, Democratic candidate Gina Hinojosa also defeated incumbent Republican Governor Greg Abbott.
Markets are focusing on potential changes in tech regulation, data center approvals, and energy policies that could be pushed by the new Congress and state governments. Texas is a key region for U.S. data center development, and Hinojosa had previously proposed a moratorium on new data center projects. If implemented, such policies could impact local data center expansion, power supply, and AI infrastructure investment.
However, state policies and federal legislation operate at different levels, and the election results do not mean that U.S. data center construction will face immediate, comprehensive restrictions.
Oracle Reportedly Cancels $7 Billion AI Chip Lease Deal with Tencent as Cross-Border Compute Cooperation Faces Regulatory Pressure.
According to a Financial Times report on November 4, Oracle (ORCL) has canceled a previously agreed five-year AI chip lease agreement with Tencent, valued at approximately $7 billion, which originally planned to supply Tencent with up to 100,000 advanced AI chips via Oracle's data centers in Southeast Asia.
According to reports, U.S. officials had expressed security concerns to Oracle, while authorities in Guangdong Province had also urged Tencent to support domestic chips. The cancellation means Oracle loses a potentially massive cloud computing business opportunity and underscores growing U.S. regulatory scrutiny over the cross-border use of advanced AI chips.
Neither Oracle nor Tencent has officially confirmed the reports, and Reuters has not independently verified them.
Meta Completes $15 Billion U.S. Dollar Bond Offering, Launches Inaugural Euro Bond Financing.
Meta (META) completed a $15 billion U.S. dollar bond issuance on November 3, attracting up to $58 billion in investor orders, approximately 3.9 times the offering size. On November 4, the company further launched its inaugural euro bond sale, planning to raise funds across six maturity tranches ranging from over 4 years to more than 38 years, with expected proceeds equivalent to $5 billion to $10 billion.
The euro bond sale is underwritten by Citigroup and Morgan Stanley, with pricing expected later on November 4. Meta continues to fund its AI data center and computing capacity construction through debt financing, but yields demanded by investors have ticked up, reflecting market focus on growing debt loads at big tech companies and returns on AI investments.
Google Plans $15 Billion Investment to Expand AI Data Centers in Malaysia.
Alphabet's Google announced on November 4 that it plans to invest $15 billion in Malaysia between 2027 and 2028 to build new data center campuses, expand cloud computing capacity, and support local clean energy, water security, and workforce training.
The new campuses are planned for the states of Selangor and Negeri Sembilan. Google projects that during construction, the investment will contribute approximately $1.1 billion annually to Malaysia's GDP and support over 37,000 local jobs; once operational, it is expected to sustain more than 9,000 jobs per year. Additionally, the company plans to add over 1 gigawatt of clean energy capacity to the local power grid and train about 800,000 local residents over the next five years.
This investment will expand Google's AI computing power and cloud services footprint in Southeast Asia while intensifying competition in the regional data center market with rivals such as Microsoft and Amazon.
Important Events Preview
US Eastern Time | Event |
Nov 4, 8:15 AM | US October ADP Private Employment |
Nov 4, 8:30 AM | US September International Trade Data |
Nov 4, 8:30 AM | US Treasury Announces Quarterly Refunding Plan |
Nov 4, 9:45 AM | US October S&P Global Final Services PMI |
Nov 4, 10:00 AM | US October ISM Services PMI |
Nov 4 Pre-market | McDonald's (MCD), Uber (UBER), CVS Health (CVS) report earnings |
Nov 4 Post-market | Qualcomm (QCOM), AppLovin (APP), Datadog (DDOG), Arm (ARM) report earnings |
Recommended Articles


