


Prediction: TSMC Stock Is Going to $1,200 by 2030
Key Points
TSMC crushed expectations and raised its 2026 guidance last week.
The AI infrastructure build-out will drive outstanding growth for TSMC through 2030.
Analysts have become more bullish about TSMC's growth potential, suggesting that the stock can soar incredibly over the long run.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Artificial intelligence (AI) stocks are in correction mode right now, driven by multiple factors, including high interest rates, a hotter-than-expected inflation report that could prompt further rate hikes, and concerns about the rising cost of financing the AI infrastructure build-out.
However, the actual results from AI industry bellwethers suggest otherwise. Taiwan Semiconductor Manufacturing (NYSE:TSM), the world's leading semiconductor foundry, released its third-quarter results on Oct. 15. TSMC is at the epicenter of the AI boom, manufacturing chips for leading chip designers and consumer electronics companies. Its numbers exceeded expectations, and the guidance indicates the growth rate is poised to accelerate.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
I won't be surprised to see this semiconductor stock emerge stronger from the recent sectorwide sell-off and soar by 2030. Let's look at the reasons why TSMC could step on the gas and jump nearly 3x by the end of the decade to hit $1,200.

Image source: Taiwan Semiconductor Manufacturing.
TSMC accelerating growth is great news for investors
TSMC's Q3 revenue increased 41% year over year to $46.7 billion. Even better, the company's net profit margin increased to 51.1% last quarter from 45.7% in the year-ago period. As a result, TSMC's earnings per share jumped by 57% from the year-ago period to $4.60.
Importantly, TSMC sees its growth rate picking up nicely this quarter. It expects $53.3 billion in Q4 revenue at the midpoint of its guidance range, implying a 58% increase over the prior-year period. Also, TSMC sees its operating margin at 57.5% in the current quarter, an improvement of 3.5 percentage points over last year.
The improvement in TSMC's revenue growth rate and its expanding margins can be attributed to the robust demand for the company's advanced chips used in AI data centers. TSMC management cited multiple AI-related catalysts driving growth. The emergence of agentic AI applications, the growing demand for server central processing units (CPUs) that run inference workloads, and the need for networking components to connect AI chip clusters and data centers are all boosting the demand for TSMC's chips.
It is worth noting that TSMC got 69% of its revenue from the advanced 2-nanometer (nm), 3nm, and 5nm nodes combined in the previous quarter. That was an improvement over the 60% revenue contribution from these nodes in the year-ago period. Notably, the company began recognizing revenue from the 2nm node last quarter and is now planning to aggressively ramp up output of chips manufactured using this process node.
The shift toward the 2nm node should be a tailwind for the company's revenue and earnings in the long run. That's because the 2nm node reportedly commands a 50% premium compared to the 3nm node. Also, TSMC has been gradually increasing the prices of its advanced process nodes. The Taiwanese giant is reportedly planning to implement a 5% to 10% price increase next year for advanced nodes, along with a 10% to 15% increase in advanced packaging prices. The higher prices should eventually filter down to the company's bottom line.
Another important point is that TSMC management expects its AI-related revenue to grow faster than the mid-to-high 50% compound annual growth rate (CAGR) it originally estimated through 2029. As such, it is easy to see why analysts have increased their earnings per share (EPS) expectations from TSMC.
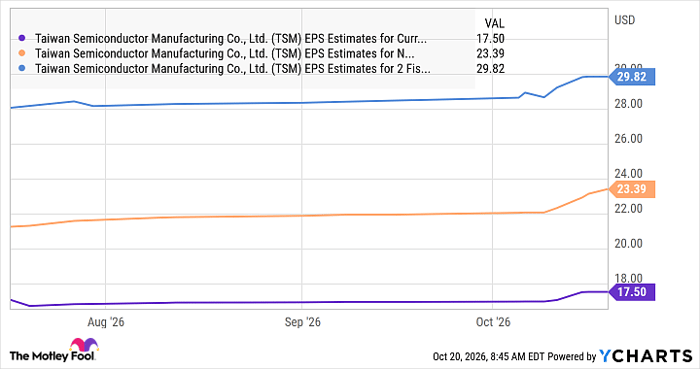
TSM EPS Estimates for Current Fiscal Year data by YCharts
The math behind a $1,200 stock price
The above chart indicates that TSMC's earnings could increase to $29.82 per share in 2028. The company delivered EPS of $10.65 in 2025, indicating its bottom line is on track to grow at a 40% CAGR through 2028.
Importantly, analysts expect TSMC to maintain an identical growth rate over the long run.
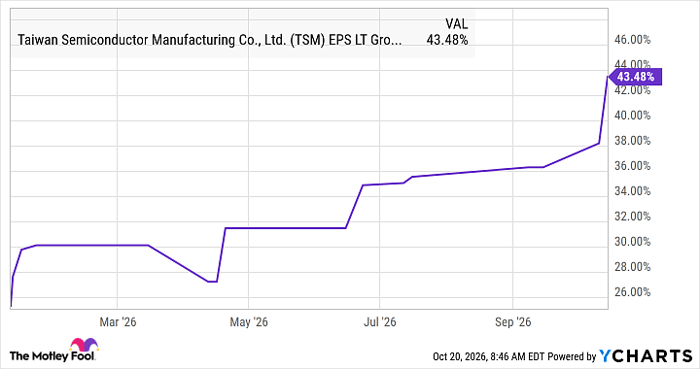
TSM EPS LT Growth Estimates data by YCharts
If TSMC's earnings increase by 43% in 2029 and 2030, its EPS could jump to $60.98 at the end of the forecast period (using 2028’s projected EPS as the base). The tech-laden Nasdaq-100 index has a forward earnings multiple of 22. Assuming TSMC trades at even 20 times earnings in 2030, its stock price could reach $1,219 (based on the $60.98 EPS estimate).
That implies a potential jump of nearly 3x in just over four years. So, this AI stock could surpass the $1,200 mark by 2030, suggesting investors should look at the bigger picture and consider buying TSMC for healthy long-term upside.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $376,696!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,333,920!*
Now, it’s worth noting Stock Advisor’s total average return is 925% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 21, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


