


Netflix earnings land tonight: the $70 line that decides whether the AI rebound has legs
Mitrade Insights — Netflix reports third-quarter results after the US close tonight, and the setup is unusually binary for a $70 stock. Shares closed at $69.85 (-0.96%) on Monday, just below the $70 round number and roughly 44% below their 52-week high of $124.86, while options imply an 8.4% one-day move. The broader tape has already made its bet: the Nasdaq rose 1.11%, the SOX jumped 1.61% to snap an eight-day slide, and Amazon gained 5% after Morgan Stanley raised its target to $350. Tonight, Netflix has to confirm that the rebound is about earnings, not just positioning.
1. The setup: a $70 stock with an 8.4% options move
Netflix is not an AI infrastructure name, but it sits in the same growth bucket that has driven the Nasdaq's 2026 run. The stock peaked at $124.86 inside the past year and has since fallen about 44%, with the 20-day average at $70.32, the 50-day at $75.09 and the 200-day at $82.88 all above the current price. Monday's range was $69.02 ~ $70.22 — a tight coil around the $70 line.
That coil is why the options market is pricing an 8.4% move. At $69.85, that implies a one-day range of roughly $64 ~ $76, which spans both the 52-week low at $65.08 and the 50-day average at $75.09. In other words, the market is not pricing a small quarter; it is pricing a re-rating in either direction.
2. What the numbers need to show
| Metric | Q3 expectation | Context |
|---|---|---|
| Revenue | ~$12.87bn (+12% YoY) | Guidance was $12.86bn; FX-neutral growth ~11% |
| EPS | ~$0.82 | Net income ~$3.45bn |
| Operating margin | 33.2% | Up from 28.2% a year ago (tax-hit base) |
| FY revenue | $51.0 ~ 51.4bn | FY operating margin 31.5% |
| Free cash flow | ~$12.5bn | Full-year guidance |
| Ad revenue | ~$3bn target for 2026 | Roughly double 2025; not reported separately |
| Engagement | H1 viewing ~97bn hours, +2% | US TV share 7.8% in July vs 8.8% a year ago |
The revenue line is not the hard part — consensus is already at guidance. The hard parts are Q4 guidance, ad monetization and engagement. Netflix's ad-supported tier had more than 250 million monthly active viewers in May, up from 190 million in November 2025, but that measures viewers, not paying accounts. First-half viewing hours rose only about 2%, and Nielsen data showed the US TV-viewing share slipping to 7.8% in July. The company also cut roughly 1,000 jobs — about 6% of staff — so investors will want to see the cost savings without a hit to content momentum.
3. Why Netflix matters for the AI trade
Tonight is the opening act of a heavy earnings week: Tesla and Meta report Wednesday after the close, alongside IBM, Lam Research and Texas Instruments. FactSet puts S&P 500 Q3 earnings growth near 29% year on year, a bar that leaves little room for a miss. The AI trade has spent the past month wrestling with the same question — whether massive capital spending will translate into revenue and margins — and the memory-chip rout showed how quickly a strong fundamental story can be repriced.
Netflix is a useful test because it is a pure subscription-and-advertising model, not a capex story. If it beats and guides Q4 higher, the market can argue that the consumer and ad markets are holding up, giving the Nasdaq rebound a fundamental leg. If it misses or guides soft, the "AI rebound" starts to look like a positioning bounce in a market that is still expensive.
4. Levels: $70 is the gate, $65 is the floor
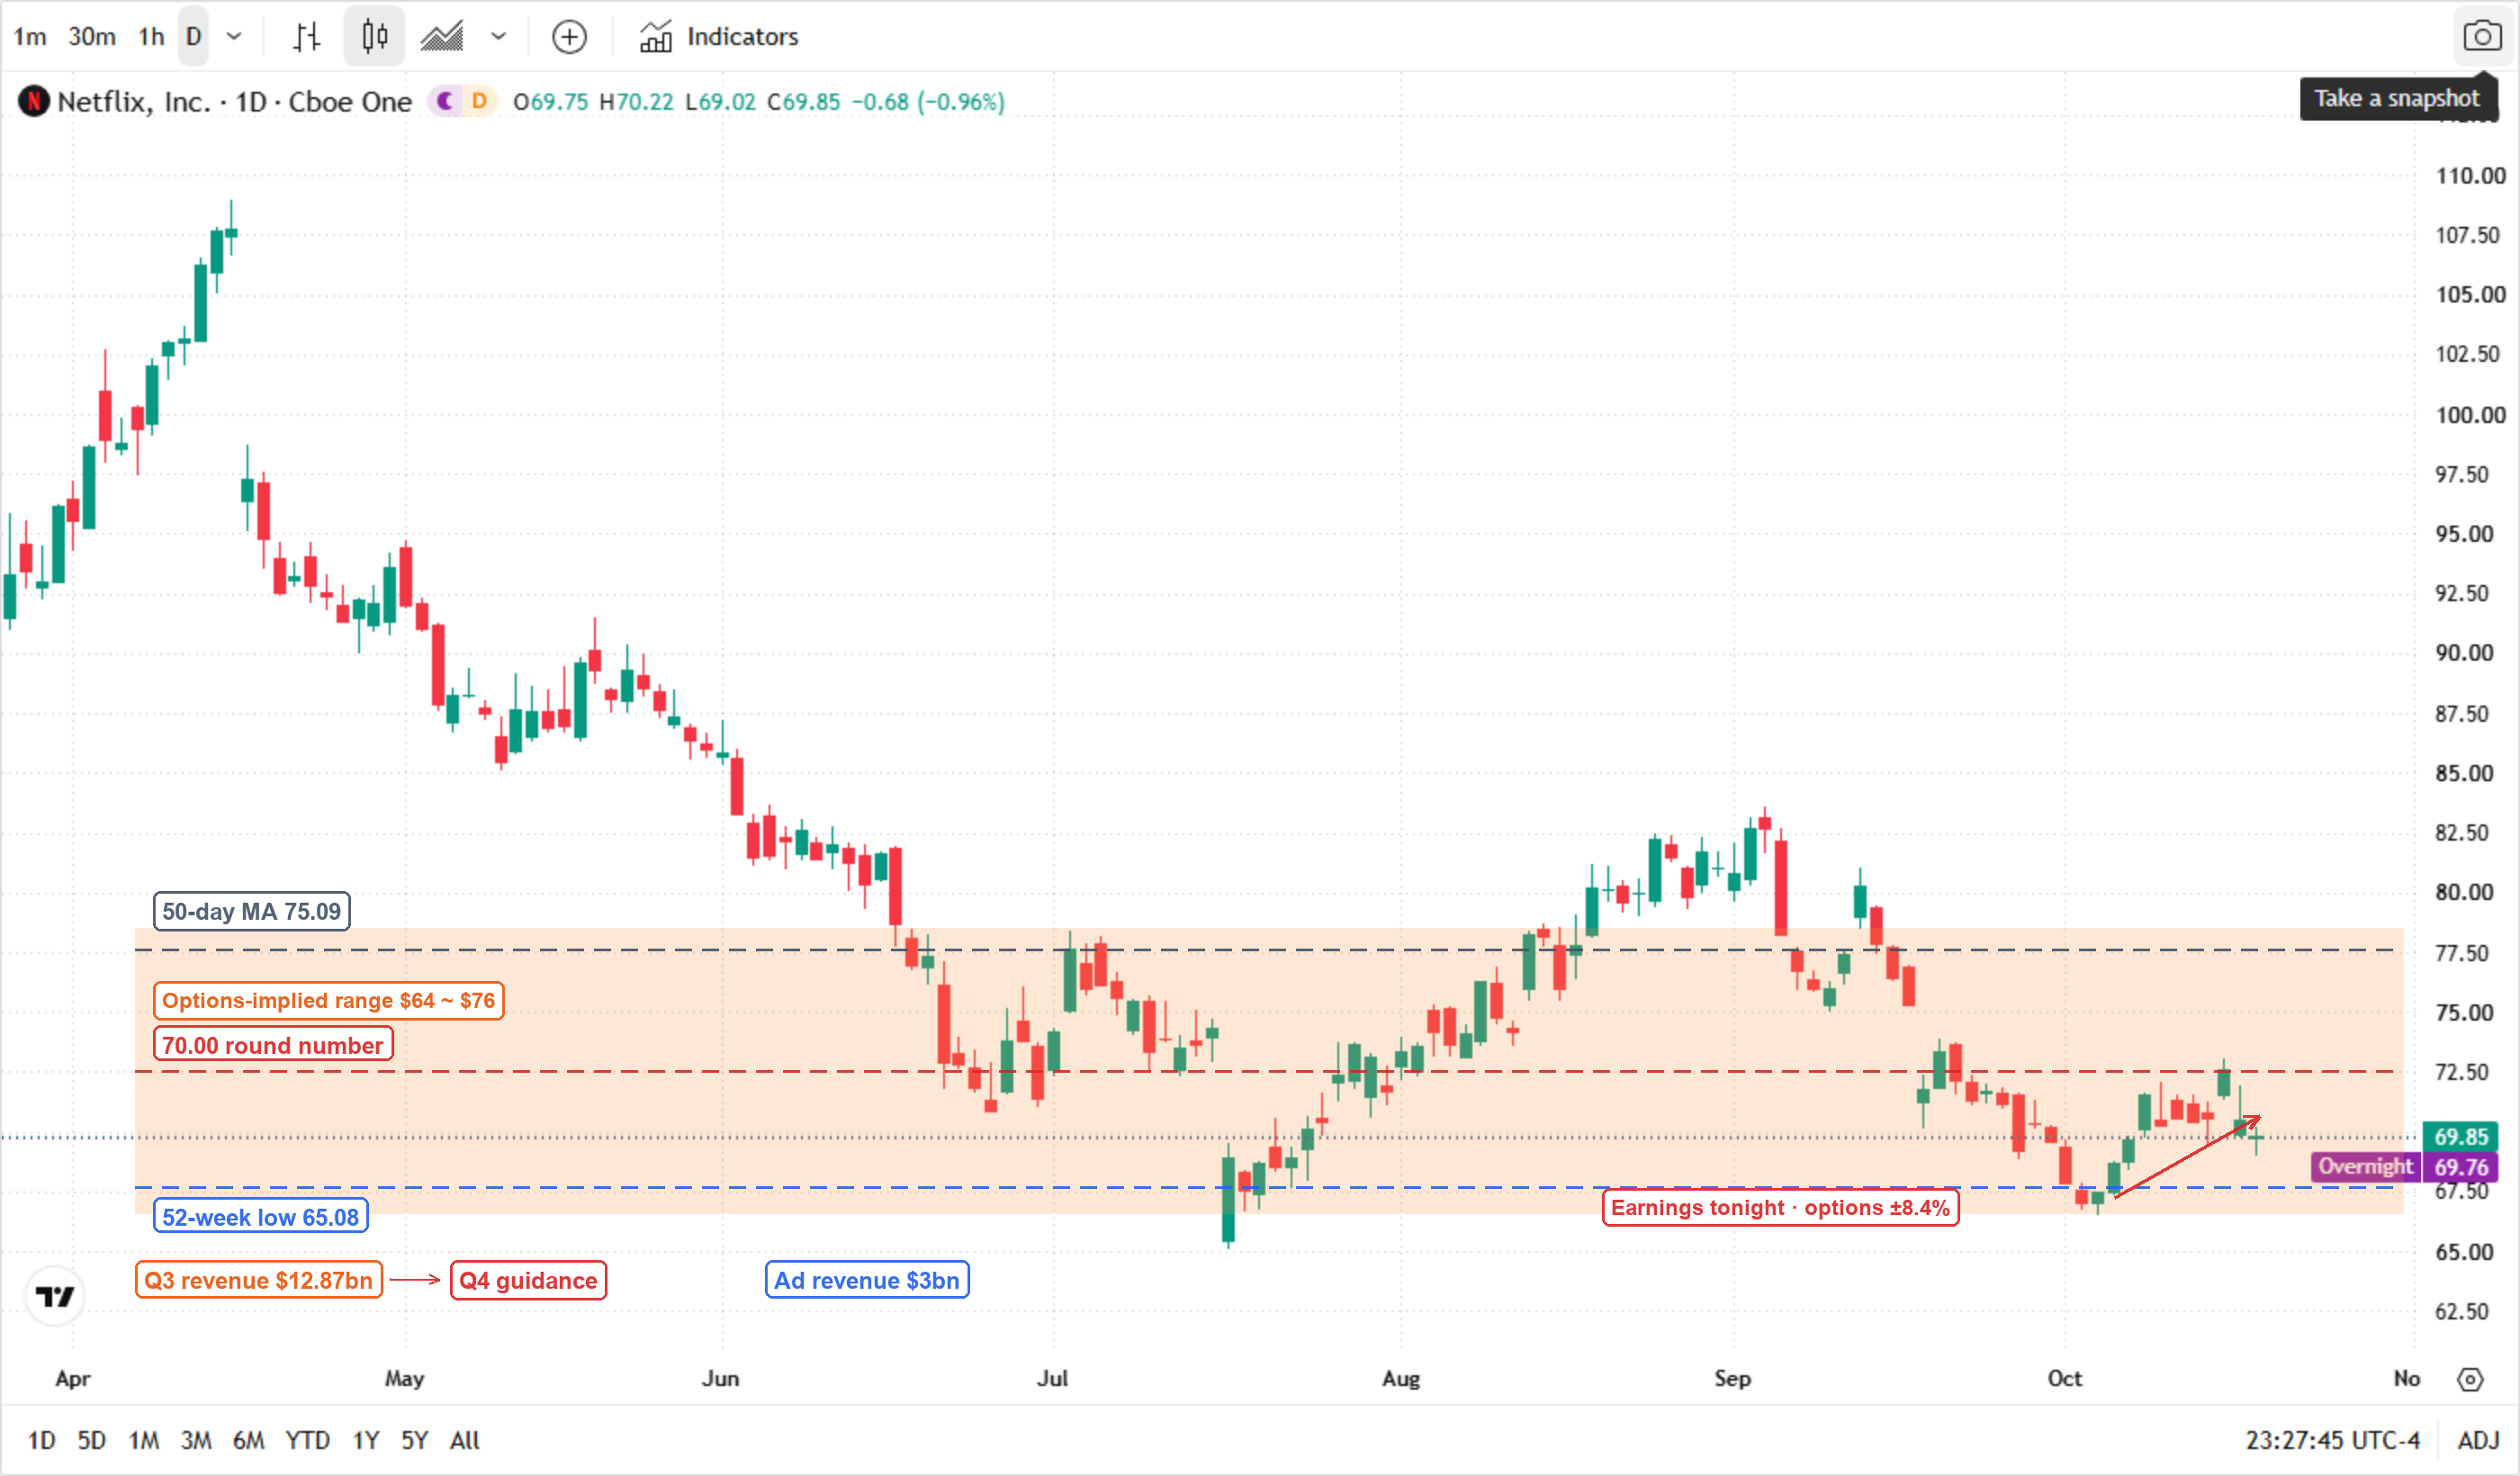
* Chart source: TradingView official chart screenshot, data source NASDAQ (Netflix).
The structure to respect: a close above $70.00 and the 20-day average at $70.32 would neutralize the immediate downtrend and open $75.09 (50-day). A break below $69.02 (Monday's low) puts $65.08 back in play; below that, the options-implied downside of $64 becomes the market's next reference. The stock is below all three major moving averages, so the path of least resistance is still lower until $70 is reclaimed.
5. Three checks, two scenarios
Q4 guidance. A guide above the current consensus would signal that pricing and advertising are offsetting slower membership growth; a soft guide would confirm the engagement concerns.
Ad monetization. The $3bn 2026 target is the bull case's second leg. Any hint that ad revenue is lagging — or that international expansion slips into 2027 — would undermine the re-rating story.
Cost savings and content. The 1,000 job cuts need to show up in margins without weakening the content slate. A margin beat with a content warning would be a mixed signal.
Scenario A: beat and raise. Revenue at or above $12.87bn, EPS above $0.82, Q4 guide solid — the stock clears $70.32 and tests $75.09, and the Nasdaq rebound gets its fundamental confirmation.
Scenario B: in-line quarter, soft guide. Revenue meets but Q4 guidance disappoints, or ad revenue slips — the stock loses $69.02 and retests $65.08, dragging the growth complex lower just as Tesla and Meta report.
The bottom line: Netflix is a $70 stock with an 8.4% options move and a 46% drawdown from its high. The quarter does not need to be spectacular; it needs to be good enough to keep $70. Everything else is a scenario.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


