


PayPal vs. SoFi Technologies: Which Financial Stock Is a Better Buy in 2026?
Key Points
PayPal continues to dominate the global digital payments market with a massive network of over 430 million active accounts.
SoFi Technologies has successfully pivoted into a full-service digital bank with high revenue growth and a new stablecoin settlement model.
Which fintech player offers the better balance of growth and value for your portfolio in 2026?
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
The digital finance landscape is shifting as traditional payment giants face off against aggressive new-age banking platforms. Deciding between PayPal (NASDAQ:PYPL) and SoFi Technologies (NASDAQ:SOFI) requires weighing mature cash flow against high-growth disruption.
PayPal remains the dominant force in global checkout, leveraging a massive network of merchants and consumers. SoFi has evolved from a student lender into a full-service digital bank, aiming to capture a larger share of the modern consumer's wallet. Both companies represent different stages of the fintech life cycle, making this a classic value-versus-growth comparison.
The case for PayPal
PayPal operates a vast two-sided network connecting 439 million active accounts across nearly 200 markets. The company provides branded checkout for consumers via digital wallets like Venmo and unbranded processing for merchants. Merchants also utilize PayPal for unbranded payment processing and "buy now, pay later" solutions to drive sales. By supporting transactions in approximately 140 currencies, it serves as a critical bridge for global commerce.
In fiscal 2025, revenue reached nearly $33.2 billion, representing year-over-year growth of roughly 4.3%. The company reported net income of $5.2 billion, with a net margin of approximately 15.8%. This growth builds on the momentum from fiscal 2024, when revenue was nearly $31.8 billion and net margin was 13%. This performance shows a steady upward trend in profitability compared to the previous fiscal year.
As of PayPal's December 2025 balance sheet, the debt-to-equity ratio is close to 0.5, indicating that for every dollar of equity, the company has 50 cents of total debt. The current ratio, which measures its ability to cover short-term debts with short-term assets, is approximately 1.3. A current ratio above 1 typically suggests that a company has sufficient liquid assets to meet its obligations over the next twelve months. Free cash flow, or cash from operations minus capital expenditures, reached nearly $5.6 billion in fiscal 2025.
The case for SoFi Technologies
SoFi Technologies operates a diversified digital suite offering personal loans, home loans, and brokerage services that distinguish it among fintech stocks. Through its Galileo and Technisys platforms, the company provides banking-as-a-service to other financial institutions. SoFi serves over 15 million members, helping them borrow, save, and invest through a single integrated application. Recently, the bank transitioned its $25 billion annual card program to a stablecoin settlement model using SoFiUSD (SOFID) in partnership with Mastercard (NYSE:MA).
In fiscal 2025, revenue reached roughly $4.8 billion, reflecting approximately 28.8% year-over-year growth. This rapid expansion follows a strong 2024, in which revenue increased from approximately $2.9 billion the previous year to nearly $3.7 billion. The company posted net income of nearly $481.3 million, yielding a net margin of close to 10.1%. While revenue climbed sharply, net income remained relatively stable compared to the $498.7 million reported in the prior year.
As of SoFi's December 2025 balance sheet, the debt-to-equity ratio is roughly 0.2, indicating the company has 20 cents of debt for every dollar of equity. The current ratio is approximately 0.2, meaning short-term liabilities exceed short-term assets. In the banking sector, a lower current ratio is often influenced by how a company manages its deposit liabilities against its loan assets. Free cash flow was negative at nearly $4 billion for the fiscal year, reflecting the heavy capital requirements of its lending and technology expansion.
Risk profile comparison
PayPal faces persistent threats from cyberattacks, data breaches, and system failures, according to its latest annual report filed for the most recent fiscal period. The company is also navigating extensive global regulations and ongoing securities class action lawsuits related to its financial outlook. Furthermore, the termination of acquisition talks with Advent and Stripe in August 2026 has left the company to compete as a stand-alone entity against traditional banks and disruptive rivals.
SoFi Technologies addresses operational risks in its latest annual report, filed for the most recent fiscal period, including difficulties integrating past acquisitions. The business is sensitive to interest rate fluctuations, which can impact loan defaults and the demand for personal lending. Additionally, the company faces regulatory oversight from the Federal Reserve and recent legal challenges involving allegations of trade secret misappropriation from Citizens Bank (NYSE:CFG).
Valuation comparison
PayPal trades at a lower multiple of future earnings estimates and sales over the past 12 months than SoFi, based on forward P/E and P/S ratios.
| Metric | PayPal | SoFi Technologies |
|---|---|---|
| Forward P/E | 10.4 | 25.6 |
| P/S ratio | 1.4 | 3.5 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
Which stock would I buy in 2026?
PayPal's valuation is certainly more attractive here, and conservative investors may appreciate that. However, it appears that shares are cheap for a reason: Revenue growth of just 4% or so is not very impressive.
In contrast, SoFi is growing at a nice clip, with revenue up almost 29% year over year in fiscal 2025. Its net margin doesn't compare favorably to PayPal's, but that is partly due to the fact that the two companies are in different stages of their life cycles. PayPal is relatively mature and established, while SoFi is an upstart in the fintech arena.
Both stocks have underperformed the S&P 500 over the past five years, with PayPal especially lagging:
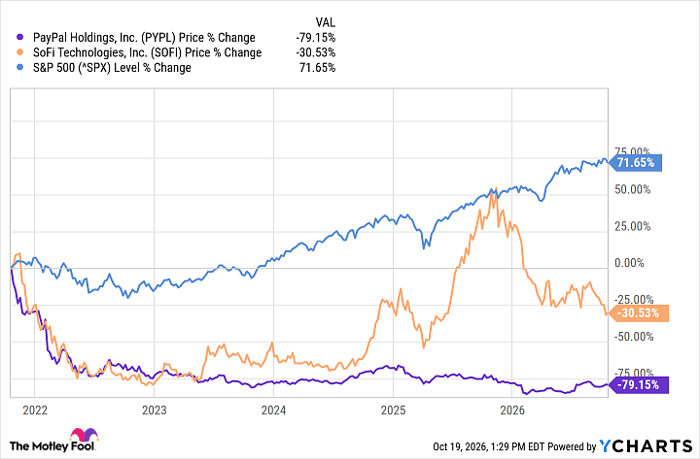
PYPL data by YCharts
Past performance is no indication of future results, of course. Even so, the point of buying individual stocks is the assumption they will outperform the broader market. Neither PayPal nor SoFi has.
If I had to buy one of these fintech specialists, I think SoFi offers better growth potential. But neither company looks especially compelling to me.
Should you buy stock in PayPal right now?
Before you buy stock in PayPal, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and PayPal wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $380,363!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,315,732!*
Now, it’s worth noting Stock Advisor’s total average return is 919% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 20, 2026.
Erin Kennedy has positions in Mastercard. The Motley Fool has positions in and recommends Mastercard and PayPal. The Motley Fool recommends the following options: short December 2026 $62.50 calls on PayPal. The Motley Fool has a disclosure policy.
Recommended Articles


