


Netflix Q3 Earnings Preview: Can Ad Revenue Offset Declining User Engagement? Wall Street's Highest Price Target at $125
TradingKey - Netflix (NFLX) will report its third-quarter 2026 financial results after the U.S. market close on October 20, Eastern Time. Facing pressures such as declining user viewing time, intensifying content competition, and a continuous stock price pullback, the market is closely watching whether the streaming giant can find new growth drivers.
According to the company's previously released guidance, Netflix's third-quarter revenue is expected to be $12.86 billion, up 11.7% year-over-year, with an operating margin projected to reach 33.2%. Market consensus estimates revenue at approximately $12.87 billion and earnings per share at around $0.82. Compared with revenue growth of around 13% in the second quarter, third-quarter growth may slow down further, but revenue contributions from price increases are expected to support earnings performance.
Price Hikes Support Margins as Revenue Growth Continues to Slow
From an earnings perspective, Netflix is expected to deliver relatively solid third-quarter results. Price adjustments previously implemented in markets such as the US, Mexico, and Spain will be more fully reflected in revenue this quarter, while the company's repurchase of approximately $4.7 billion in stock in the second quarter will also lend support to earnings per share.
However, expected revenue growth of about 11.7% would be lower than in the second quarter and could mark the lowest level for the same period in nearly three years. This means that although Netflix can still rely on price hikes, advertising, and subscriber scale to maintain double-digit growth, its traditional subscription business has entered a more mature phase.
Under these circumstances, the operating margin of 33.2% may draw more attention than the revenue figures. If the margin meets or exceeds guidance, it would indicate that price hikes, cost control, and business scale effects are still at work; if profit growth relies primarily on layoffs and spending cuts while viewership demand continues to weaken, the market may question the sustainability of such improvement.
Netflix recently announced that it will cut about 1,000 employees, representing approximately 6% of its global workforce, marking its largest round of headcount adjustments since 2022. The layoffs mainly affect departments including product, technology, legal, and human resources, reflecting management's reallocation of resources and a further shift in operational focus toward profitability efficiency and core content.
Ad Growth and Watch Time Engage in a Tug-of-War
As its subscriber base matures, advertising is becoming Netflix's most critical source of incremental revenue. The market expects that the company's advertising revenue could reach approximately $3 billion in 2026, doubling from the previous year. Expanding upfront ad commitments, improving programmatic buying tools, and a growing user base on ad-supported tiers all provide support for this goal.
However, whether advertising revenue can sustain its growth ultimately depends on user watch time; if user engagement with the platform declines, the ad inventory and value Netflix can sell will also be constrained. According to estimates by third-party research firms, Netflix subscribers spent an average of approximately 49 hours per month watching content in the first half of 2026, down significantly from 66 hours in the same period of 2023; over the same period, total platform watch time grew by only about 2%.
User metrics in mature markets are also beginning to show signs of pressure. Third-party app data indicates that Netflix's US churn rate rose 16.6% year-over-year in the third quarter, while app downloads in the US and Canada fell by roughly 20%. Although Netflix still boasts a low overall churn rate and a massive global subscriber base, the gap between subscriber count and engagement is becoming an issue that investors cannot ignore when evaluating its advertising business.
Netflix is no longer facing competition solely from traditional streaming platforms such as Disney+ and Amazon Prime Video; YouTube, TikTok, and other creator-driven short-form video content are equally competing for user time. Compared with high-cost film and television productions, this type of content updates faster and offers more abundant supply, posing a challenge to Netflix's traditional content investment model.
Live programming has therefore become a key avenue for management seeking incremental viewership demand. Netflix is expanding its sports events and live entertainment offerings, having acquired the broadcasting rights for the 2030 World Cup in Spain and Andorra. However, live content typically carries high copyright costs and currently makes a limited contribution to total watch time. Management needs to prove that the subscriber growth, ad revenue, and brand influence generated by live programming are sufficient to cover the related investment, rather than merely generating short-term buzz.
Wall Street Average Price Target Falls Amid Content Team Restructuring
Amid slowing user engagement, Netflix is also restructuring its content management architecture. Longtime head of global content Bela Bajaria has departed, and former Disney and Fox executive Peter Rice will take over as Chief Content Officer on October 26; film head Dan Lin subsequently left the company as well. Rice will temporarily oversee the film division while managing Netflix's massive global content budget.
This series of changes indicates that Netflix aims to improve the success rate of its content investments and recreate hit titles capable of consistently driving watch time. The company is reducing resource allocation to underperforming projects while exploring theatrical releases, live sports, podcasts, and alternative show release schedules. However, whether these strategies can improve engagement remains to be validated over multiple quarters.
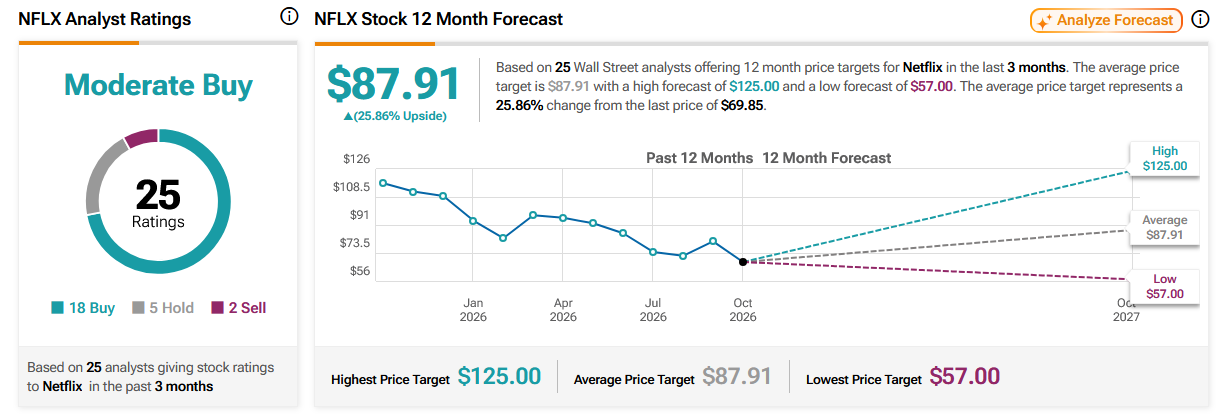
Capital markets have already priced in some of these concerns, with Netflix's stock recently trading near $70, down over 40% from its 52-week high. Against the backdrop of declining watch time, layoffs, and content team restructurings, the options market expects the stock could see a swing of nearly 10% following the earnings release.
Wall Street views on Netflix are also somewhat divided.
According to TipRanks data, analysts' average 12-month price target is approximately $87.91, with a high forecast of $125 and a low of $57. Some institutions believe ad monetization, price hikes, and margin expansion can still drive a stock recovery, while cautious views worry that declining content appeal will gradually erode subscriber growth and pricing power.
Source: TipRanks
Recommended Articles


