


Is Fed Chair Kevin Warsh About To Pop CoreWeave's Bubble?
Key Points
CoreWeave's stock has plunged on concerns about rising yields on its bonds.
New Fed Chair Kevin Warsh has promised to tame inflation, in part by raising interest rates.
CoreWeave will face a key test when it has to refinance $10.6 billion worth of debt by the end of 2027.
- 10 stocks we like better than CoreWeave ›
CoreWeave (NASDAQ:CRWV) has taken center stage in the AI bubble debate.
After venture capital investor Chamath Palihapitiya posted a chart on X last week showing that bond yields on the neocloud operator's debt have risen as high as 15%, CoreWeave shares have spiraled. The stock, the largest of the so-called neocloud companies and posting triple-digit revenue growth, has plunged 24% over the last week and is now trading at its lowest level since shortly after its IPO last March.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Concerns about CoreWeave brought down the broader chip and tech sectors last week, and the stock could continue to serve as an avatar for the broader AI sector as investors debate its future.
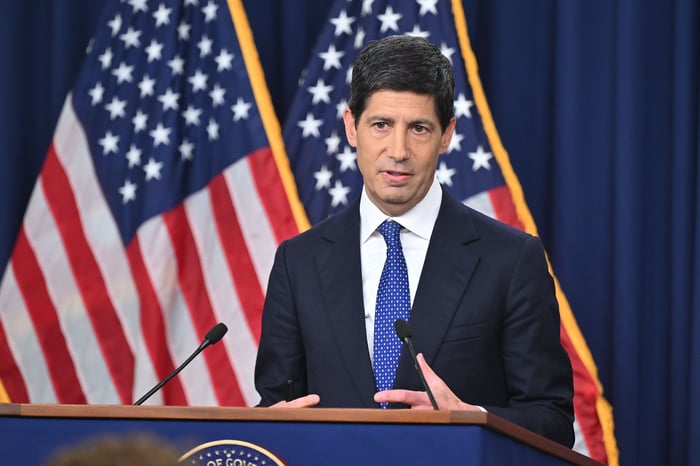
Kevin Warsh. Image source: Official Federal Reserve Photo.
Why CoreWeave has become a microcosm of the AI trade
CoreWeave embodies what both AI bulls and bears see in the AI sector. As a neocloud operator, the company's business model is essentially to borrow money to buy GPUs and then rent out the computing power from those GPUs.
It's a straightforward business model, and it's delivered enormous growth since the company pivoted from crypto to AI around 2022. In its second quarter, CoreWeave reported 112% revenue growth to $2.58 billion, showing the surging demand for AI compute. That has pleased AI bulls and explains why the company's market cap jumped to around $100 billion at one point.
However, CoreWeave is also unprofitable and burning a ton of cash. In the second quarter, it had a generally accepted accounting principles (GAAP) operating loss of $49 million and a net loss of $626 million due to $640 million in interest expense.
CoreWeave reported an adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) profit of $1.51 billion, but that's not the best metric to judge the company on because its business model is highly dependent on capital expenditures and depreciation. Through the first half of the year, the company has had negative free cash flow of $10.5 billion, and it has now accumulated $34 billion and $16 billion in operating lease liabilities.
What's Kevin Warsh got to do with it?
Kevin Warsh took over as Fed Chair in May, and he's made one thing clear: He will bring inflation to heal. Warsh has repeatedly observed that inflation has been above the central bank's 2% target for five years, and he plans to use the tools at his disposal to bring it down, including raising interest rates, which the Fed did at its last meeting.
Treasury yields have soared, partly in response to persistent inflation and expectations that the Fed will continue to hike rates, which has made things more difficult for CoreWeave.
CoreWeave has more interest rate exposure than almost any other major publicly traded company, currently spending roughly a quarter of its revenue on debt service. Most of its debt is floating-rate, meaning its interest expense goes up as rates go up, and new debt will cost it more if rates are higher as well.
What it means for investors
There's no question about CoreWeave's demand, as the company reported a revenue backlog of $104 billion at the end of June and added more than $25 billion to it in the third quarter.
However, the company could be forced to slow its expansion if it has trouble paying its debts. In a worst-case scenario, it could even go bankrupt, though that seems unlikely since Nvidia (NASDAQ:NVDA) is a close partner of the company, and Nvidia has an interest in CoreWeave's success. Nvidia is currently its second-largest investor.
CoreWeave has $10.6 billion coming in debt due by the end of next year, and refinancing that debt will be a major test for the company.
If interest rates continue to go up, CoreWeave's stock is likely to come under more pressure. Keep your eye on treasury yields and Fed commentary in the coming months for further clues into the stock's future. CoreWeave's upcoming earnings report on Nov. 11 could also be pivotal, likely shedding more light on how the company plans to navigate a high-interest rate environment. Whatever happens, investors should expect the volatility to continue.
Should you buy stock in CoreWeave right now?
Before you buy stock in CoreWeave, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and CoreWeave wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $380,363!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,315,732!*
Now, it’s worth noting Stock Advisor’s total average return is 919% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 19, 2026.
Jeremy Bowman has positions in CoreWeave and Nvidia. The Motley Fool has positions in and recommends Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


