


Costco Stock Forecast: Q4 Sales Strength Meets a Membership Growth Test
TradingKey - Costco Wholesale (COST) closed at $922.77 last Friday, an increase of 2.93% from the previous close, on the first trading day after the release of the company’s earnings report for the 16-week quarter ended August 30, 2026. Based on the report, sales trends and renewals remained healthy, and the company continued to see strong progress in its online business. The report and earnings call also addressed membership growth and shopping frequency, which remain key drivers as one-time tariff-refund benefits and the prior membership-fee increase roll through comparisons.
Q4 Sales Were Strong, but the Quarter Had a One-Time EPS Benefit
Costco’s fiscal 2026 fourth quarter covered 16 weeks and ended on August 30, 2026. Net sales for the quarter increased 11.2% to $93.9 billion from $84.4 billion a year earlier. Net income increased to $2.998 billion, or $6.75 per diluted share, from $2.610 billion, or $5.87 per diluted share, a year earlier. Costco said Q4 EPS included a non-recurring $0.15-per-share benefit from IEEPA tariff refunds received in the quarter, less partial reinvestment of those refunds in increased member value.
That makes the after-clean-up EPS $6.60. For me, that makes a difference. At these levels, stock prices usually reflect expectation of growth without aid of extraordinary items.
Comparable Sales Still Show Healthy Underlying Demand
Companywide, reported comparable sales for the quarter increased 9.4%. Adjusted for changes in foreign exchange rates and gas prices, the company reported a 6.7% increase in comparable sales. In the United States, reported comparable sales increased 10.7%, and adjusted comparable sales increased 7.2%. Adjusted digitally enabled comparable sales increased 19.8%.
According to company management, gasoline inflation was the main driver of the comparables sales increase and accounted for approximately three percentage points of the sales increase.
Worldwide shopping frequency increased 3.3%. The average transaction increased 5.9%, or 3.3% excluding gasoline inflation and foreign-exchange changes.
Even after excluding gasoline-price and foreign-exchange effects, comparable sales increased 6.7%, showing that underlying demand remained healthy.
Membership Growth Is the Next Important Test
Costco reported a 7.3% uptick in quarterly membership fee income to $1.85 billion. Total paid membership numbers were at 84.1 million (an increase of 3.8%) with 42.3 million of that number being Executive members (an increase of 9.4%). Renewal rates improved to 92.3% in the U.S. and Canada and 89.8% globally.
Those numbers are impressive, but I find it more interesting to examine the quality of the growth. Executive membership grew at a higher rate than the total paid membership and Executive members are more likely to shop at Costco and renew their membership.
It's worth addressing the 10 year plan. While the total number of members and renewals is encouraging, revenue growth from memberships has been slower compared to the growth of merchandise sold.
The Old Membership-Fee Increase Is No Longer a Tailwind
About one percentage point of the membership revenue growth in the last quarter can be attributed to the membership fee increase implemented in September 2024 in the U.S. and Canada. Management said Q4 was the final quarter with a year-over-year benefit from that increase. Excluding the membership-fee increase and foreign exchange, membership fee income grew 6.8%.
With the year-over-year membership-fee increase tailwind now rolling off, any positive changes to Costco's membership renewals and overall member attendance would be positive for revenue growth.
Digital Growth Is Becoming More Meaningful
Digitally enabled sales exceeded $33 billion in fiscal 2026 and grew more than 20%. Recently, Costco partnered with Uber Eats and DoorDash to provide alternative delivery options, in addition to their partnership with Instacart.
Management has noted that the average age of customers using their delivery services is below the average age of their customer base. Management also said sales through these third-party delivery channels are mostly incremental, with limited impact on core warehouse grocery trips.
While management expects that their focus on digital sales will pay off in the long term, it remains part of Costco's overall membership business.
Tariff Refunds Helped, but Costco Reinvested Part of the Benefit
The refunding of the import duties that Costco previously paid provided a boost and granted them $174 million in tariff refunds plus $10 million in related interest, for $184 million in total tariff-related cash received in the fourth quarter. Management claimed that they decreased prices and boosted member benefits with this refund.
While this boosted EPS by $0.15, management said it had already received a similar amount of refunds in fiscal Q1 2027 and intends to continue reinvesting the majority of the dollars received in increased member value.
Management stated that they expect these boosts to be only temporary. Management will need to continue to evaluate and adjust their member prices to boost sales while attempting to maintain member profits.
Expansion and Cash Flow Support the Long-Term Case
Costco closed fiscal 2026 with 939 warehouses. According to management, 33 new warehouses will open in fiscal 2027, including 5 replacements. Thus, 28 new warehouses are expected to open, assuming the replacements occur as planned.
The expected increase in capital expenditures, to about $7.5 billion from $6.4 billion in fiscal 2026, will be spent on new warehouses and improvements to the supply chain. The cost of these investments will be more than offset by the cash generated by the business.
Costco's financial condition allows them to pursue this growth. Net cash provided by operating activities for fiscal 2026 was approximately $15.8 billion. After $6.4 billion was spent on property and equipment, the simple operating-cash-flow-minus-capex difference was approximately $9.4 billion. Although Costco does not issue guidance, the cash flow illustrates the business' strength.
Valuation Remains the Main Constraint
The stock price of approximately $922.77 as of the publication date valued each share of fiscal 2026 earnings of $20.76 with a multiple of approximately 44.4.
The valuation reflects a positive opinion on key elements of the business, including shopper visits, membership renewals and other positive trends.
A business can become less profitable, and still trade at current valuation levels. Therefore, it is prudent to evaluate key trends for new investors.
The current bull case for Costco is supported by mid-single digit comparable sales with positive membership renewals.
The Next Catalyst Is September Sales
The next update will be the September Sales report on October 7th. We will get our first look at demand for fiscal 2027 with this report. I will look for positive compatible sales issues and increase my bullish outlook with improving traffic. I will look for a slowing of traffic and look for further deterioration of paid memberships and renewals.
Costco Technical Analysis: COST Breaks Descending Channel as $934.34 Comes Into Focus
Costco closed this week at $922.77 and $889.56 has now been support. The breakout above the descending channel is positive and so is the close above the $903.32 and $907.20 moving averages. The $916.35 and $920.05 levels have been support this week, and given the improvements in price and structure, these levels can be viewed as support rather than resistance. The RSI is at 69, which is well above the 54 level and could be moving into overbought territory.
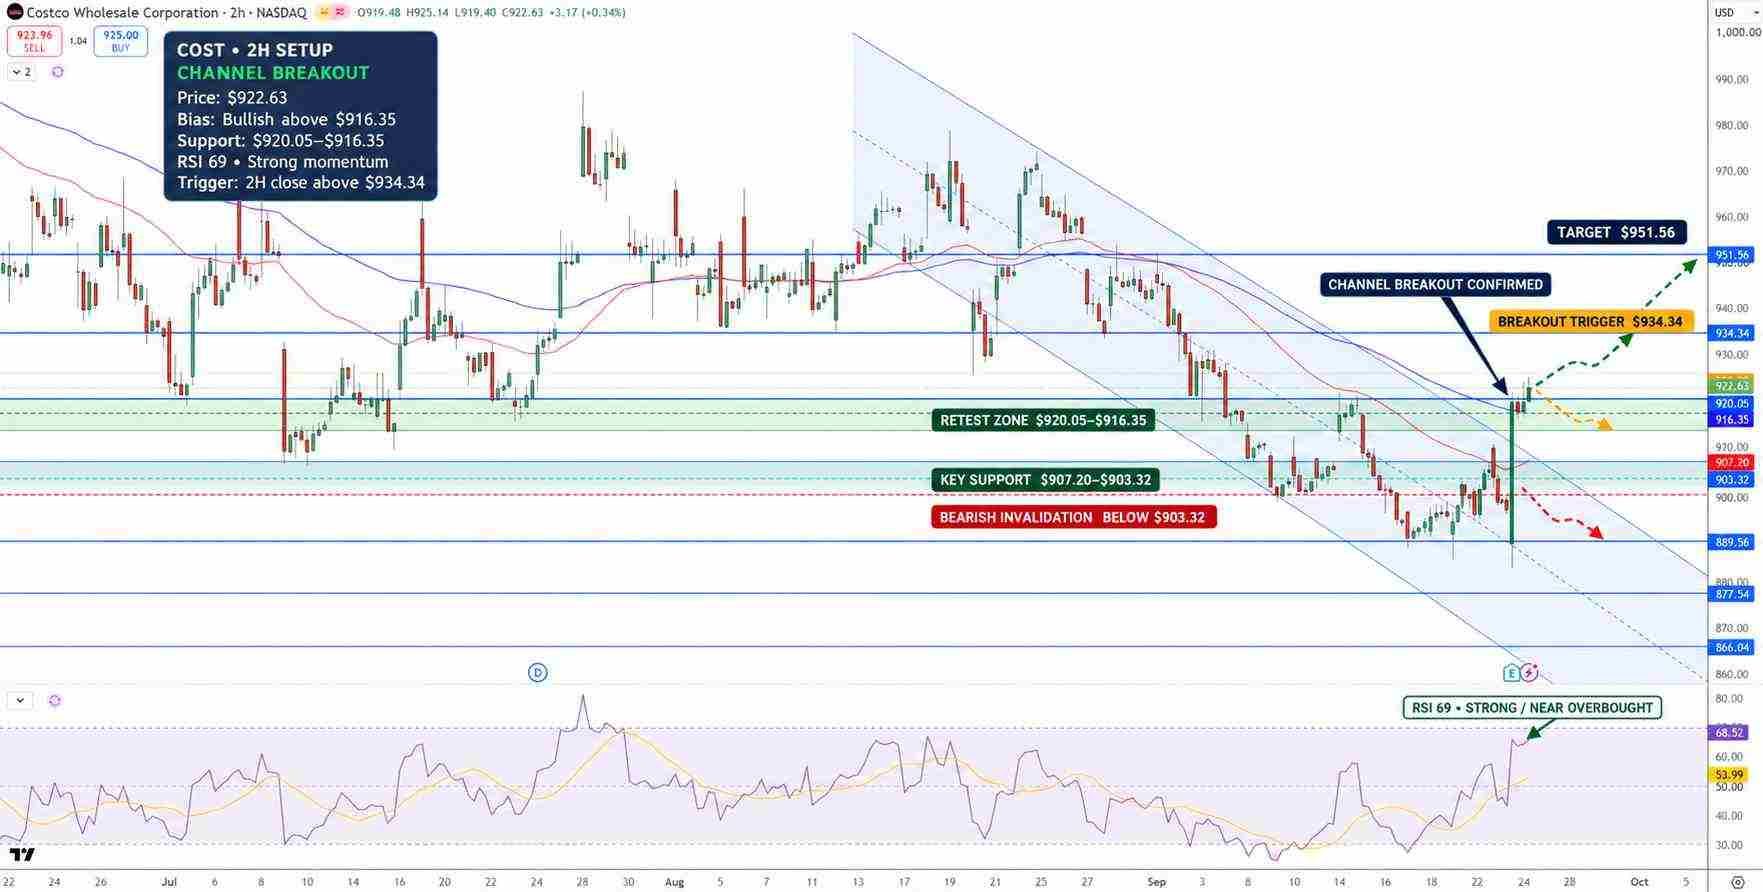
Costco Stock Price Chart - Source: Tradingview
Strong buying has pushed Costco higher. The pace of the advance makes a test of resistance possible before the next leg up. Resistance is in the $925-934 range. A close above $934 in the 2 hourly bar would test $951.56. Support is in the $920-921 range with lower support and first major support in the $907-903 area. Loss of $903 would bring $889 into play. I look for Costco to continue to rise above $916 and my target is $934. RSI is near the overbought range, but not yet above the standard 70 threshold.
Key Levels
• Key Support Level: $916.35
• Key Resistance Level: $934.34
• Major Support Levels: $920.05 to $916.35; $907.20 to $903.32; $889.56
• Major Resistance Levels: $925 to $934.34; $951.56
• Breakout Target: $951.56
• RSI: 69
Why is Costco stock in focus now?
Costco reported its fourth quarter results last week. The company's adjusted comparable sales and renewal rates improved. Executive memberships hit an all time high. Its digital sales also increased. The main headwind for Costco going forward is the loss of the year-over-year benefit from the September 2024 membership-fee increase, along with the stock's elevated valuation, rather than the fee increase itself.
What level confirms a stronger COST breakout?
A bullish outlook on Costco would be justified with a sustained 2-hour close above $934.34. This would also increase the probability of a move to $951.56. A move below $916.35 would reduce the probability of Costco reaching its bullish target.
Bottom Line
Costco's latest earnings release showed that Costco continues to improve. The renewal rates of members improved. More people are also shopping at Costco. The executive memberships also increased.
The main concern with Costco is its valuation. Costco is trading at over 44 times its trailing 12 month earnings. Costco needs to continue to improve in order to justify its valuation.
From a technical standpoint, Costco is in a bull market and is likely to continue increasing. The target price of $951.56 is only valid if Costco trades above $934.34. A decline below $903.32 would materially weaken the bullish breakout structure and increase the risk of a retest of $889.56.
Recommended Articles


