


【US Pre-Market】Nasdaq Futures Fall Nearly 1% as Oil Surges, Tech Stocks Under Pressure, Nvidia News in Focus
TradingKey - On Monday, September 28, Eastern Time, futures on the three major US stock indices fell collectively in pre-market trading. US President Donald Trump rejected a peace proposal from Iran, sending international oil prices surging again and fueling twin concerns over energy inflation and Federal Reserve rate hikes; US Treasury yields broke above 5.2%, putting tech stocks and other high-valuation assets under pressure. Meanwhile, investors were awaiting US PCE inflation and nonfarm payrolls data to be released this week.
As of press time, Dow futures fell 0.54%, S&P 500 futures fell 0.47%, and Nasdaq 100 futures fell 0.82%.
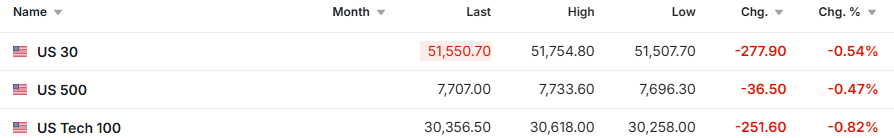
Source: Investing
In commodities, international oil prices rose significantly, with WTI (USOIL) crude rising to near $95 and Brent crude climbing above $100. Trump's rejection of Iran's proposal to end the conflict and reopen the Strait of Hormuz reignited risks of supply disruptions. Gold (XAUUSD) fell over 3%, retreating to around $4,150, as a stronger US dollar and rising Treasury yields weighed on non-yielding assets.
In cryptocurrencies, Bitcoin (BTC) fell about 1.8%, dropping below $83,000. Rising interest rate expectations and cross-asset deleveraging pressure dampened risk appetite in the crypto market.
Market Movers
Big tech and chip stocks were generally under pressure in premarket trading. Meta (META) fell about 3.1%, Intel (INTC) dropped about 3.5%, Arm (ARM) and Marvell Technology (MRVL) both fell over 3%. Rising oil prices and Treasury yields prompted the market to reduce risk exposure to high-valuation growth stocks.
Memory stocks collectively fell in premarket trading. Micron Technology (MU) fell about 2.4%, SanDisk (SNDK) dropped about 3.7%, Western Digital (WDC) fell about 2.8%, Seagate Technology (STX) dropped about 2.4%. Ahead of Micron's earnings report on Wednesday, investors took profits on memory stocks that had previously notched large gains.
Energy stocks bucked the trend and rose. ExxonMobil (XOM) rose about 1.7%, Chevron (CVX) gained about 1.4%, Occidental Petroleum (OXY) climbed nearly 2%. Higher international oil prices improved market expectations for short-term earnings and cash flows of upstream oil and gas companies.
Market News
Trump rejected an Iranian peace proposal. Iran had previously submitted a proposal via Qatari mediators to end the conflict and reopen the Strait of Hormuz. Trump said over the weekend that he had rejected the proposal, but U.S. negotiators are still expected to continue contacts with the Iranian side this week.
China may allow certain companies to import Nvidia chips. According to a report by The Information citing people familiar with the matter, relevant Chinese authorities have signaled that they may allow certain companies, such as ByteDance and Alibaba (BABA), to import Nvidia's (NVDA) RTX Pro 5500 chip designed for the high-end professional computing market. However, the news has not been officially confirmed by Chinese authorities, the relevant companies, or Nvidia, and Reuters also stated it could not independently verify it for now; uncertainty remains over the final scope of approval and whether procurement will materialize.
Profit growth of China's industrial enterprises slowed. Data from China's National Bureau of Statistics showed that profits of industrial enterprises above designated size grew 4.2% year-on-year in August, down from 11.2% in July; in the first eight months of this year, profits increased 15.7% year-on-year, moderating from a 17.6% growth rate in the first seven months.
Bank of Japan meeting minutes show some members supported accelerating rate hikes. The Bank of Japan's July meeting minutes showed that several members paid greater attention to upside risks to inflation, with some suggesting that the pace of policy rate increases may need to accelerate.
Key Data/Events Preview
At 8:15 a.m. ET on September 28, Fed Vice Chair Bowman discusses the latest developments in bank supervision.
At 10:30 a.m. ET on September 28, the U.S. releases the Dallas Fed Manufacturing Index for September.
At 1:25 p.m. ET on September 28, Fed Governor Cook speaks on artificial intelligence and emerging technologies.
At 1:30 p.m. ET on September 28, Richmond Fed President Barkin participates in a fireside chat.
Recommended Articles


