


Amazon Q3 Earnings Preview: AWS Growth Expected to Rise to 41%, Wall Street Top Price Target $400
TradingKey - Amazon (AMZN) will report its third-quarter 2026 financial results after the U.S. market close on October 29 Eastern Time, and host an earnings conference call at 5:00 p.m. on the same day.
The market expects Amazon's third-quarter revenue to reach approximately $202.1 billion to $202.2 billion, up about 12.2% year-over-year, with earnings per share expected to be $1.96, roughly flat compared to the same period last year. The company previously issued revenue guidance of $197 billion to $202 billion and operating income guidance of $22.5 billion to $26.5 billion, meaning market expectations are already near or even slightly above the high end of the revenue guidance range.
Compared with single-quarter revenue, AWS growth, AI infrastructure spending, and free cash flow will likely have a greater impact on the stock price after the earnings release. The options market expects Amazon's post-earnings stock price movement to be around 6.6% to 7.2%. However, actual price moves following the past few earnings reports have significantly exceeded options pricing, indicating that the market remains divided on AI investment returns.
Can AWS Become the Main Driver of an Earnings Beat?
AWS is Amazon's most critical growth variable this quarter. As enterprises continue migrating workloads to the cloud, alongside increasing generative AI model training, inference services, and corporate agent applications, the market is looking to confirm whether cloud growth is still accelerating and whether newly added compute capacity can be timely translated into revenue.
According to analysts' forecasts across business segments, market expectations for AWS third-quarter net sales are approximately $45.4 billion, representing a year-over-year increase of about 37.6%. Deutsche Bank's estimates are even more optimistic, projecting AWS revenue at around $46.5 billion, corresponding to a year-over-year growth of about 41%, higher than the second-quarter growth rate of roughly 37%. The bank also projects that AWS fourth-quarter revenue could rise to $51.1 billion, with the growth rate accelerating further to around 44%.
Beyond cloud service demand itself, new data center capacity, enterprise AI inference demand, the adoption of custom chips, and the development of AI services such as Amazon Bedrock could all impact AWS's actual performance.
Deutsche Bank (DB) believes AWS has the potential to become a key source of upward revisions to Amazon's forecasts. The bank expects third-quarter total revenue to approach the upper end of the company's guidance range, while operating profit could exceed market consensus.
Bank of America also expects AWS growth to reach around 40%, higher than the market's previous consensus of about 38%. Its view is mainly based on the gradual rollout of new capacity, price adjustments, and an increase in enterprise AI workloads.
However, revenue growth is not the sole metric. In the previous quarter, AWS revenue grew by about 37% year-over-year, with an operating margin of approximately 39.4%. As Amazon continues expanding data centers, procuring AI chips, and increasing infrastructure investment, depreciation expenses are also climbing.
Therefore, investors also need to monitor whether AWS can maintain its profit margins while sustaining fast growth. Only if newly added revenue covers infrastructure operating and depreciation costs will the cloud expansion be more likely to sustainably improve Amazon's overall profitability.
Can E-Commerce and Advertising Offset the Impact of Prime Day Timing Shift?
Third-quarter retail data was impacted by the timing shift of Prime Day; last year's event took place in July, whereas this year's was moved up to June, shifting a portion of product sales and advertising revenue from the third quarter to the second quarter.
Amazon stated in its guidance that excluding the timing discrepancy of Prime Day between the two years, third-quarter revenue growth would be nearly 4 percentage points higher. This indicates that the slowdown in July data does not entirely reflect falling consumer demand, but rather significant differences in base effects and revenue recognition timing.
Credit and debit card data tracked by Deutsche Bank also showed that Amazon's e-commerce sales in the US and Europe slowed noticeably at the start of the quarter but gradually recovered afterward. The bank estimates third-quarter net retail sales growth of around 6%, with North American business revenue potentially reaching $113.4 billion and international revenue around $43.2 billion.
The advertising business is expected to sustain double-digit growth, with consensus estimates projecting third-quarter advertising revenue of around $20.9 billion, up nearly 18% year-over-year. Although the Prime Day shift affected merchants' ad spending rhythm, DSP and video advertising continued to expand rapidly.
Rather than further increasing the monetization intensity of on-site product ads, Amazon's incremental ad growth in the future will likely stem more from off-platform traffic, streaming video, and DSP offerings. Leveraging Amazon's proprietary shopping data, these products provide advertisers with end-to-end performance measurement from exposure to purchase, boasting higher profit margins and strong competitive moats.
$220 Billion Capex Tests Free Cash Flow
AI investment remains the single biggest debate surrounding Amazon's valuation. The market projects that the company's capital expenditures in 2026 could reach approximately $220 billion, primarily allocated to AWS data centers, AI chips, network infrastructure, and satellite projects. As front-loaded investments outpace revenue realization, free cash flow has come under significant pressure.
UBS estimates that Amazon's capital expenditures could exceed $300 billion by 2027, while Deutsche Bank offers an even more aggressive forecast of around $330 billion. It is worth noting that these figures are analyst estimates, not official guidance from Amazon.
Investors need to distinguish the specific drivers behind the increase in capital expenditures. If spending growth stems from adding new data center capacity that can be brought online quickly, it could help accelerate AWS revenue growth. Conversely, if the increase is primarily driven by rising costs for memory, GPUs, power, and construction without a corresponding gain in available compute power, return on capital may fall short of expectations.
Ahead of the earnings release, several institutions maintained a positive stance on Amazon. UBS (UBS) raised its price target from $318 to $348 while maintaining a Buy rating; Evercore kept its $355 price target, believing AWS and advertising can support earnings growth; BMO Capital reaffirmed its positive rating with a price target of $380; and Deutsche Bank maintained its $325 price target, noting that AWS growth could drive upward revisions to future performance expectations.
According to data from TipRanks, the average 12-month price target for Amazon given by 44 Wall Street analysts over the past three months is $331.54, with a high of $400 and a low of $230.
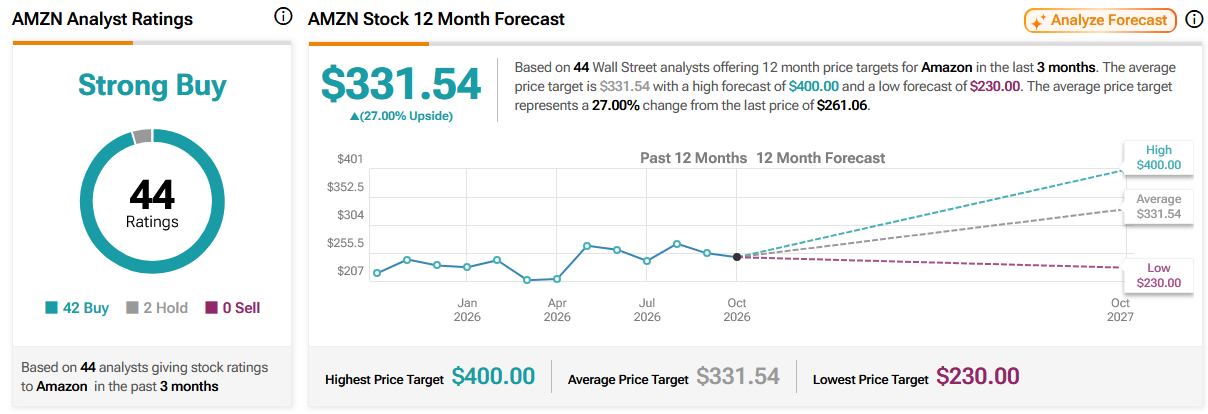
Source: TradingView
Recommended Articles


