


Taiwan Semiconductor Is Set to Cash in on AI. Here's What a $5,000 Investment Could Be Worth by 2030.
Key Points
Taiwan Semiconductor is forecasting rapid growth in demand for computer chips, and is investing to expand its production capacity.
Taiwan Semiconductor's stock isn't all that expensive right now.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Few stocks are as much of a guaranteed winner from the AI build-out as Taiwan Semiconductor (NYSE: TSM) is. Taiwan Semiconductor is the world's largest chip foundry by far, and it's the only one with the technology and expertise to produce the cutting-edge chips needed to power devices like GPUs from Nvidia or smartphones from Apple.
Taiwan Semiconductor is set to cash in, but what could a $5,000 investment now grow to by 2030? I think it could reach $15,000.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: The Motley Fool.
Taiwan Semiconductor has a great outlook
Few companies have the level of visibility into conditions in the tech sector that Taiwan Semiconductor enjoys. Because it makes chips for nearly every company designing AI computing units, it is privy to information regarding expected future demand. That allows Taiwan Semiconductor time to build out the production capacity necessary to meet demand. The company has heavily invested in new chip foundry facilities in Arizona, and has now committed $265 billion to increasing U.S. chip production capacity. That's not an insignificant investment, and it also helps diversify its chip production away from Taiwan, which is always at risk of military action from mainland China.
Previously, the company gave guidance that its AI chip sales would grow at a compound annual rate in the high 50% range from 2024 through 2029. An analyst asked for an updated figure during its most recent conference call, and while CEO C.C. Wei didn't offer a specific update, he noted that demand is "very extremely robust," and that the actual growth rate "doesn't matter, it probably will be higher."
That's a very bullish statement, and with other chip companies already starting to guide for high levels of demand for 2030 to 2031, it could last for much longer.
During Q3, nearly 70% of its business came from high-performance computing, which encompasses its AI products. About 20% of its business comes from smartphones, with the remaining 10% coming from various other industries. Taiwan Semiconductor's business is most heavily influenced by AI right now, and if that segment's growth rate stays rapid -- as management suggests it will -- then the company is in for quite the growth trajectory.
Here's how Taiwan Semiconductor will turn $5,000 into $15,000
Management's older long-term forecast for compound annualized growth of 50% now includes several years when its sales of higher-powered computing chips were growing much faster. From here, I think it's more reasonable to assume that Taiwan Semiconductor as a company can grow at a 35% rate until 2030. For reference, analysts expect 38% growth in 2027.
It has also achieved a 51% profit margin over the past few months. I could see that margin expanding as demand stays tight, but for the sake of these estimates, I'll keep it at 50% to bake in a bit of conservatism. If Taiwan Semiconductor can grow its revenue at a 35% pace from now until 2030, that would increase its revenue to $518 billion. At a 50% profit margin, that would be about $259 billion in profits.
Right now, the market values the stock at about 28 times earnings. If we assume that by 2030, its valuation will have slipped to just 25 times earnings (fairly cheap compared to its historical levels), that would give it a market cap of $6.5 trillion.
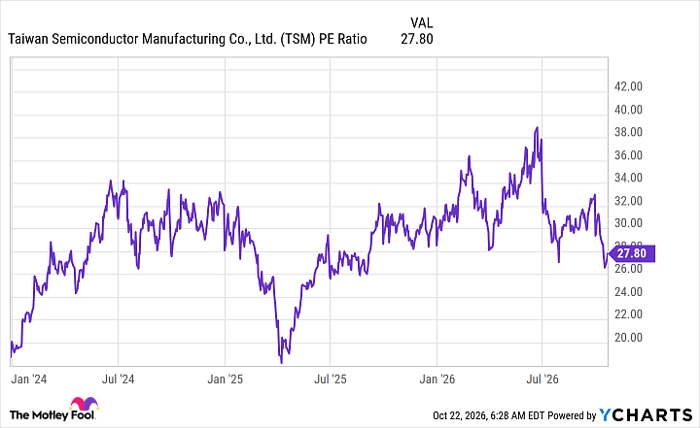
TSM PE Ratio data by YCharts.
Currently, Taiwan Semiconductor has a $2.2 trillion market cap. So, this estimate projects that TSMC's stock could nearly triple in the next four years, turning a $5,000 investment into about $15,000. That's a great return in just a few years, and if the AI build-out continues at the expected pace, Taiwan Semiconductor will be one of the best stocks to own during that time frame.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 25, 2026.
Keithen Drury has positions in Nvidia and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Apple, Nvidia, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


