


Can GE Vernova's Gas Turbines Make Up for a Collapsing Wind Business?
Key Points
Revenue and orders for GE Vernova’s wind turbine business have been declining since 2024.
Its natural gas power turbines business, conversely, is experiencing growth.
Interested investors need to understand that there’s more at work here than just a mere redirection of revenue.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Do you fear bad news can do more harm to a company's stock than good news can help it? It's not unheard-of. Investors are inherently defensive, wired to prevent losses more than they are to reap gains.
It's something investors are grappling with right now regarding GE Vernova (NYSE: GEV). While demand for its natural gas power turbines appears to be soaring, interest in its wind turbines is tumbling. Can the former's growth offset the latter's decline? Here are some visual aids to help put things in perspective.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source:
Not a headwind, but a shift
Yes, GE Vernova is one of the offshoots of the old General Electric, spun off from the iconic company in 2024. GE Vernova's focus is power production. In addition to wind and natural gas turbines, this enterprise manufactures hydropower equipment, power grid solutions, and even nuclear power reactors in addition to systems and software that optimize its technology.
Demand for these different categories of equipment is forever changing too, in step with constant rethinking of how to best shore up the planet's electricity shortage. And as it turns out, institutions can take or leave wind-driven electricity. GE Vernova's wind power equipment revenue fell 11% year over year to $2 billion during the second quarter of the year, paired with a 40% decline in orders for wind turbines, extending a slump that really materialized beginning in 2024.
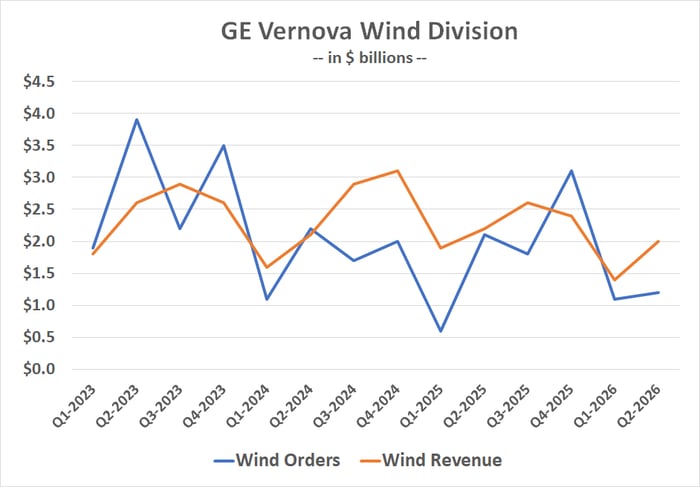
Data source: GE Vernova. Chart by author.
This slump, however, isn't so much an indictment of renewable energy as much as it's an indication of shifting preference for a more proven and persistent form of clean energy. That's the aforementioned natural gas power turbines, which account for the bulk of GE Vernova's power division's sales. This business reported year-over-year revenue growth of 14% to $5.5 billion in Q2, while orders soared 135% to $16.7 billion. Both growth figures extend well-established trends.
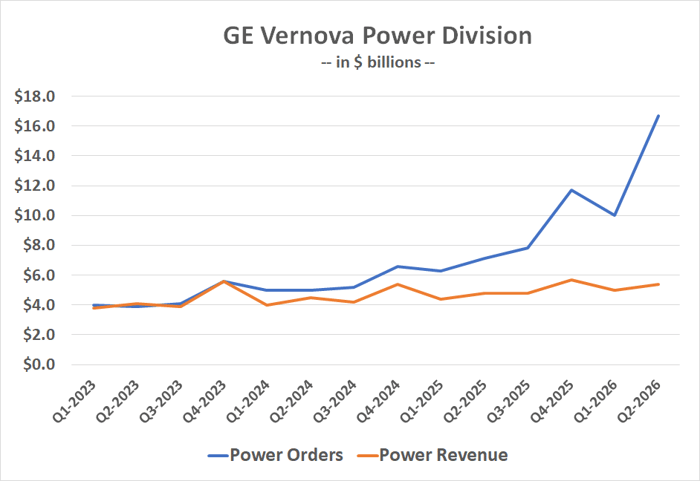
Data source: GE Vernova. Chart by author.
Perhaps even more helpful is a combined, comparative visualization of these order numbers along with those of GE Vernova's electrification arm, which handles equipment like transformers and switchgear. This image speaks volumes, with total combined orders reaching a record $24.2 billion in Q2 alone.
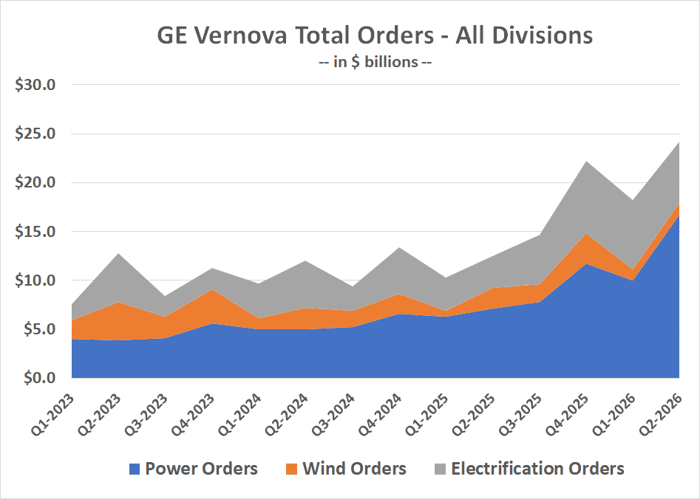
Data source: GE Vernova. Chart by author.
The company's biggest roadblock right now? Mostly just a lack of production capacity, though it's addressing that as well.
The graphics speak for themselves
In answer to the overarching question, then, yes, the growth of GE Vernova's gas turbine business can more than offset the slow collapse of its wind turbine business. It's clearly doing so, in fact.
Its long-term future looks bright too, and not necessarily for the reason you might think. Although it is true that artificial intelligence (AI) data centers are purchasing GE Vernova's natural gas turbines as a source of secondary or even primary power, an implosion of the AI business (and its capital spending) wouldn't be a fatal blow to this company's leading growth engine. As CEO Scott Strazik noted during July's Q2 conference call, only 20% of GE Vernova's power division's current backlog is data center customers. The rest are conventional customers, such as utility companies, that need this equipment regardless of the economic backdrop.
Should you buy stock in GE Vernova right now?
Before you buy stock in GE Vernova, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and GE Vernova wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 25, 2026.
James Brumley has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends GE Vernova. The Motley Fool has a disclosure policy.
Recommended Articles


