


General Motors' Q3 Sales Slipped. Its Profits Soared. Here Are 3 Takeaways Investors Must Note.
Key Points
Digital services and subscriptions such as OnStar and Super Cruise are growing and becoming a profit engine.
GM authorized a record $20 billion for share repurchases.
Lucrative truck sales are driving the company's bottom line, but overall sales volume declined.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
General Motors (NYSE: GM) released its third-quarter earnings and it was really a dueling narrative story. On one hand, a lot of data showed GM excelled with sales of highly profitable full-size trucks, despite an overall sales decline, with net income soaring compared to the prior year.
On the other hand, tariffs, commodity costs, onshoring production from overseas, and an increasingly difficult environment are headwinds that are going to provide speed bumps for automakers across the industry. All that aside, GM's third quarter had intriguing data that emphasized three big takeaways for investors.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Digital services becoming a second engine
One of the biggest developments for automakers such as General Motors and rival Ford Motor Company (NYSE: F) is growth in digital services which generate software-like high-margin business. Recognized revenue from OnStar increased 15%, compared to the prior year, to $800 million. With deferred revenue collected in advance for both OnStar and Super Cruise, revenue generated from GM's subscription services was on pace to reach $10.5 billion this year.
Further, GM is on track to add 1 million subscribers by the end of 2026 and with full-size truck redesigns on the way this fall the automaker expects Super Cruise penetration in its trucks to grow between four to five times in 2027. "Trucks will be a big driver of incremental Super Cruise adoption and digital revenue in 2027 as we make the technology standard on high-end Silverado and Sierra trims, and optional on most others," GM CEO Mary Barra said in letter to shareholders.
Record repurchase authorization
Another massive development for GM was authorizing a record $20 billion for share repurchases. This has been a big driving force for GM's stock price as it's significantly reduced its outstanding share count with more than $42 billion toward share repurchases since 2015. At current prices, that $20 billion authorization has the potential to repurchase roughly a quarter of GM's shares outstanding. While investors often squabble about the advantages and disadvantages of returning value to shareholders via stock repurchases, rather than a lucrative dividend, investors can also see that GM's rise in share price has largely coincided with its reduction in outstanding shares.
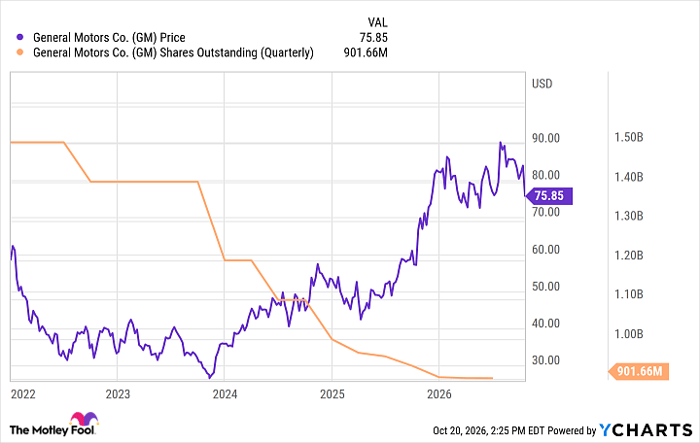
GM data by YCharts
In addition to simply signaling management's confidence in its business going forward, share buybacks increase earnings per share, as profits remain at similar levels with a reduced number of shares to split between. Investors can also enjoy some tax efficiency because dividends are typically taxed as income the year they are received, while the value gained from repurchases can be capital gains that are deferred until the stock is sold.
GM's trade-off
General Motors hasn't changed its strategy of pushing sales of lucrative full-size trucks and high-margin subscription services, but the trade-off is that the gains in margin from higher-priced vehicles are essentially in exchange for lower volume of sales. GM's volume and deliveries are down, and a big driving force of that is its focus on more profitable and expensive vehicle sales while the rising average new-car price is forcing some consumers out of the market.
Image source: General Motors.
Further, GM has missed some opportunities with surging sales of hybrids while its U.S. sales declined 6.3% during the third quarter. For now, the trade-off is paying off on the bottom line as third-quarter revenue increased only 2.9% while net income jumped 151% to $3.34 billion. Investors will want to pay attention to how GM attacks the growing affordability problem in the U.S. and how it seizes the opportunity with rising hybrid sales.
Why the sell-off?
Despite the impressive bottom-line growth during the third quarter, investors sent the stock down about 8% by mid-afternoon on Oct. 20th. GM also noted that "There are clear external headwinds, and in some cases they are intensifying," said CEO Mary Barra on a call with analysts. For instance, copper prices are at record levels and spot prices for steel have jumped as much as 50% from 2025, according to the Detroit automaker, and commodity inflation alone will hit GM by about $400 million in incremental costs in 2026. When investors add in rising logistics costs and memory chip prices, total commodity inflation is projected to cost GM about $2 billion this year.
For investors, it was a strong third quarter with net income blossoming, digital services expanding and turning into a second engine of profits, and a massive $20 billion authorized for share repurchases. While GM may be leaving some sales volume on the table in preference for more lucrative sales of its bread-and-butter trucks, GM seems to be firing on all cylinders even if uncertainty and rising costs continue to cloud over the global auto industry.
Should you buy stock in General Motors right now?
Before you buy stock in General Motors, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and General Motors wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $370,440!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,330,110!*
Now, it’s worth noting Stock Advisor’s total average return is 924% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 21, 2026.
Daniel Miller has positions in Ford Motor Company and General Motors. The Motley Fool recommends General Motors. The Motley Fool has a disclosure policy.
Recommended Articles


