


Not Nvidia. Not Micron. These 2 Under-the-Radar AI Stocks Could Be Worth Holding Through 2030
Key Points
Shares of Micron and Nvidia may remain under pressure owing to negative market perception.
Applied Digital and Jabil have been growing at an impressive pace and can sustain healthy growth due to robust demand for AI data center infrastructure.
- 10 stocks we like better than Applied Digital ›
Nvidia (NASDAQ: NVDA) and Micron Technology (NASDAQ: MU) are among the leading players in the artificial intelligence (AI) infrastructure market, providing critical chips that help AI workloads run smoothly in data centers.
The impressive growth in their revenue and earnings in recent years has made investors significantly richer. For example, Nvidia stock has jumped by 259% over the past three years, while Micron has clocked even more impressive gains of almost 977% during this period. However, there is a chance that these two bellwethers may be outperformed by lesser-known AI infrastructure stocks, such as Jabil (NYSE: JBL) and Applied Digital (NASDAQ: APLD) through the end of the decade.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Let's look at the reasons why.
Image source: Getty Images.
Why Nvidia and Micron could remain under pressure despite solid growth
There is no doubt that Nvidia and Micron still have impressive growth potential. Both companies recently noted that they expect to sustain solid growth levels over the coming year. Nvidia, for instance, expects a 70% increase in revenue next year, while Micron expects its financial performance in fiscal 2027 to be better than last year's record results.
However, these AI stocks could be victims of market perception. Nvidia, for example, has been in the news for the wrong reason lately. Co-founder and former CEO Jensen Huang's ouster could erode investor trust in the stock. The company will now be under greater scrutiny from investors and analysts alike, and any slip in its financial performance is likely to be punished heavily.
Meanwhile, there are concerns that Micron's red-hot growth won't be sustainable forever, given the impressive margins the company has already achieved. Also, growing competition from China, which explains why Micron's share of the dynamic random-access memory (DRAM) market slipped by five percentage points year over year in Q3, is another reason to be worried about the stock's prospects.
That's the reason why I think now is a good time to take a closer look at some underrated AI infrastructure players that could deliver robust gains through 2030.
Jabil is growing at a nice clip thanks to strong AI server demand
Jabil is not a household name in the AI infrastructure space, as only 13 analysts cover the stock, compared to 55 covering Micron and 73 covering Nvidia. However, all 13 analysts rate Jabil as a buy, with a median 12-month price target of $430. That implies 66% gains over the coming year.
It is easy to see why that's the case. Jabil's revenue increased by 21% in fiscal 2026 (which ended on Aug. 31) to $36 billion, and it expects a stronger 24% increase in revenue in fiscal 2027 to $44.5 billion. The company predicts a 34% increase in its non-GAAP earnings per share in fiscal 2027 to $17.55. AI will be the primary driver of Jabil's solid growth this year, which isn't surprising as the company sells server racks, power management systems, and cooling solutions.
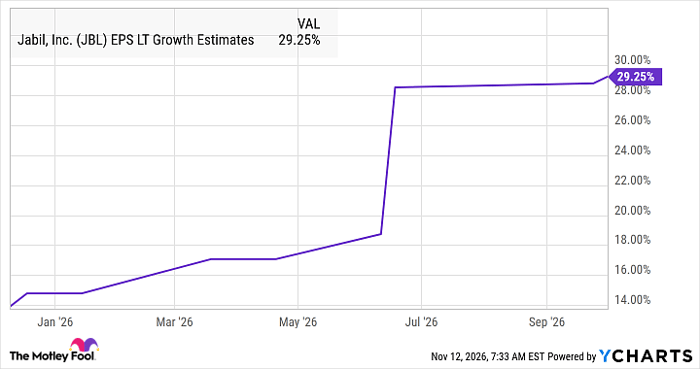
The company is forecasting a 54% increase in AI-related revenue in fiscal 2027 to $22.1 billion. Notably, AI server demand is predicted to increase at an annual rate of 34% through 2030, according to a third-party estimate. So, Jabil's end market should grow at a healthy pace until the end of the decade, and that explains why analysts have become quite bullish about its long-term earnings growth prospects.
Data by YCharts
With Jabil trading at just 15 times forward earnings, a discount to the tech-laden Nasdaq-100 index's forward earnings multiple of 20, investors are getting a good deal on this under-the-radar AI infrastructure stock that could soar impressively through the end of the decade.
Applied Digital is another potential multibagger to buy and hold for the long run
Applied Digital is right in the middle of the AI infrastructure boom. The company designs, builds, and operates high-performance computing (HPC) and dedicated AI data centers, which is why it is enjoying exponential growth.
The company's revenue in the first quarter of fiscal 2027 (which ended on Aug. 31) jumped by 322% year over year to $342 million. Applied Digital has already delivered 250 megawatts (MW) of data center capacity to customers, and it estimates it will deliver another 600 MW over the next 12 months. As a result, Applied Digital should start recognizing more lease revenue over the coming year.
Even better, the company predicts that it can build 3.5-4 gigawatts (GW) of data center capacity by the end of 2030. So, I won't be surprised to see Applied Digital's revenue pipeline getting bigger by the end of the decade. The company currently has $36 billion in contracted lease revenue pipeline for 15 years at its five data center campuses for 1.4 GW of capacity.
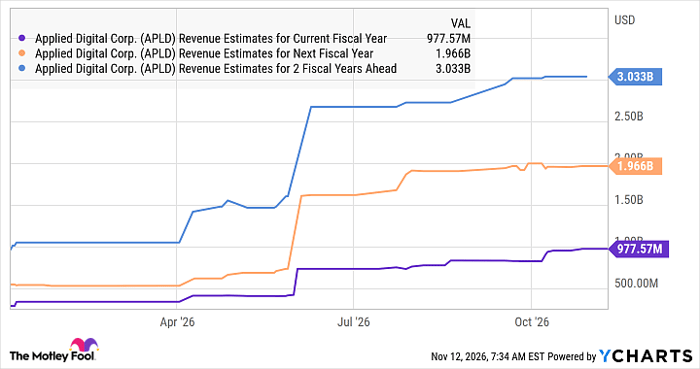
The potential expansion suggests that the revenue pipeline could increase substantially by 2030. Not surprisingly, analysts expect terrific growth in Applied Digital's revenue over the next three fiscal years, a trend that could continue through 2030, given the points discussed above.
Data by YCharts
What's more, 17 of the 19 analysts covering Applied Digital rate it as a buy. The stock has a 12-month median price target of $64, nearly 4x its current price. Applied Digital trades at just 6 times sales, a small premium to the Nasdaq Composite index's sales multiple of 5. That's quite cheap considering the phenomenal growth it has been clocking.
So, investors can buy this potential multibagger at a really attractive valuation right now, and doing so looks like the smart move, given the incredible room for growth the company has through 2030.
Should you buy stock in Applied Digital right now?
Before you buy stock in Applied Digital, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Applied Digital wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 16, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Micron Technology and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


