


Billionaire Bill Ackman Has Been All-In on Uber. Is Now the Time to Buy the Stock?
Key Points
Uber continues to deliver strong revenue growth and operating leverage.
Investors can still buy the stock at a similar price to what Ackman paid.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Billionaire Bill Ackman is one of the world's top investors. He went all in on Uber Technologies (NYSE: UBER) at the start of 2025, and added to his position in the second quarter of this year to make it his largest position. Despite his endorsement, Uber stock is down around 25% over the past year.
When Ackman disclosed his stake in Uber in February 2025, the company had been under pressure due to fears of what role it would play in a world with autonomous driving. He thought the ride-share company's risk was ultimately limited and that autonomous driving companies were more likely to partner with Uber than disrupt it. Meanwhile, he felt its food delivery business would feel no effect, given that a person would presumably have to pick up orders from restaurants and other places and bring them to people's doors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ackman added that Uber was "one of the best-managed and highest quality businesses in the world." Today, investors can buy the stock at a just slightly higher price than Ackman was likely buying shares at nearly two years ago.

Image source: Getty Images.
Bullish thesis remains on track
A large part of Ackman's thesis with Uber is that the company would begin to see strong operating leverage and that profits would nicely outpace revenue growth in the coming years. That has played out, and Uber demonstrated that once again when it reported its third-quarter results on Nov. 4.
For the quarter, Uber's revenue increased 10% year over year, to $14.77 billion. That came in ahead of the $14.69 billion consensus, as compiled by LSEG. Notably, its mobility segment revenue growth is being affected by new laws in the U.K. and some other European countries that require the company to classify drivers as workers rather than independent contractors. This just affects revenue, so gross bookings (the total dollar amount billed to customers) is perhaps the better measure of how the company is performing.
Both the company's main segments -- mobility (rideshare) and delivery (home to UberEats) -- reported robust gross bookings in Q2. Mobility gross bookings jumped 18% to $29.5 billion, while revenue fell 2% to $7.5 billion due to the business model change. Segment adjusted EBITDA, meanwhile, jumped 27% to $2.4 billion. The company saw stable growth in the U.S., while some international markets, like Brazil and India, felt driver supply constraints due to high fuel prices.
Delivery gross bookings rose 22% to $28.5 billion, while revenue climbed 23% to $5.5 billion and segment EBITDA soared 30% to nearly $1.06 billion. The company said its grocery and retail business is doing well, with this segment sitting at a $15 billion run rate growing 40%. Its partnership with Costco Wholesale, meanwhile, is running ahead of expectations.
Uber's overall gross bookings rose 20% year over year in the quarter, while trips in the quarter jumped 16% to 4.1 billion. Showing strong operating leverage in the business, adjusted EBITDA climbed 31% to $3 billion, while adjusted earnings per share (EPS) jumped 35% to $0.88.
Looking ahead, the company forecasts gross bookings to rise between 18% and 22% on a constant currency basis to a range of $63.25 billion to $65.25 billion. It projected that adjusted EPS would increase to a range of $0.95 to $0.88, representing growth of 34% to 39%.
Uber expects to have 700 autonomous vehicles on its platform by year-end, and more than 2,000 by the end of 2027, with half in the U.S.
Is the stock a buy?
Uber continues to deliver strong growth and operating leverage, while the stock trades at an attractive valuation with a forward price-to-earnings (P/E) of 16 based on 2027 analyst estimates. The biggest question for the stock is what the long-term effect of autonomous driving on its business will be. Unfortunately, that likely won't be answered for a long time.
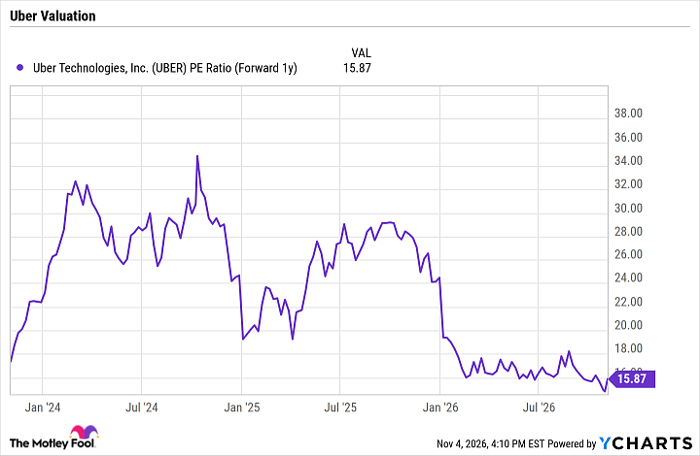
UBER P/E Ratio (Forward 1y) data by YCharts.
Uber is investing in the autonomous vehicle space with multiple partners, and it seems unlikely that these companies would want to run a competing rideshare business and deal with the day-to-day operations. Meanwhile, Uber has strong brand equity with an app already on hundreds of millions of people's phones around the world, along with decades of routing and pricing data. As such, it should still be an important partner even in an autonomous vehicle world, making the stock a buy at current levels.
Should you buy stock in Uber Technologies right now?
Before you buy stock in Uber Technologies, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Uber Technologies wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $341,966!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,146,819!*
Now, it’s worth noting Stock Advisor’s total average return is 852% — a market-crushing outperformance compared to 203% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 8, 2026.
Geoffrey Seiler has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Costco Wholesale. The Motley Fool recommends Uber Technologies. The Motley Fool has a disclosure policy.
Recommended Articles


