


Cloudflare Stock Forecast: AI Growth Puts $272.23 Reclaim to the Test
TradingKey - Cloudflare (NYSE: NET) closed November 5 at $244.51, down 8.28%, before reporting earnings. Shares subsequently traded at $280.51 at 7:59 p.m. Eastern, up 14.72% from the regular close. That extended-session move reclaimed $272.23, the chart barrier buyers must now defend. Stock Analysis records the two session prices.
Revenue acceleration and management’s forecast of fourth-quarter GAAP profitability explain the renewed interest. The investment test is whether expanding AI workloads can improve cash returns as Cloudflare spends more on its network.
Customer Expansion Gives Growth More Depth
Quarterly revenue rose 39% to $782.5 million. Adjusted diluted EPS increased to $0.38 from $0.27.
Dollar-based net retention reached 122%, up from 120% in the previous quarter and 119% a year earlier. This measure tracks expansion within existing customer relationships after accounting for reductions and departures. Cloudflare also added 308 large customers, bringing the group to roughly 5,000 customers generating more than $100,000 in annualized revenue. Both acquisition and expansion are contributing.
Workers Turns AI Activity Into Spending Commitments
Management described a one-year, $11 million agreement with an unnamed AI company using its Workers developer platform. Workers lets developers run applications on Cloudflare’s infrastructure.
A single agreement cannot establish the economics of the whole AI business. I would focus on whether customers continue expanding after their first spending commitments. Recurring usage across multiple applications would give Cloudflare a stronger revenue base than a short burst of experimentation.
Adjusted Margin Gains Need a GAAP Cross-Check
Adjusted operating margin improved to 17.5% from 15.3%, even as adjusted gross margin declined to 72.4% from 75.3%. The combination suggests operating costs consumed a smaller share of revenue, offsetting weaker profitability before those expenses.
GAAP results tell a less favorable story. The operating loss widened to $67.9 million from $37.5 million, leaving an operating margin of negative 8.7%. Net loss reached $34.1 million, versus $1.3 million a year earlier. Shareholders therefore need to assess adjusted progress alongside the costs excluded from those measures. The promised profitability milestone still lies ahead.
Network Spending Slows Cash Conversion
Operating cash flow increased to $215.4 million, but free cash flow reached $82.1 million versus $75 million a year earlier. The reported free-cash-flow margin fell to 10% from 13%. Sales are expanding much faster than the cash remaining after the investments included in Cloudflare’s calculation.
Network capital expenditure represented 15% of quarterly revenue. Management continues to expect 14% to 15% for the full year. Investing ahead of demand can improve capacity and service quality, but the financial payoff requires that capacity to attract enough paid usage. Improving cash generation per dollar of revenue would strengthen confidence in the expansion.
Cash, equivalents and available-for-sale securities totaled approximately $5.13 billion. Cloudflare also issued $2.5 billion of convertible notes and repaid $1.3 billion during the quarter. Financing contributed to liquidity, while convertible debt introduces future repayment obligations and potential dilution.
New Revenue Leadership Must Sustain Enterprise Execution
Christian Smith became president of revenue effective November 2, succeeding Mark Anderson. Smith previously led Splunk’s worldwide commercial business at Cisco. Anderson is retiring from his full-time role and will support the transition as an adviser through December, according to the appointment announcement.
The practical question is whether sales productivity and renewals hold up as the organization grows. Sustained expansion after the leadership handover would provide evidence that execution extends beyond individual executives.
Fourth-Quarter Profitability Is the Next Financial Test
Cloudflare forecasts fourth-quarter revenue of $845 million to $846 million and adjusted EPS of $0.43. Management also expects GAAP profitability in that quarter, earlier than its previous timetable of achieving the milestone by 2028 at the latest.
The November 18 RBC technology conference offers an earlier opportunity for commentary, followed by a Barclays conference on December 9. The next quarterly results will provide the decisive evidence on profitability. Durable customer expansion with stabilizing margins would strengthen the outlook, while further cash-conversion deterioration would challenge it.
Cloudflare Technical Analysis: $272.23 Separates Recovery From Rejection
Cloudflare’s daily chart broke beneath its rising trendline and support zone before closing at $244.51. Buyers recovered from the $233.62 session low and finished above $239.86 support. That setup favored selling a failed retest of $272.23, but the verified $280.51 after-hours print has moved price beyond that barrier.
I would require a regular-session daily close above $272.23 to invalidate the immediate bearish rejection setup. Holding that level would favor recovery toward $299.80. A daily close above $299.80 would confirm further strength, although the supplied chart offers no higher target.
RSI at 29.42 is oversold on the supplied daily chart. MACD remains below its signal line with a widening negative histogram, indicating strengthening downside momentum before the earnings response. Those readings need reassessment after regular trading resumes. If buyers surrender $272.23, the recovery loses credibility. A daily close below $239.86 would confirm renewed weakness and expose $214.53. The old bearish call is therefore conditional on a failed reclaim.
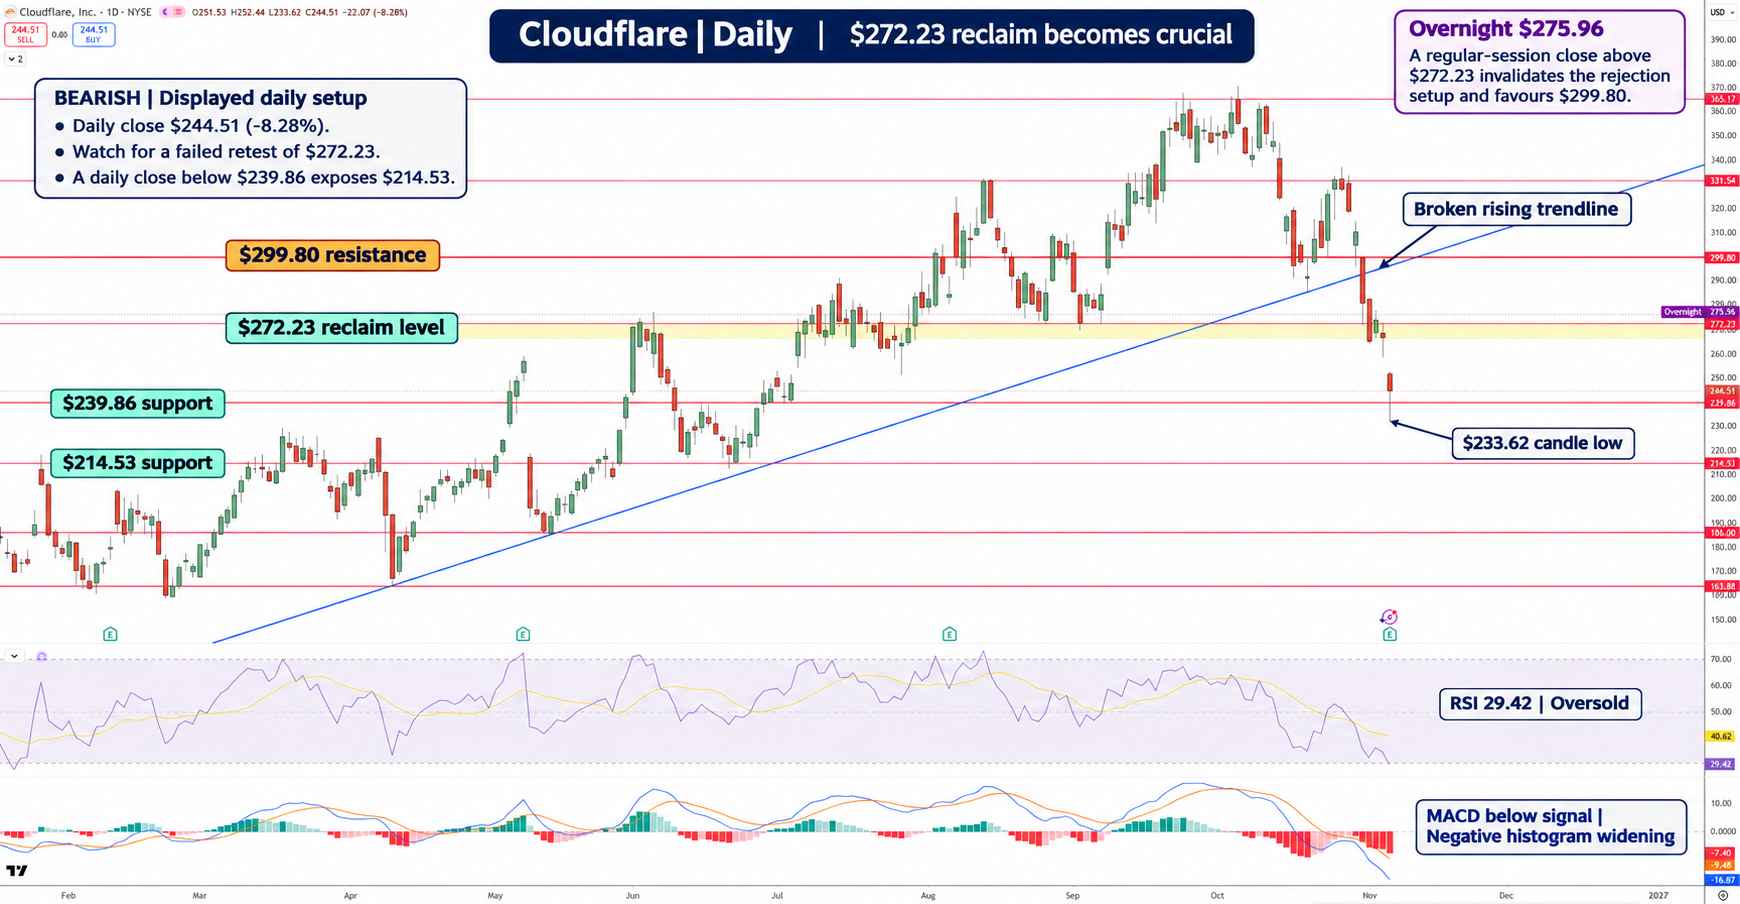
NET Price Chart - Source: Tradingview
Key Levels
- Latest completed close: $244.51 on November 5
- After-hours reference: $280.51 at 7:59 p.m. Eastern on November 5
- Immediate reclaim and support test: $272.23
- Resistance and upside target: $299.80
- Lower support: $239.86, then $214.53
- Supplied daily RSI: 29.42, oversold before the earnings reaction
FAQ
Why did Cloudflare rise after earnings?
Revenue accelerated and management forecast fourth-quarter GAAP profitability, supporting a stronger growth outlook.
What invalidates the immediate bearish NET setup?
A regular-session daily close above $272.23 would favor $299.80. Losing $239.86 would expose $214.53.
Bottom Line
Cloudflare’s customer expansion supports a constructive fundamental view, but cash conversion and GAAP losses require scrutiny. A daily close above $272.23 would shift the chart toward recovery. Failure there keeps the bearish rejection scenario relevant.
Recommended Articles


