


Docusign vs. Okta: Which Tech Stock Is a Better Buy for 2027?
Key Points
Docusign maintains a dominant position in the electronic signature market, with a massive customer base exceeding 1.8 million users.
Okta is a leader in identity and access management, benefiting from a robust integration network and double-digit revenue growth.
Which software specialist is the better investment for your portfolio heading into 2027?
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
As digital workflows become standard, many investors are choosing between the leader in electronic signatures and the titan of identity security. Here is how Docusign (NASDAQ:DOCU) and Okta (NASDAQ:OKTA) compare today.
Docusign focuses on automating agreement workflows through its Intelligent Agreement Management platform. Okta operates as a leader in identity security, ensuring only authorized users access corporate systems. While both provide critical cloud services, their growth profiles and market valuations offer distinct paths for investors looking ahead to 2027.
The case for Docusign
Docusign provides cloud-based software that simplifies the way organizations prepare, sign, and manage agreements. According to its latest annual report, filed for the period ending in early 2026, its Intelligent Agreement Management platform serves over 1.8 million customers globally. The company relies on deep integrations with partners like Salesforce (NYSE:CRM), Microsoft (NASDAQ:MSFT), and SAP (NYSE:SAP) to drive its product adoption.
In fiscal 2026, revenue reached nearly $3.2 billion, representing growth of approximately 8.2% over the prior year. This steady expansion is supported by a broad international presence in over 180 countries. The company reported net income of roughly $309.1 million during this period, showing continued profitability even as it invests in new artificial intelligence agreement features to remain competitive.
Docusign maintains a healthy balance sheet with a debt-to-equity ratio of 0.1, which measures total debt against shareholder equity. As of its January 2026 balance sheet, the current ratio is 0.7, which compares a company's short-term assets to its short-term liabilities. Free cash flow, which is cash from operations minus capital expenditures, reached approximately $1.1 billion. Note that stock-based compensation accounted for roughly 53.4% of operating cash flow, inflating reported cash generation, as SBC is a non-cash expense added back in the cash flow statement.
The case for Okta
Okta provides identity and access management solutions to more than 20,000 customers globally, including large Fortune 50 enterprises and government agencies. Its latest annual report highlights a land-and-expand sales model used to increase its footprint among tech stocks. It manages an extensive integration network featuring over 7,000 connections with various cloud and mobile applications.
In fiscal 2026, revenue reached nearly $2.9 billion, representing approximately 11.8% growth over the previous year. This double-digit revenue increase remains higher than that of its e-signature peer, reflecting strong demand for cloud-based identity security. The company reported net income of roughly $235 million, a significant improvement from the fiscal year ended in 2024, when it reported a net loss.
Okta maintains a debt-to-equity ratio of 0.1, indicating its total debt is low relative to its shareholder equity. As of its January 2026 balance sheet, the current ratio is 1.4, suggesting the company has ample short-term assets to cover its upcoming liabilities. Free cash flow for the period was approximately $863.0 million. Note that stock-based compensation accounted for roughly 61.5% of operating cash flow, inflating reported cash generation, as SBC is a non-cash expense added back in the cash flow statement.
Risk profile comparison
Docusign faces intense competition, particularly from Adobe (NASDAQ:ADBE), which offers a rival document platform. Potential disruptions to the business model could arise from rapid advancements in artificial intelligence. Furthermore, the company deals with long and unpredictable enterprise sales cycles that make forecasting future revenue difficult. It also relies on third-party cloud service providers for infrastructure, which presents operational risks.
Okta must contend with intense competition from larger, well-established companies such as Microsoft. Any future cybersecurity incidents or service outages could harm the brand and lead to the loss of customer trust or regulatory scrutiny. Additionally, the company faces the ongoing challenge of maintaining its competitive advantage as AI-driven security threats evolve. Managing international operations also introduces complexity regarding global data privacy regulations.
Valuation comparison
Docusign appears cheaper than Okta when comparing their forward P/E and P/S ratios.
| Metric | Docusign | Okta |
|---|---|---|
| Forward P/E | 17.8 | 53 |
| P/S ratio | 4.6 | 11.3 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
Which stock would I buy for 2027?
One key difference between Okta and Docusign is how important their offerings are to keeping an organization running. I have personally used Docusign in the past, but I've also used other e-signature platforms that weren't all that different. They are all alike enough that I couldn't even tell you the specific software names. So there is a question in my mind of whether Docusign customers could simply substitute some other platform that's just as good (or close enough).
Okta, on the other hand, provides critical software to maintain organizational security and identity management. It's more important than ever for companies to lock down data for reputational, regulatory, and legal reasons. I think this makes Okta's products and services stickier than Docusign.
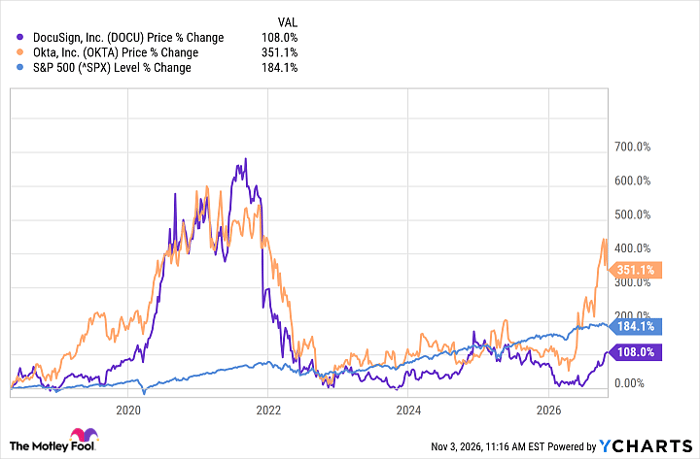
Now, let's turn to the tape:
DOCU data by YCharts
Okta stock has handily outperformed Docusign and the S&P 500 over the past decade or so. Okta's valuation is considerably higher than Docusign's, but I think the chart above indicates why investors are willing to pay that premium. Okta looks more attractive to me.
Should you buy stock in Docusign right now?
Before you buy stock in Docusign, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Docusign wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $336,195!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,241,567!*
Now, it’s worth noting Stock Advisor’s total average return is 875% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 4, 2026.
Erin Kennedy has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Adobe, Docusign, Microsoft, Okta, and Salesforce. The Motley Fool recommends the following options: long January 2028 $330 calls on Adobe and short January 2028 $340 calls on Adobe. The Motley Fool has a disclosure policy.
Recommended Articles


