

ServiceNow Shares Drop Over 18% as Slowing Q4 Growth Guidance Sparks Market Concerns

Source Tradingkey

TradingKey - On October 28 ET, ServiceNow (NOW) reported its third-quarter financial results, after which its stock plunged nearly 18% in after-hours trading. As of press time, ServiceNow dropped 18.79% in overnight trading to $121.92.
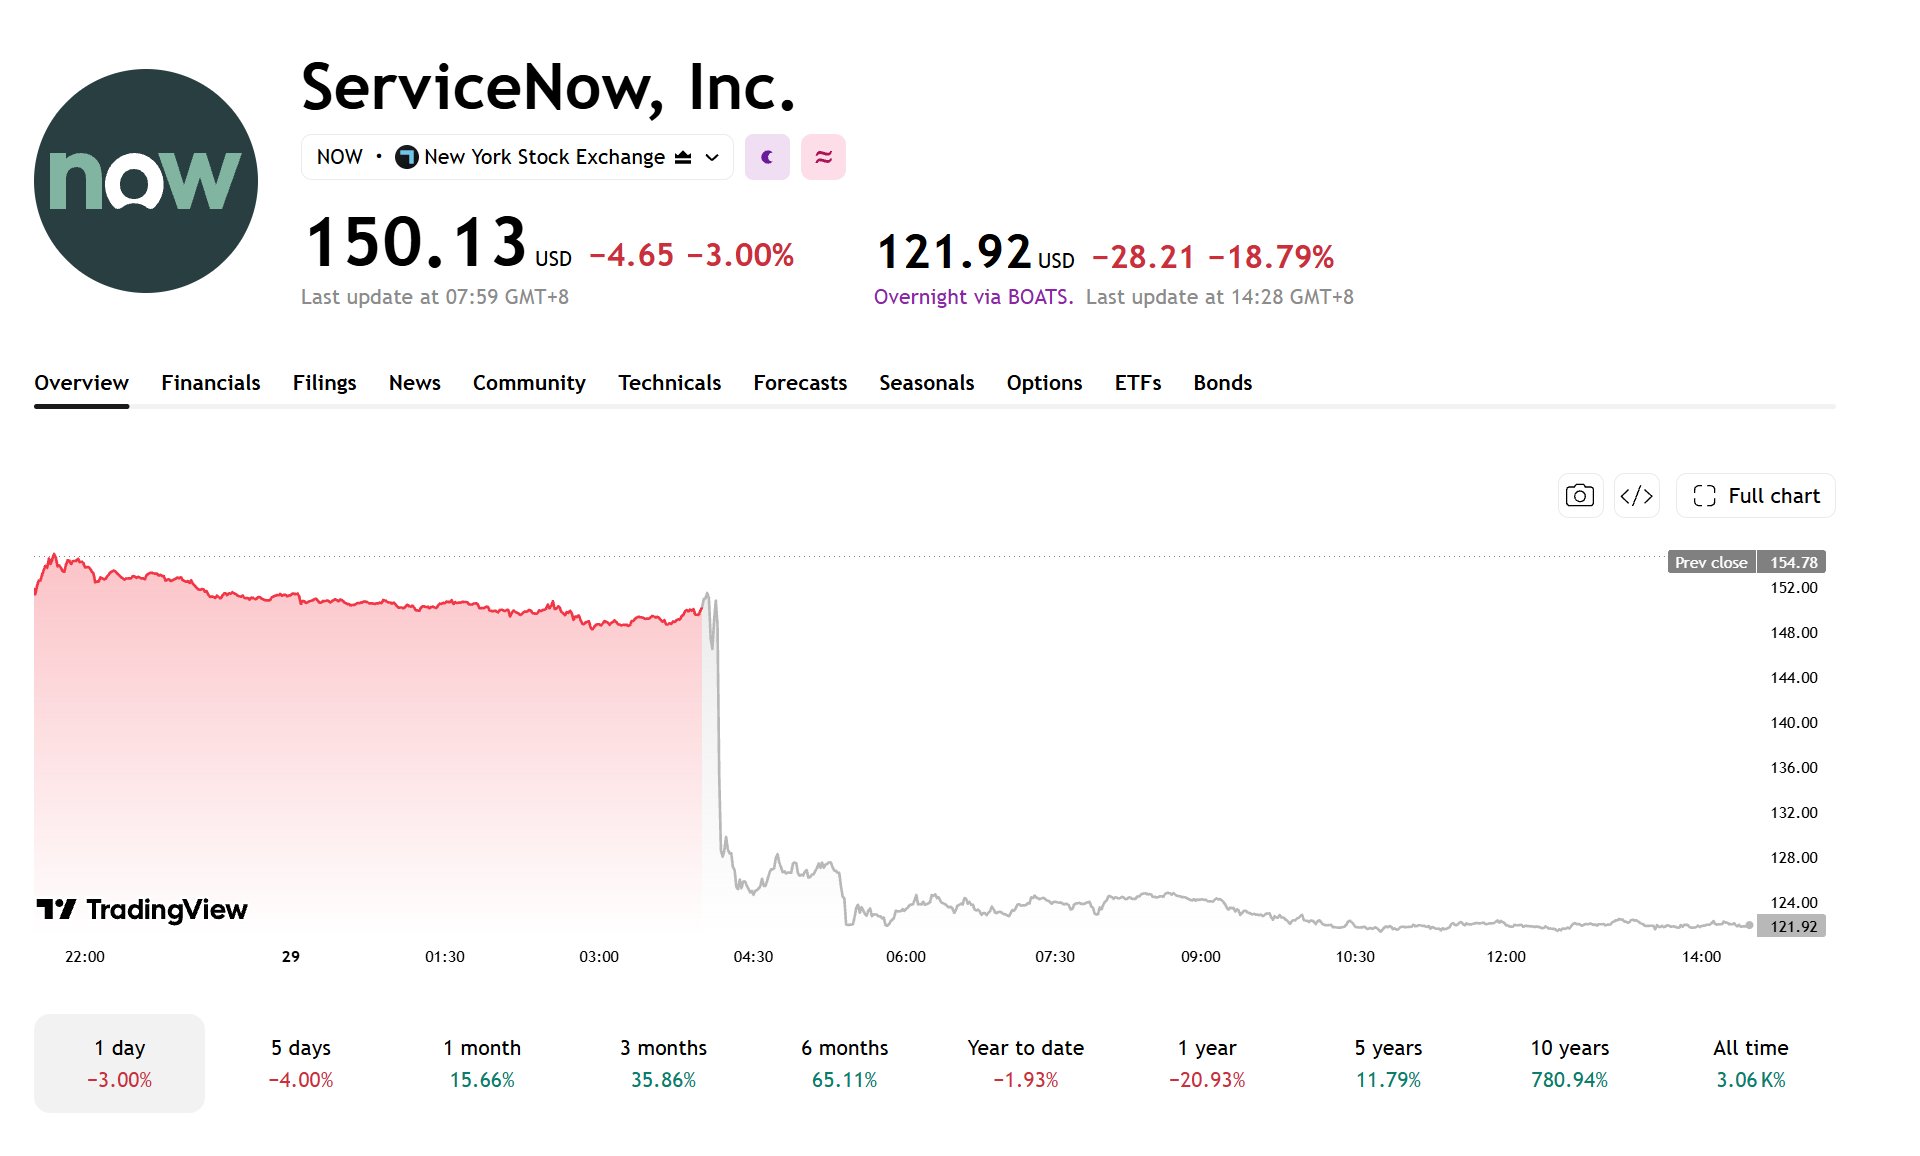
NOW-029-d99e03ce59ec49a590ceb83ffb3da748

[Source: TradingView]

Although the company raised its full-year subscription revenue guidance and increased its 2026 AI product annual contract value target to $17 billion, an expected slowdown in fourth-quarter current remaining performance obligations (cRPO) growth, combined with adjusted earnings per share missing market expectations, has prompted the market to reevaluate the company's growth prospects.

ServiceNow Q3 Results: Revenue Grows, EPS Misses Estimates

ServiceNow's third-quarter revenue increased 20.5% year-over-year to $4.106 billion, with subscription revenue rising 21% year-over-year to $3.988 billion. As of September 30, the company's remaining performance obligations (RPO) reached $29.7 billion, up 22% year-over-year; contract revenue expected to be recognized over the next 12 months (cRPO) was $13.65 billion, up 20.5% year-over-year.

Third-quarter non-GAAP adjusted earnings per share were $1.00, falling short of the $1.02 expected by analysts. The company's interest income declined year-over-year, while interest expenses rose due to increased financing costs related to the Armis acquisition, weighing on earnings.

Overall, the company maintained growth in revenue and subscription revenue, but its adjusted earnings per share fell slightly short of market expectations.

Why Expected Slowdown in Q4 Order Growth Triggers Market Concern?

ServiceNow expects fourth-quarter cRPO to grow 18.5% year-over-year in constant currency, down from 21% in the third quarter. This metric reflects contracted revenue expected to be recognized over the next 12 months, and its slowing growth suggests that future subscription revenue growth may come under pressure, sparking market concerns about the company's growth prospects.

On the AI front, ServiceNow raised its 2026 annual contract value (ACV) target for AI products to $1.7 billion, up 70% from the $1 billion set at the beginning of the year, marking its second target upgrade this year and indicating that the commercialization of AI products is progressing better than previously expected.

However, investors still need to monitor whether new contracts can consistently translate into subscription revenue and whether AI business growth can further drive profitability.

How to View ServiceNow's Stock Price Outlook?

ServiceNow expects fourth-quarter subscription revenue of $4.245 billion to $4.255 billion, up 22.5% to 23% year-over-year, and raised its full-year 2026 subscription revenue guidance to $15.78 billion to $15.79 billion.

Although the fourth-quarter subscription revenue growth guidance was higher than the third quarter's 21%, the company expects contract revenue growth over the next 12 months to slow to 18.5%, down from 21% in the third quarter, sparking market concerns over its future growth momentum.

Looking ahead, key areas to monitor include fourth-quarter subscription revenue performance and the progress of its AI business. If contract revenue growth continues to slow and the AI business fails to further drive revenue and profit growth, ServiceNow's stock price may remain under pressure; if subscription revenue maintains steady growth, market concerns regarding the company's growth prospects are expected to ease.

Disclaimer: For information purposes only. Past performance is not indicative of future results.
placeholder
Big Tech's $800 billion AI bill faces its first real test — free cash flow is the judgeAlphabet and Microsoft report after the close on October 28, Amazon on October 29, with hyperscaler AI capex running near $800 billion a year. Meta's negative free cash flow and 9.40% drop on October 22 was the warning; this week's prints decide whether cloud growth and backlog can pay for the buildout. Here are the consensus numbers, the free-cash-flow table and the two-sided test.
Author  Irene Q.
Oct 26, Mon
Alphabet and Microsoft report after the close on October 28, Amazon on October 29, with hyperscaler AI capex running near $800 billion a year. Meta's negative free cash flow and 9.40% drop on October 22 was the warning; this week's prints decide whether cloud growth and backlog can pay for the buildout. Here are the consensus numbers, the free-cash-flow table and the two-sided test.
placeholder
Anthropic files for a $2 trillion IPO — the $80.7 billion loss is the decoy, the $450 billion compute bill is the riskAnthropic publicly filed its S-1 on October 26, revealing $16.29 billion of first-half revenue (+1,304% year over year) and a $80.7 billion net loss — of which $72.4 billion is a non-cash convertible-note charge. The real number is the $450 billion of signed, mostly non-cancelable compute commitments. Here is what the filing says, why NVDA, ARM and MU are the tradeable read-through, and the conditions that decide whether the AI trade passes its first public valuation test.
Author  Irene Q.
Oct 27, Tue
Anthropic publicly filed its S-1 on October 26, revealing $16.29 billion of first-half revenue (+1,304% year over year) and a $80.7 billion net loss — of which $72.4 billion is a non-cash convertible-note charge. The real number is the $450 billion of signed, mostly non-cancelable compute commitments. Here is what the filing says, why NVDA, ARM and MU are the tradeable read-through, and the conditions that decide whether the AI trade passes its first public valuation test.
placeholder
Fed October Rate Decision Preview: Rate Hike Pause Has Become Consensus, How Will US Stocks, Dollar, and Gold React?The Federal Reserve will announce its October interest rate decision at 14:00 Eastern Time on October 28, and Fed Chair Warsh will hold a press conference at 14:30. Markets currently wide
Author  TradingKey
Oct 27, Tue
The Federal Reserve will announce its October interest rate decision at 14:00 Eastern Time on October 28, and Fed Chair Warsh will hold a press conference at 14:30. Markets currently wide
placeholder
Brent's $115 front month sits $4.6 above January — the $14 spread to WTI is the supply-risk premiumDecember Brent trades at $115.29 while January is $110.71, a $4.58 backwardation. The December Brent-WTI spread is $14.2, versus a $3-5 normal. That gap, not the headline, is where the Middle East supply risk is priced. Here is what the curve says, why the December contract's expiry on October 30 will mechanically cut the headline by $4.6, and the 108.81 neckline that decides the next move.
Author  Irene Q.
Yesterday 06: 21
December Brent trades at $115.29 while January is $110.71, a $4.58 backwardation. The December Brent-WTI spread is $14.2, versus a $3-5 normal. That gap, not the headline, is where the Middle East supply risk is priced. Here is what the curve says, why the December contract's expiry on October 30 will mechanically cut the headline by $4.6, and the 108.81 neckline that decides the next move.
placeholder
Gold Price Analysis Today | Forex Gold Analysis | XAU/USD Analysis - October 29, 2026Get the latest gold price analysis, forex gold insights, and XAU/USD analysis for October 29, 2026. Read on for the details.
Author  Mitrade
7 hours ago
Get the latest gold price analysis, forex gold insights, and XAU/USD analysis for October 29, 2026. Read on for the details.
goTop
quote