


Not Nvidia. Not Micron. This Underappreciated AI Stock Could Be 2027's Biggest Winner.
Key Points
Western Digital has been a major beneficiary of the AI boom, as demand for its storage drives has outpaced supply.
The company's solid growth potential and attractive valuation suggest it could soar after a stellar 2026.
Analysts expect significant upside for Western Digital over the coming year, but I won't be surprised if it outpaces expectations.
- 10 stocks we like better than Western Digital ›
Nvidia and Micron Technology have benefited big time from the artificial intelligence (AI) infrastructure boom, driven by their mission-critical chips that play a central role in handling training and inference workloads in data centers.
Both companies have been growing at a solid pace and, importantly, can sustain their healthy growth momentum in 2027. However, there is another AI stock that I think could outperform Nvidia and Micron in 2027.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Western Digital (NASDAQ: WDC) is an important player in the AI infrastructure ecosystem, manufacturing data storage devices that are deployed by hyperscalers and enterprises. Shares of the company have jumped by 103% in 2026, though the past few months have been quite rough for shareholders.
Specifically, Western Digital has dropped 49% from the 52-week high it reached on June 18. However, I think this is an opportunity for savvy investors to add a top growth stock to their portfolios. Let's look at the reasons why Western Digital can step on the gas and become a big winner in 2027.
Image source: Getty Images.
AI-driven storage demand will help Western Digital sustain its terrific momentum
Western Digital released fiscal 2027 first-quarter results (for the three months ended Oct. 2) on Oct. 22. The company's revenue jumped by 55% from the year-ago period to $4.38 billion. Even better, its non-GAAP gross margin increased to 58.1% from 43.9% in the year-ago quarter. This impressive expansion in Western Digital's margins led to a 161% year-over-year increase in the company's non-GAAP earnings per share (EPS) to $4.64.
Western Digital's numbers exceeded expectations. What's more, the company anticipates a stronger jump of 69% in revenue in the current quarter. Meanwhile, non-GAAP gross margin is poised to jump to a range of 60% to 61%, well above the year-ago period's reading of 46.1%. As a result, Western Digital expects adjusted EPS to jump to $5.80 from $2.13 in the year-ago period.
The healthy demand for data storage in AI data centers is behind this phenomenal growth. The company gets 88% of its revenue from the cloud segment, and the good part is that this segment is on track to continue growing at a robust pace over the long run. Western Digital estimates that the AI and cloud storage market will grow at a 25% compound annual growth rate (CAGR) through 2030.
The company also points out that 80% of cloud storage happens on hard disk drives (HDDs). An important point to note is that the AI-driven data storage boom has created a shortage of high-capacity HDDs. Western Digital's rival Seagate Technology notes that it has sold out its 2028 capacity already. Similarly, Western Digital has already received commitments for most of its 2027 capacity, and it is receiving orders for 2028 and 2029.
What's more, Western Digital's customer base is still expanding. The company will start shipping its first-generation heat-assisted magnetic recording (HAMR) high-capacity HDD to two hyperscale customers in the first half of next year. It anticipates adding two more customers for its HAMR solution in the first half of 2027.
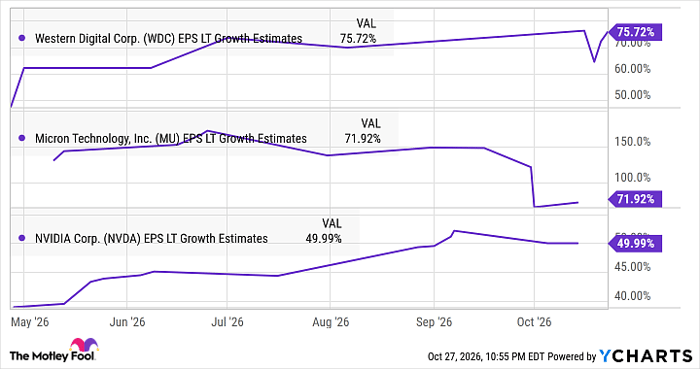
So, Western Digital is poised to enjoy healthy demand next year, while the accompanying supply shortage should ensure further margin improvements. So, it is easy to see why analysts have become bullish about Western Digital's long-term earnings growth prospects. In fact, as the chart below shows, its EPS growth could outpace that of both Nvidia and Micron.
Data by YCharts
The valuation makes Western Digital a solid buy
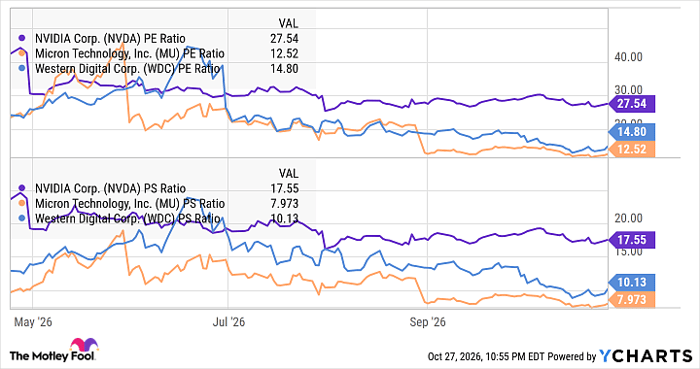
Western Digital trades at an incredibly attractive valuation. It is significantly cheaper than Nvidia and carries only a slight premium to Micron.
Data by YCharts
Also, Western Digital's 12-month median price target of $625 implies a 64% jump from current levels. That's higher than the implied upside of 47% for Nvidia, and slightly lower than the 70% upside expected in Micron, based on their 12-month median price targets. I won't be surprised to see Western Digital outperform Nvidia and Micron next year, given its exponential growth, solid prospects, and attractive valuation.
So, investors looking to buy a top stock trading at an attractive valuation can consider buying Western Digital right away before it starts soaring once again.
Should you buy stock in Western Digital right now?
Before you buy stock in Western Digital, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Western Digital wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $337,166!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,339,143!*
Now, it’s worth noting Stock Advisor’s total average return is 904% — a market-crushing outperformance compared to 213% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 28, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Micron Technology, Nvidia, and Western Digital. The Motley Fool has a disclosure policy.
Recommended Articles


