


Did Greg Abel Already Make His First Big Mistake as Berkshire Hathaway CEO?
Key Points
American Express’s closed-loop system makes it noticeably different from open-loop systems operated by Visa and Mastercard.
American Express is an exception to the trend of Berkshire Hathaway reducing its exposure to financial stocks.
Berkshire’s stake in American Express has increased due to stock buybacks, not additional share purchases.
- 10 stocks we like better than American Express ›
Warren Buffett's hand-picked successor, Greg Abel, became chief executive officer of Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB) on Jan. 1. Within months, he made a number of changes, including selling stakes in many smaller holdings, such as Visa (NYSE: V) and Mastercard (NYSE: MA), and pole-vaulting Alphabet into a core holding (on Buffett's recommendation). Just as meaningful was inaction on key holdings like American Express (NYSE: AXP) and Coca-Cola (NYSE: KO) -- which signaled a vote of confidence amid the portfolio reshuffling.
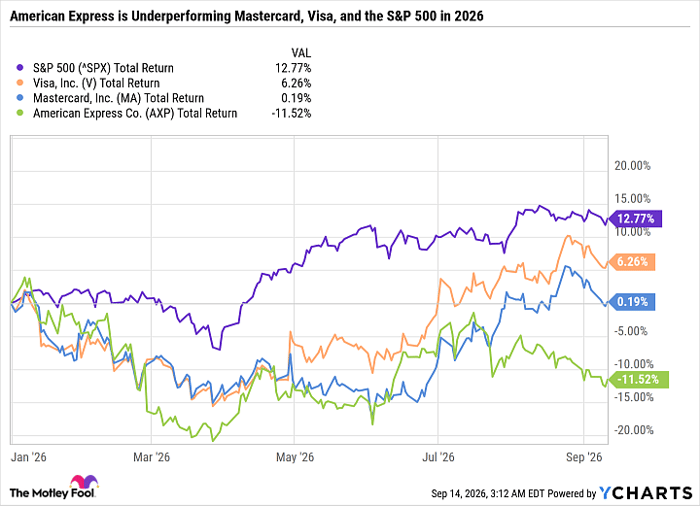
American Express is underperforming Visa and Mastercard year-to-date. So at first glance, it may look like it was a mistake to sell Berkshire's entire stakes in Visa and Mastercard and bet solely on American Express. But context is in order.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: The Motley Fool.
American Express is underperforming its peers
American Express is a huge Berkshire Hathaway holding -- second only to Apple (NASDAQ: AAPL). And like Coca-Cola, Berkshire has owned it for decades, whereas Visa and Mastercard were relatively small holdings acquired more recently. Similarly, Berkshire sold its entire Amazon stake and significantly increased its stake in Alphabet, thereby reducing overlap in the cloud computing and artificial intelligence sector and centering the portfolio around a core holding.
^SPX data by YCharts
In his first letter to shareholders as CEO, Greg Abel identified American Express as a stock that Berkshire understands well, trusts its management team, and expects to compound over the long term. That trust extends far beyond a matter of months. And in his letter, Abel said Berkshire's concentrated approach will continue, and investors can expect limited activity in holdings such as Apple, American Express, Coca-Cola, and Moody's, although adjustments may be made if fundamentals change.
Despite underperforming Visa and Mastercard year-to-date -- American Express's fundamentals remain rock solid. The company is generating all time high revenue and earnings and has forecast 10% year-over-year revenue growth in 2026. Expenses are on the rise, and gross margins have compressed as American Express is spending more on advertising and cardmember rewards. But those expenses could pay off if they help attract and retain high-quality customers.
American Express is a great value
American Express has become Berkshire's second-largest holding, behind Apple, due to a combination of its rising stock price and aggressive stock buybacks. Buybacks benefit long-term shareholders by reducing the share count outstanding, which accelerates earnings-per-share growth and makes the stock a better value, while also giving loyal shareholders a larger stake in the company.
Berkshire essentially completed its purchases of American Express stock in 1995. During the past 31 years, American Express has reduced its share count by almost 59%. Berkshire now owns roughly 24% of the entire company thanks to buybacks -- a position that's worth $49.2 billion.
In addition to its fundamentals and excellent business model, American Express's huge buyback program and increasing dividend are reasons to buy and hold the stock over the long term. Its price-to-earnings (P/E) ratio has come down to 19.6, and its forward P/E is now just 16.3 -- far lower than Visa's and Mastercard's forward P/E of about 25.
However, part of the reason American Express trades at a steep discount to its peers is that investors view it as a middle ground between high-margin payment processing and capital-intensive bank stocks, which tend to sport very low valuations. American Express operates a closed-loop system -- serving as the payment processor, card issuer, and lender. Whereas Visa and Mastercard offer open-loop systems by partnering with financial institutions that issue cards, manage the cardmember rewards programs, and bear the credit risk.
American Express serves a key role in Berkshire's portfolio
When Abel took over as CEO, the biggest question mark was how he would handle Berkshire's mega holdings. It's clear that Berkshire still views American Express as a long-term compounder, and it's its highest conviction stock in the payment processing sector.
Under Buffett, Berkshire repeatedly trimmed its position in Bank of America and fully exited its Citigroup position in late 2025. So, keeping American Express is a way to retain exposure to a high-quality, multi-faceted financial stock that is distinct from Berkshire's other public equity holdings and its company-controlled insurance businesses.
Another reason Abel may have wanted to continue trimming financial stocks is that the sector has run up significantly in recent years, and Abel may have wanted to book the gains at favorable tax rates and shore up cash to invest in growth plays like Alphabet. Berkshire still has an enormous cash, cash equivalent, and Treasury Bill position valued at $365.5 billion as of June 30, but that's down 8% from March 31, due to the rapid accumulation of Alphabet stock.
Holding American Express is the right long-term move
Investors shouldn't judge Berkshire's holdings over a short period, but rather, how its high conviction bets stack up compared to the benchmarks during at least a three to five-year period. To be sure, Abel had the chance to sell some American Express shares near an all-time high as part of a broader portfolio restructuring. So criticism would be more warranted if American Express drastically underperforms Visa, Mastercard, and the financial sector over a long-term period rather than a handful of months.
However, I fully expect American Express to remain an excellent long-term buy for patient investors, given its customer loyalty, relatively straightforward business model, and recurring revenue from cardholder and swipe fees.
Add it all up, and American Express remains a top blue-chip dividend stock to buy now.
Should you buy stock in American Express right now?
Before you buy stock in American Express, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and American Express wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $433,160!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 949% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 15, 2026.
American Express is an advertising partner of Motley Fool Money. Bank of America is an advertising partner of Motley Fool Money. Citigroup is an advertising partner of Motley Fool Money. Daniel Foelber has positions in American Express. The Motley Fool has positions in and recommends Amazon, American Express, Apple, Berkshire Hathaway, Mastercard, Moody's, and Visa. The Motley Fool has a disclosure policy.
Recommended Articles


