


1 Glorious Growth Stock to Buy Before It Climbs by 33%, According to Wall Street
Key Points
Workiva's software helps enterprises aggregate their data for reporting and compliance purposes.
The company is embedding artificial intelligence into its products to make them more powerful than ever.
Workiva stock is attractively valued, and the majority of the analysts tracked by The Wall Street Journal think it's a buy.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Workiva's (NYSE:WK) software products help enterprises manage their financial reporting and regulatory compliance obligations. The company recently started using artificial intelligence (AI) to make its products more powerful than ever, which could encourage more spending per customer over time.
Despite Workiva's steady growth at the top and bottom lines, its stock is down 17% this year. But Wall Street sees an opportunity; the majority of the analysts tracked by The Wall Street Journal have given Workiva stock a buy rating, and none recommend selling. Their average price target points to a potential return of 33% over the next 12 months, and here's why I think it's more than achievable.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »

Image source: Getty Images.
AI is creating new opportunities for Workiva and its customers
Most large organizations use dozens, and sometimes even hundreds of digital applications to run their day-to-day operations. This creates a nightmare for managers tasked with compiling data for the purposes of preparing regulatory filings and executive reports, which can be a long and error-prone process.
Workiva's software streamlines the process by plugging into all major third-party productivity apps, storage platforms, and systems of record, and autonomously aggregating all of their data onto one dashboard. It creates a single source of truth for managers, and using one of Workiva's many templates, they can rapidly turn that data into internal reports or filings for regulators like the Securities and Exchange Commission (SEC).
Workiva is now embedding AI into its platform to enhance its capabilities. One example is the tie-out agent, which helps managers verify the accuracy of the numbers in their reports. It autonomously flags discrepancies and provides a clear explanation for every instance. This is a powerful tool because AI agents can read and compare documents significantly faster than humans.
But the company also launched the Agent Studio in September, where enterprises can create their own custom agents to perform specific tasks within the Workiva ecosystem. Managers can use plain language to design agents, so they don't need to write a single line of code. Over time, the Agent Studio could save enterprises significant amounts of time and money by automating a variety of different workflows.
Steady revenue growth and an improving bottom line
Workiva generated $263 million in revenue during the third quarter of 2026 (ended Sept. 30), topping management's forecasted range of $260 million to $262 million. It represented a 17% increase from the year-ago period, but I think the company could have grown even faster if it wasn't carefully managing costs to boost its bottom line.
Workiva grew its total operating expenses by just 7.8% during the third quarter, and it actually reduced administrative costs, specifically. Since revenue grew at a much faster pace, more money flowed to the bottom line as profit, resulting in a generally accepted accounting principles (GAAP) net income of $19.1 million. That was up by a whopping 582% from the year-ago period.
Moreover, after excluding one-off and non-cash expenses like stock-based compensation, Workiva's adjusted (non-GAAP) net income grew by 50% to $43.3 million.
But despite carefully managing expenses like marketing, Workiva still attracted hordes of new, high-spending enterprises. It had 6,840 total customers at the end of the third quarter, up 4.6% from the year-ago period, but the number of customers with annual contract values of at least $100,000 jumped by 20% to 2,853. Further, the number of customers with annual contract values of at least $300,000 soared by 31% to 708.
Why Wall Street's bullishness might be justified
The Wall Street Journal tracks 13 analysts who cover Workiva stock, and nine of them have assigned it a buy rating. Three others are in the overweight (bullish) camp, while the remaining analyst recommends holding. None recommend selling.
The analysts have an average price target of $91.50, suggesting Workiva stock could climb by 33% over the next 12 months. The Street-high target of $111 implies an even greater potential upside of 62%.
I think both targets are achievable because of Workiva's valuation. Its stock is trading at a price-to-sales (P/S) ratio of 3.9, so it's much cheaper than the Nasdaq-100 index which has a P/S ratio of 6.2. Therefore, it appears to be undervalued compared to a group of America's top technology companies.
Moreover, Workiva stock would have to rise by 88% just to trade in line with its five-year average P/S ratio of 7.3.
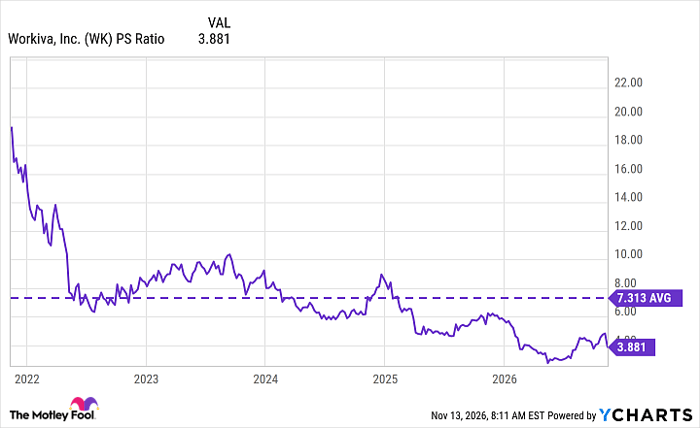
WK PS Ratio data by YCharts
As a result, Wall Street's price targets might actually be conservative. But investors could earn even greater returns over the long term, because Workiva believes it can generate up to $2 billion in annual revenue by 2030, almost doubling its expected 2026 revenue of $1.04 billion.
I think Wall Street's bullish stance on Workiva stock is justified.
Should you buy stock in Workiva right now?
Before you buy stock in Workiva, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Workiva wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 16, 2026.
Anthony Di Pizio has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Workiva. The Motley Fool has a disclosure policy.
Recommended Articles


