


Despite Strong Revenue Growth and a Cheap Valuation, Supermicro Stock Is Still Not a Buy
Key Points
Supermicro is seeing huge revenue growth.
Its checkered history and deep ties to the neocloud market make it a riskier investment.
- 10 stocks we like better than Super Micro Computer ›
With a long history of controversy, Super Micro Computer (NASDAQ: SMCI) is one of the most divisive stocks in the market. The company has been growing revenue quickly and remains a clear beneficiary of the AI build-out. However, it also has a history of accounting issues, and three now-former employees have been charged by the Department of Justice with violating U.S. technology export bans. As such, the stock is down by more than 35% over the past year, while rivals Dell and Hewlett Packard Enterprise have more than doubled over the same period.
Supermicro designs and assembles servers and rack solutions for data centers. It normally customizes its systems around Nvidia's graphics processing units (GPUs), and provides turnkey solutions that include things like networking, cooling, and software. The company has said its big advantage is speed, as its integrated rack solutions get customers up and running more quickly.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Despite being a key player in the artificial intelligence (AI) infrastructure build-out, Supermicro has dealt with a lot of issues over the past few years. A short-seller accused the company of accounting irregularities in 2024, and the subsequent investigations eventually led to the company's auditor resigning and delays in its regulatory filings. This was preceded by the SEC (Securities and Exchange Commission) fining the company in 2020 for improperly recognizing revenue, and in 2018, the stock was delisted from the Nasdaq after the company failed to file financial reports. It did not relist on the exchange until 2020.
The biggest issue the company faces currently, however, is that three former employees, including one of its co-founders, have been charged with illegally smuggling high-end Nvidia GPUs into China through an elaborate scheme that involved fake paperwork, "dummy" servers, and a Thailand-based company that acted as an intermediary. Throughout all these scandals, somehow, CEO Charles Liang has managed to stay in charge.
Image source: The Motley Fool.
Strong growth and outlook
While the company has dealt with a lot of controversy, it has also produced some strong growth this calendar year.
In its fiscal 2027 first quarter (which ended Sept. 30), Supermicro's revenue nearly quadrupled year over year from $5 billion to $19.9 billion. That was well above the $14.5 billion to $15.5 billion range that management forecast in August.
Supermicro is in a low-gross-margin business, as much of its revenue is essentially the pass-through cost of expensive GPUs. It has dealt with issues in the past, but its gross margins appear to be recovering from a recent all-time low. Gross margin came in at 12.7% in fiscal Q1. That was up from 9.3% a year ago, although down from 17.5% last quarter. The company said it is seeing improvement stemming from the growing contribution of higher-margin solutions, like its DCBBS (Data Center Building Block Solutions) model, which is a modular, pre-designed turnkey solution that includes customer-specific software.
Adjusted earnings per share (EPS), meanwhile, soared from $0.35 to $1.81. That was well ahead of its guidance for EPS of between $1.01 and $1.10.
Management projects that fiscal 2027 Q2 revenue will be between $19.5 billion and $21.5 billion, up from $12.7 billion in the prior-year period. It guided for EPS of between $1.66 and $1.90, up from $0.69 last year.
The company also raised its fiscal-year revenue forecast to between $72 billion and $82 billion, up from a prior outlook of $65 billion to $72 billion.
A cheap stock, growing quickly
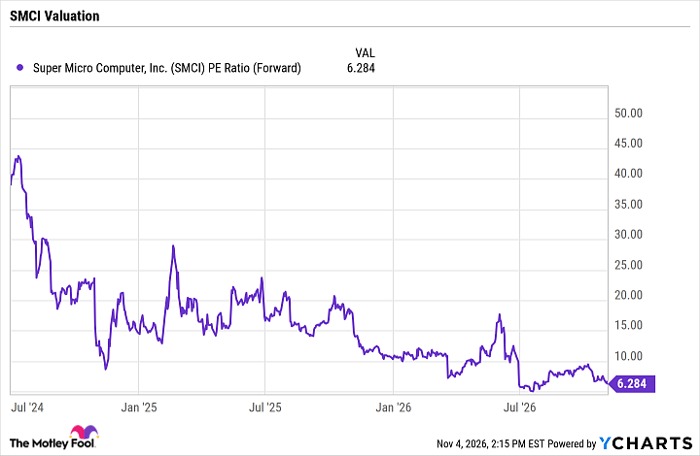
Supermicro is seeing incredible growth, while the stock trades at a cheap forward price-to-earnings ratio (P/E) of just above 6, based on fiscal 2027 analyst estimates. That said, I would still not buy the stock.
SMCI PE Ratio (Forward) data by YCharts.
The company's checkered history will likely keep a lid on its valuation multiples. Meanwhile, according to Goldman Sachs, Supermicro is highly tied to the neocloud niche, estimating that it has about a 40% share of the server market for neoclouds. The neoclouds already face financing issues relating to the debt they must take on to build out new data centers.
Moreover, after the new crop of governors and legislators elected in this week's midterms takes office, changes across various governments could lead to longer permitting timelines for data centers, create additional hurdles to their construction, and put pressure on the space. That would be bad news for SMCI, and at the least could reduce the value of its speed advantage.
As such, I'd avoid Supermicro -- there are better AI stocks to own.
Should you buy stock in Super Micro Computer right now?
Before you buy stock in Super Micro Computer, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Super Micro Computer wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $358,037!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,229,708!*
Now, it’s worth noting Stock Advisor’s total average return is 897% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 6, 2026.
Geoffrey Seiler has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Goldman Sachs Group, Hewlett Packard Enterprise, and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


