


Nvidia Stock Forecast: China Shipment Delays Put $173.69 in Focus
TradingKey - Nvidia (NASDAQ: NVDA) closed November 5 at $181.60, down 9.26%, just $0.14 above its session low. A Reuters report describing H200 chips awaiting mainland Chinese import approval adds uncertainty ahead of November 17 earnings.
The fundamental debate is whether demand converts into profitable deliveries and cash. China is a potential source of additional business, but Nvidia’s existing quarterly forecast already excludes Data Center compute revenue from that market.
China’s Import Hold Complicates Delivery
Reuters reported that approximately 600,000 H200 chips were stored in Hong Kong awaiting shipment to mainland China, citing people familiar with the matter. Beijing had permitted limited shipments but had yet to approve large-volume imports. Nvidia did not respond to Reuters’ request for comment.
The report establishes a delivery bottleneck without establishing ownership of every chip in storage or the accounting treatment of prior transactions. It would be premature to translate the reported quantity into Nvidia revenue, a write-down or a canceled order balance.
The exclusion of China compute revenue from guidance narrows the immediate earnings risk. Continued restrictions could delay future upside, while shipment approvals would still need to produce recognized sales before changing the financial assessment.
The Earnings Base Includes Investment Gains
Nvidia’s latest reported quarter ended July 26. Revenue rose 106% to $96.2 billion, with Data Center revenue up 117% to $89.0 billion. GAAP diluted EPS was $2.46 and adjusted EPS was $2.22.
Reported profit included $7.771 billion in net gains from equity securities, which Nvidia excludes from adjusted results. GAAP operating income reached $63.734 billion, providing a measure of business performance before those investment gains. The earnings reconciliation also includes other adjustments and tax effects, so subtracting the gross investment gain directly from EPS would misstate the comparison.
I would give more weight to operating profitability and collections than to changes in portfolio valuations.
Oracle Broadens the Rubin Deployment Opportunity
Nvidia and Oracle announced on October 27 that Vera Rubin NVL72 systems and Vera CPUs were generally available on Oracle Cloud Infrastructure. They also outlined plans to expand Rubin infrastructure to multi-gigawatt scale.
Nvidia can participate in more of each deployment by supplying computing, networking and the software that connects them. That broadens the commercial opportunity, but customer facilities still need adequate power, cooling and installation capacity.
General availability marks a product milestone. The planned expansion remains dependent on execution, and its ultimate revenue contribution will emerge through deliveries and customer usage.
Meta Links Customer Expansion With Capital Investment
Nvidia’s separate October 27 announcement described expanded collaboration on Meta’s Muse models, including intended deployments of Vera Rubin, Vera CPUs and networking. Nvidia also announced plans to invest $3 billion in Meta’s equity offering.
The two commitments have different financial consequences. Equipment deliveries can generate sales, while buying equity uses capital and exposes Nvidia to investment returns. The announcement gives no basis for assuming the investment proceeds are reserved for Nvidia purchases.
Expansion is more durable when customers can generate sufficient cash from their AI services to support further equipment purchases.
Cash Collection Must Keep Pace With Shipments
Quarterly operating cash flow was $24.077 billion. The cash-flow statement recorded a $22.346 billion use of cash from changes in receivables and $5.784 billion from inventory changes. Those movements help explain why cash generation lagged reported profit.
Rapid expansion can require more stock on hand and leave more money awaiting customer payment. The question is whether those balances normalize as deliveries mature. Persistently slower collections would make growth more demanding to fund and would warrant closer examination of customer payment terms.
November 17 Tests the $108 Billion Forecast
Management forecasts third-quarter revenue of $108 billion, plus or minus 2%, and GAAP and adjusted gross margins of 74%, plus or minus half a percentage point. Both margins were 75% in the preceding quarter.
Results are scheduled for approximately 1:20 p.m. Pacific on November 17, followed by the conference call at 2 p.m. Pacific. Until that release, the figures remain guidance. Delivery progress, gross margin and the next sales outlook will determine whether the business is meeting the expectations already embedded in its expansion plans.
Nvidia Technical Analysis: $190.01 Rejection Would Favor $173.69
Nvidia’s daily close at $181.60 followed a break beneath its rising trendline and the support zone below $190.01. The session low was $181.46, leaving almost no recovery into the close. That position suggests sellers retained control despite the size of the decline.
RSI at 25.40 is explicitly oversold, making a relief rebound plausible. MACD’s widening negative histogram still indicates strengthening selling momentum on the supplied chart. Oversold conditions alone provide insufficient confirmation that a durable low has formed.
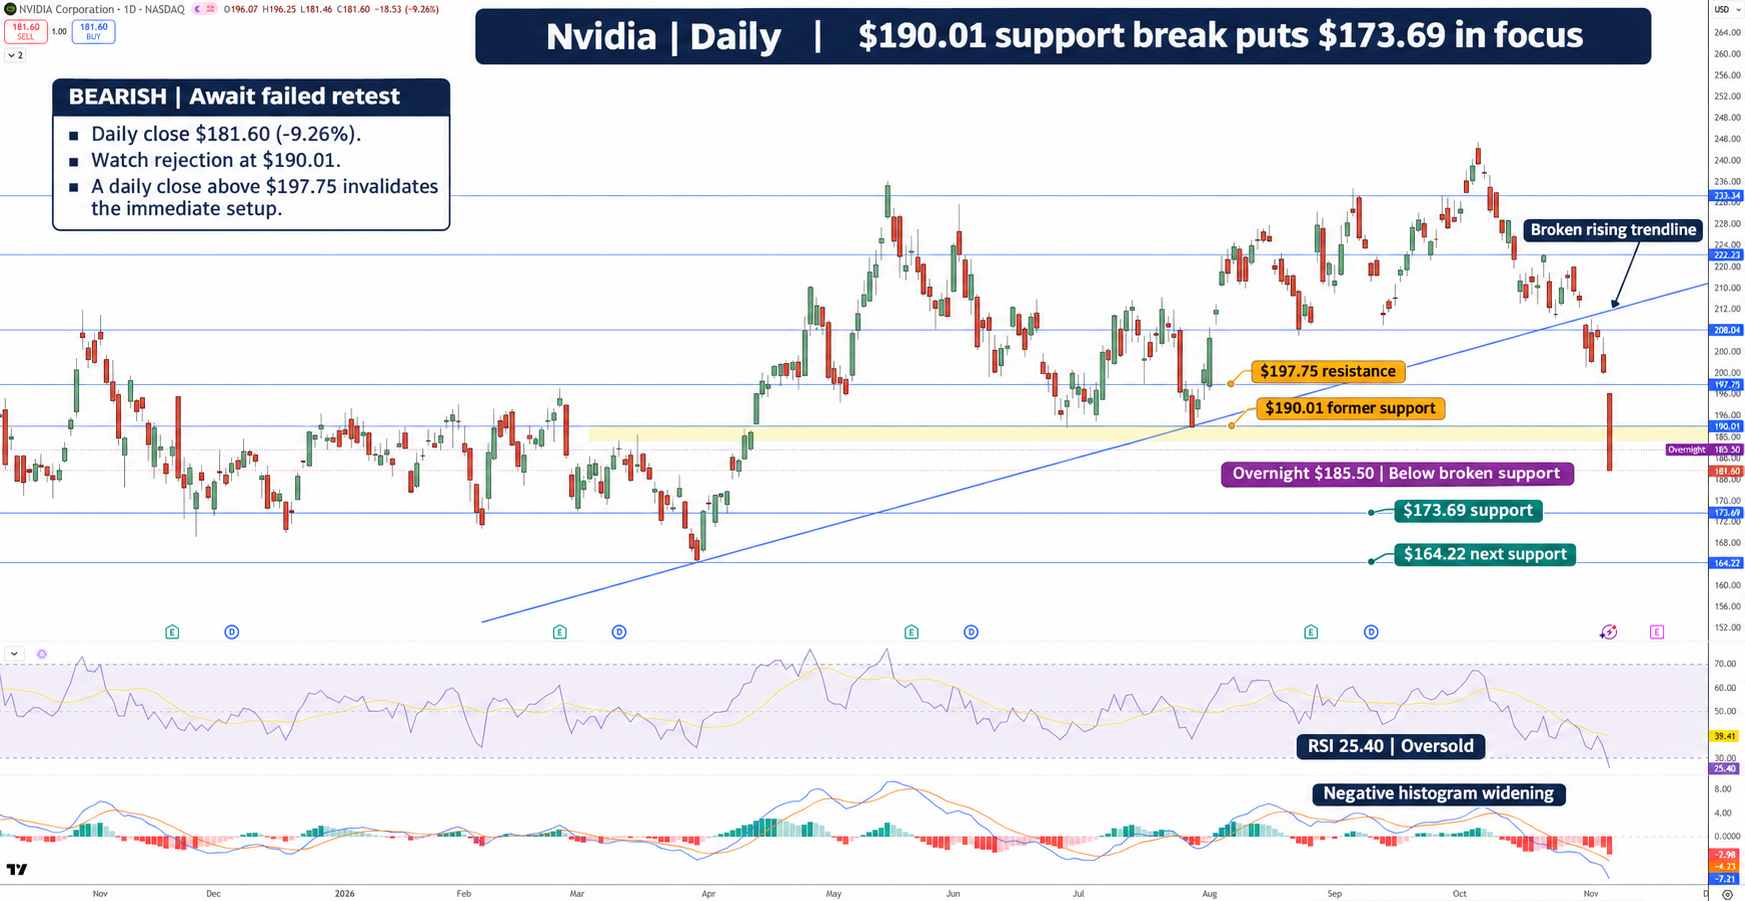
NVDA Price Chart - Source: Tradingview
I remain bearish while rebounds fail at $190.01. A rejection there would favor $173.69, with a daily close below that support opening the way toward $164.22. The supplied $185.50 overnight quote represents a separate-session recovery and still sits below broken support.
A sustained reclaim of $190.01 would weaken the immediate selling case. A daily close above $197.75 would invalidate it, although the broken rising trendline remains an additional obstacle.
Key Levels
- Latest completed close: $181.60 on November 5
- Immediate resistance: $190.01
- Upside confirmation and invalidation level: $197.75
- Immediate marked support: $173.69
- Downside target: $164.22
- Daily RSI: 25.40, oversold
FAQ
Does Nvidia’s forecast depend on China compute sales?
Its existing quarterly revenue guidance assumes no Data Center compute revenue from China.
What would invalidate the bearish NVDA setup?
A daily close above $197.75 would invalidate the immediate bearish call. A reclaim of $190.01 would be an earlier improvement.
Bottom Line
Nvidia’s operating growth remains strong, but delivery access and cash collection require scrutiny. The chart favors sellers below $190.01, with $173.69 next. A daily close above $197.75 would change that near-term view.
Recommended Articles


