


Is Arm Holdings a Buy After Its Latest Earnings Report?
Key Points
Wall Street isn't impressed with the chip designer's latest results.
Visible growth is solid, but recurring revenue will depend on actual chip production going up.
At 75 times forward earnings, there needs to be a better entry point for the stock.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Arm Holdings (NASDAQ:ARM) delivered a record fiscal second quarter, yet its stock has fallen approximately 11.5% as of noon following yesterday's earnings report.
That's an uncomfortable reaction for a company reporting 27% revenue growth, a 33% increase in adjusted earnings and a 50% surge in licensing revenue.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Why is Wall Street selling?
On paper, the AI growth story remains firmly intact. But investors aren't simply buying visible growth anymore. They're demanding evidence that today's AI spending will translate into sustainable earnings and cash flow.
There seems to be an important disconnect between Arm's operating performance and investor expectations. Second-quarter revenue reached $1.44 billion, while data center royalties doubled year-over-year. Management also raised its optimism, now expecting its new Artificial General Intelligence (AGI) CPU to generate up to $2 billion in cumulative revenue across fiscal 2027 and 2028.

Image source: The Motley Fool.
But here's where the analysis gets interesting. Licensing and other revenue surged 50% to $773 million, but the Annualized Contract Value (ACV), a better indicator of underlying licensing momentum, grew just 12%. Wall Street seems to be focusing on this divergence.
Large licensing agreements can inflate quarterly revenue, but they don't automatically produce recurring royalties. Customers of Arm's proprietary technology must still design, manufacture, and ship chips before Arm collects those payments.
The metric investors must focus on
It's easy for investors to look at the $773 million in licensing revenue and its 50% growth and assume the business is accelerating.
But Annualized Contract Value (ACV) growth of just 12% is disappointing, and that's the metric investors must keep a close eye on. ACV essentially strips out much of the quarterly noise from large licensing agreements, providing a clearer picture of underlying licensing momentum.
The uncomfortable truth is that while reported licensing growth grew 50%, underlying ACV growth actually slowed.
This doesn't mean Arm's business is deteriorating. It means the headline number looks more attractive than the underlying core driver.
The divergence becomes obvious when we put the last three quarters side by side:
| Metric | Q4 FY26 | Q1 FY27 | Q2 FY27 |
|---|---|---|---|
| Licensing revenue | $819 million | $574 million | $773 million |
| YoY growth | +29% | +23% | +50% |
| ACV | $1,660 million | $1,732 million | $1,790 million |
| YoY growth | +22% | +13% | +12% |
The real investment question isn't whether Arm can book another massive licensing quarter. It's whether those customer commitments become production designs, shipped chips, and recurring royalties.
Arm Holdings signed several large licensing agreements and benefited from the timing and accounting treatment of those deals. The resulting revenue hit the income statement immediately, but the underlying annualized contract base didn't expand nearly as quickly.
Meanwhile, customers continue to invest in Arm technology. More than 60 active ATA subscriptions and additional CSS agreements support the longer-term opportunity. But investors should not mistake upfront licensing revenue for guaranteed future royalties.
Here's the operational reality: Arm licenses technology first. Customers spend months designing chips. Manufacturers then produce those chips. Only when production ramps do recurring royalties follow.
Valuation has little room for error
Arm's business is firing on multiple cylinders, but its valuation leaves very little room for disappointment. Even after the recent 11% sell-off, investors are still paying an extraordinary premium for the company's future growth.
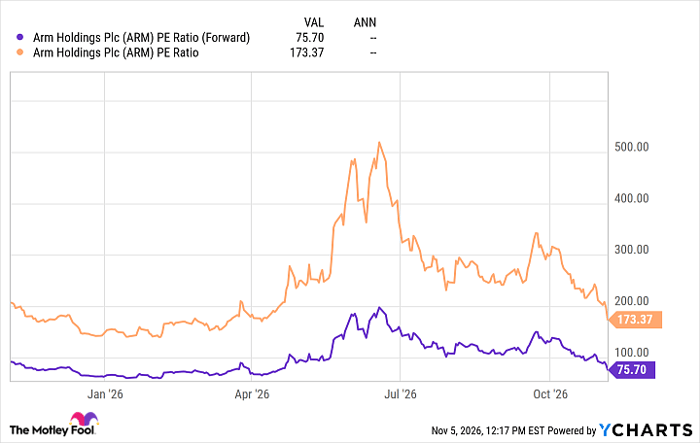
ARM PE Ratio (Forward) data by YCharts.
As of noon, Arm shares trade at approximately 173 times trailing earnings and more than 75 times forward earnings. That kind of valuation is too large and risky to justify.
Such a premium assumes Arm can successfully convert its licensing momentum into recurring royalties, capture a meaningful share of the AI server CPU market, and scale its AGI CPU business without sacrificing profitability. That's a lot of execution already embedded in the share price.
The risks are not hypothetical. Royalty growth of 8% lagged the explosive licensing performance. AGI CPU shipments have yet to ramp materially; initial gross margins are expected to be just 30–40%, and supply-chain constraints remain an obstacle. Meanwhile, competition from AMD and Intel isn't going away.
Is the stock a buy?
ARM is a compelling long-term business, but at this valuation, I don't see much upside anytime soon. I'd rather remain on the sidelines than chase the AI narrative. Today's decline makes the stock cheaper, but not necessarily cheap in the absolute sense.
I'd rather wait for a more attractive entry point or another quarter confirming that licensing commitments are converting into royalties and AGI shipments. AGI is, after all, the next logical step in AI development.
But, at the end of the day, there’s no prize for buying a great company at any price. Arm deserves a place on the watch list, but until valuation catches up with fundamentals, patience may be the better investment strategy.
Should you buy stock in Arm Holdings right now?
Before you buy stock in Arm Holdings, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Arm Holdings wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $358,037!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,229,708!*
Now, it’s worth noting Stock Advisor’s total average return is 897% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 5, 2026.
Isac Simon has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Advanced Micro Devices, Arm Holdings, and Intel. The Motley Fool has a disclosure policy.
Recommended Articles


