


AMD Q3 Data Center Revenue Jumps 97% YoY, Driving 74% EPS Growth; Shares Surge 7% After Hours
TradingKey - On November 3 Eastern Time, AMD (AMD) reported its third-quarter financial results for fiscal year 2026. Data center revenue nearly doubled, driving record revenue for the group, with adjusted earnings per share exceeding market expectations. The company expects revenue growth to accelerate further in the fourth quarter, but free cash flow for the quarter was significantly lower than expected, making the conversion of profit growth into cash flow a key point of focus.
AMD reported revenue of $13.377 billion this quarter, up 45% year-over-year and 16% quarter-over-quarter, beating expectations of $13.080 billion by $297 million, or 2.27%. Non-GAAP diluted earnings per share were $2.09, up 74% year-over-year, exceeding the comparable estimate of $1.97 by $0.12, or 6.09%.
Shares rose over 7% in after-hours trading and were trading at $519.49 as of press time.
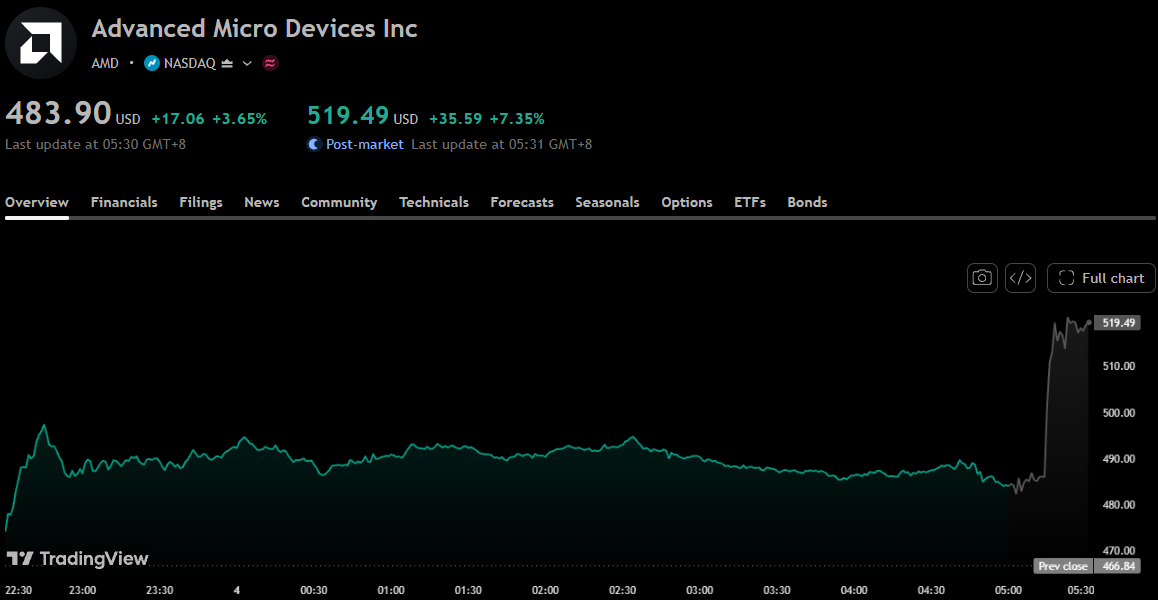
[AMD Stock Price Chart, Source: TradingView]
The Data Center segment continued to serve as the main growth driver, generating $8.546 billion in revenue, up 97% year-over-year, which beat the estimate of $8.200 billion by $346 million, or 4.22%. Segment operating income increased from $1.074 billion in the prior-year period to $2.882 billion. The company attributed the growth to strong demand for EPYC processors and the contribution from the launch of the Instinct MI450 series GPUs.
Performance across other business segments was mixed. Client revenue reached $2.949 billion, up 7% year-over-year, driven primarily by sales of Ryzen mobile processors. Gaming revenue was $773 million, down 40% year-over-year, impacted by lower semi-custom and graphics product revenue. Combined revenue from the Client and Gaming segments was $3.722 billion, down 8% year-over-year, with operating income declining from $867 million to $573 million. Embedded revenue was $1.109 billion, up 29% year-over-year, with growth coming from the aerospace and defense, automotive, communications, and industrial markets, while operating income came in at $453 million.
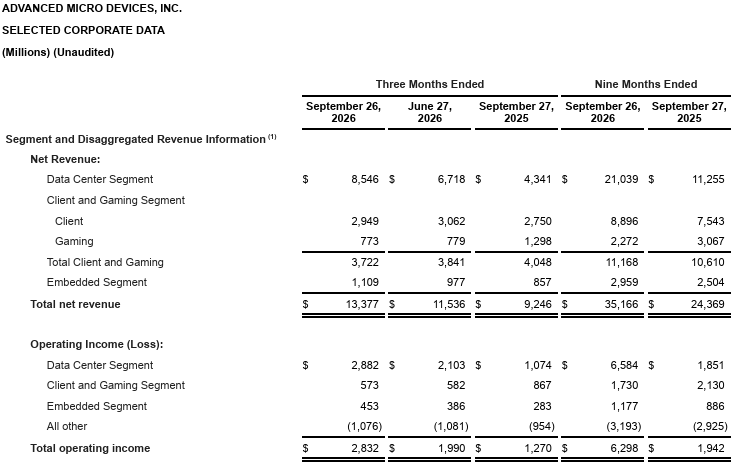
[AMD Revenue by Segment, Source: ADM Q3 Financial Report]
Revenue growth drove an expansion in operating margin. For the quarter, GAAP gross margin was 54%, up 2 percentage points year-over-year. GAAP operating income was $2.832 billion, up 123% year-over-year, with operating margin rising from 14% to 21%. Non-GAAP gross margin was 56%, up 2 percentage points year-over-year and flat quarter-over-quarter. Non-GAAP operating income was $3.923 billion, up 75% year-over-year, with operating margin expanding from 24% to 29%.
GAAP net income was $2.428 billion, up 95% year-over-year, with diluted earnings per share of $1.46. Non-GAAP net income was $3.471 billion, up 77% year-over-year.
Cash flow performance lagged earnings growth. Cash flow from continuing operations for the quarter was $1.202 billion, and capital expenditures were $648 million. Free cash flow, as defined by the company, was $554 million, lower than $1.558 billion in the previous quarter and $1.530 billion in the same period last year; free cash flow margin dropped to 4%, down from 14% in the previous quarter. Compared to market expectations of $1.970 billion, free cash flow was $1.416 billion below expectations, missing estimates by 71.88%. Capital expenditures exceeded the expected $647 million by only $0.01 billion, higher by 0.15%, remaining basically in line with expectations.
Looking ahead to the fourth quarter, the company expects revenue of approximately $17.0 billion, plus or minus 3%, corresponding to a range of $16.490 billion to $17.510 billion. The company disclosed that the midpoint corresponds to year-over-year growth of approximately 66% and quarter-over-quarter growth of approximately 27%. Non-GAAP gross margin is expected to be approximately 55%, lower than 56% in the current quarter.
CEO Lisa Su stated that demand for Instinct and EPYC continues to strengthen, and as production ramps up for Helios and products codenamed "Venice," the company expects growth to accelerate further in the fourth quarter. The earnings report also revealed that Anthropic, Meta, Microsoft, OpenAI, and Oracle Cloud Infrastructure are using the first batch of Helios rack-scale systems to run models and workloads. CFO Jean Hu noted that the scaling of the Data Center business is driving operating leverage across the company.
Recommended Articles


