


SpaceX Is Considering a Merger With Tesla. Here's Why That Would Be a Bad Move.
Key Points
SpaceX and Tesla are exploring a merger.
Tesla's earnings are moving in the wrong direction, but SpaceX may want access to its large cash position.
Both stocks trade at premium valuations, and a merger might just make things messier for investors to analyze.
- 10 stocks we like better than Space Exploration Technologies ›
The final move may be about to unfold. Elon Musk has set plans in motion to potentially merge his two industrial giants: Space Exploration Technologies (NASDAQ: SPCX) and Tesla (NASDAQ: TSLA). A merger has not been formally announced, but each company has formed an independent committee to explore the potential benefits of a merger. It is more likely than not to go through within the next year.
Two trillion-dollar market cap stocks merging would consummate the largest corporate marriage in history. I think it would be a terrible idea. Here's why.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Minimal business overlap
Regardless of what the merger presentation says, there is little overlap between Tesla's and SpaceX's businesses today.
SpaceX has its launch business, connectivity (Starlink), and is investing in artificial intelligence (AI) data centers. It is investing in AI software services like Grok Bot in hopes of carving out a place in the AI race. Tesla sells electric vehicles and battery packs and is working on autonomous driving and humanoid robot technologies.
One might argue that the future Optimus humanoid robot could utilize Starlink to connect to the internet, or that Tesla battery packs could be used at SpaceX AI data centers. However, just because one business can sell a product to another does not mean the two should merge simply because they share the same chief executive officer.
Adding so many product lines under one corporate umbrella is not going to make the two businesses more valuable; it will muddy the waters and confuse any investor trying to decide whether to buy the stock.
Tesla and SpaceX CEO Elon Musk. Image source: Getty Images.
Raiding Tesla's balance sheet for capital spending
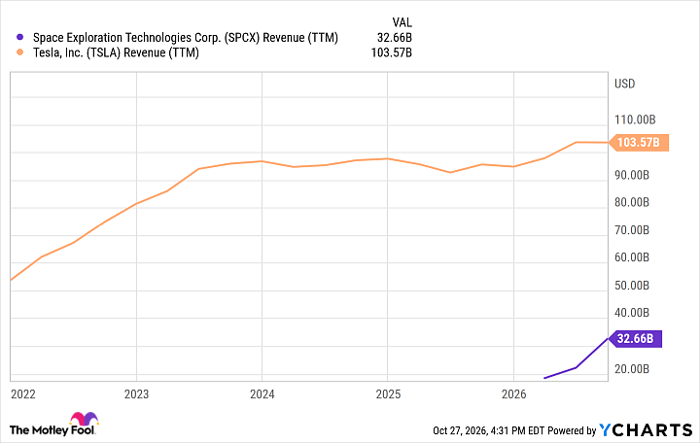
SpaceX's revenue is soaring, posting 161% growth last quarter. Tesla, not so much. Its revenue was little changed year over year, with declining operating earnings, and its revenue has been stagnant for many years. Its earnings before interest and taxes (EBIT) peaked in 2022 and have declined ever since.
So why does Musk want to merge it with SpaceX? It is likely due to the $45 billion in cash on Tesla's balance sheet. SpaceX is in the midst of a huge spending spree on data centers, which is a large cash drain for the business. This is why it did the biggest initial public offering (IPO) earlier this year, raised more debt in recent weeks, and might acquire Tesla.
Last quarter, SpaceX spent nearly $20 billion on capital expenditures, primarily for AI data centers. It plans to double this to $40 billion in Q4. Revenue was only $14.6 billion in Q3. If this level of capital spending continues, Tesla's balance sheet will likely be a good avenue to keep the party going.
The only question is at what price it is acquiring this cash.
SPCX Revenue (TTM) data by YCharts
The valuation math that should concern investors
Today, Tesla has a market cap of $1.6 trillion. For that, investors are buying a $100 billion revenue business with narrowing profit margins, now trading at a price-to-earnings ratio (P/E) of 444. Maybe the electric vehicle business will revive, and maybe the promises made about autonomous driving and the Optimus humanoid robot will lead to explosive growth in the years ahead. Investors should have their doubts that this will occur anytime soon, as Musk has been making imminent promises in automation technology for more than a decade now, with few results.
It is not like SpaceX is a bargain stock, either, even though it is growing rapidly at the moment. With a market cap of about $2 trillion and $33 billion in trailing 12-month revenue, it has a price-to-sales ratio (P/S) of 59, which is one of the highest P/S ratios in the market today. Adding Tesla to the mix just to get its cash does not solve the issue.
Smart investors will avoid buying either stock. A merger will just make this situation messier.
Should you buy stock in Space Exploration Technologies right now?
Before you buy stock in Space Exploration Technologies, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Space Exploration Technologies wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $334,631!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,312,844!*
Now, it’s worth noting Stock Advisor’s total average return is 893% — a market-crushing outperformance compared to 213% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 31, 2026.
Brett Schafer has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Tesla. The Motley Fool has a disclosure policy.
Recommended Articles


