


Is Lockheed Martin a Buy After Its Latest Earnings Report?
Key Points
Management announced a record-breaking backlog of $292 billion.
Management has outlined how existing and future systems can work together to deliver incremental gains.
The company raised its dividend for the 24th consecutive year.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
In an environment where retail investing activity has fallen sharply, aerospace and defense contractor Lockheed Martin (NYSE:LMT) has seen its market value go up nearly 15% at one point since last Thursday's third-quarter results.
Against this backdrop, a double-digit rally following earnings may instinctively prompt investors to anticipate a pullback. However, over a three- to five-year horizon, it could mark the early stages of a longer rally for America's largest defense contractor by revenue.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The general anxiety levels seen today in the stock market and financial media may sound as though doomsday is approaching. In reality, however, the market is far more fractured than the prevailing sentiment suggests. Institutional investors are quietly rotating capital out of overvalued, highly vulnerable sectors and into companies that have greater structural immunity and long-term visibility.

Image source: The Motley Fool.
The most important number: $292 billion
At the core, Lockheed Martin is transitioning from a traditional defense contractor into a faster-moving, integrated defense technology and manufacturing firm. It is expanding production capacity ahead of customer requirements and using long-term contracts to support sustained growth.
Management announced a record-breaking backlog of $292 billion, with nearly a fifth of that amount going into producing missile interceptors under a multi-year contract. For context, over the previous four quarters, backlog has cumulatively grown by 63%, from just $179 billion.
Meanwhile, management has revised free cash flow expectations for 2026 from a midpoint of $6.65 billion at the beginning of this year to $7.9 billion in three quarters.
Why does this matter?
Despite a solid outlook and a 15% gain since last week, Lockheed Martin shares have only returned 29% this year. While that may seem substantial in isolation, particularly given the S&P 500's 12% gain over the same period, it is difficult to argue that the stock has exhausted its upside potential.
For the third quarter, sales grew in all four segments, with Missiles and Fire Control (MFC) leading the way at 24% year-on-year growth. The segment was equally profitable. Despite accounting for less than 22% of total revenue, MFC contributed nearly 29% of total operating profit. Notably, the PAC-3 interceptor leads with a seven-year contract that's cumulatively worth $58.6 billion.
Beyond munitions production, the F-35 aircraft program continues to be a growth engine for the company, having secured a new multiyear contract in the aeronautics segment. On the earnings call, management specifically noted that the aircraft is singularly contributing to expanding profit margins for the company.
A more efficient operating model
Instead of developing individual systems and platforms in isolation, management is outlining how existing and future systems can work together to deliver incremental gains.
Additionally, the company's 1LMX initiative, a model-based engineering and production system, uses digital technology to design, model, and test products before actually investing in physical hardware by using digital twins and digital threads. This creates far greater efficiency and reduces wasted or sunk costs.
Backlog alone may not guarantee profits
Yet backlog isn't the same as profits. These multi-year contracts must still be executed. Moreover, as in any manufacturing business, expansion in actual production depends heavily on suppliers, labor availability, and manufacturing efficiency.
More importantly, investors must keep an eye on margins. While the long-term economics look favorable, Lockheed's ability to consistently deliver top-grade returns depends on whether these contracts get the final go-ahead and whether these operational changes translate into actual free cash flow growth.
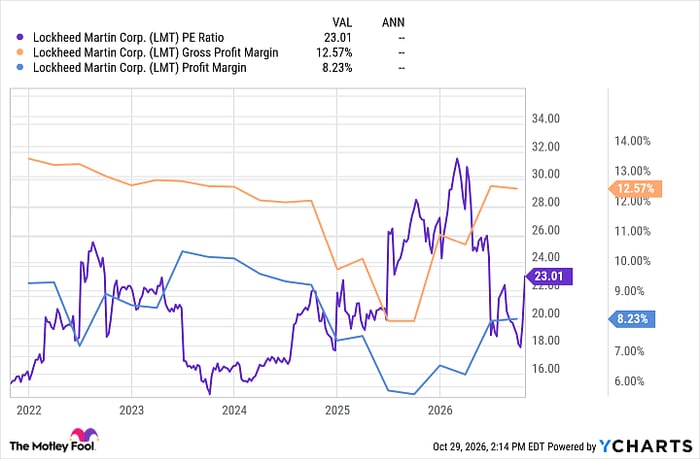
LMT PE Ratio data by YCharts.
Priced like a growth stock
At nearly 23 times trailing price-to-earnings (P/E) ratio, Lockheed Martin stock isn't exactly cheap. For context, Northrop Grumman (NYSE:NOC) stock trades at a more conservative 18 times trailing earnings. It's evident the market is already pricing in a lot of growth by pricing Lockheed higher. However, this doesn't necessarily mean the stock fully reflects its longer-term growth potential.
If you believe defense spending and missile production will remain elevated, and you're comfortable with government-contract and geopolitical risks, Lockheed Martin may be worth looking into.
The 24th consecutive annual dividend raise of $0.15, to $3.60, also makes the stock attractive to dividend investors.
Lockheed Martin has a compelling growth story after last week's third-quarter earnings release. Given today's geopolitical landscape, I'd put this stock on the buy list for long-term exposure to the defense sector. But more importantly, I'd watch for sustained sales growth driving higher profit margins.
Should you buy stock in Lockheed Martin right now?
Before you buy stock in Lockheed Martin, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Lockheed Martin wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $334,308!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,323,413!*
Now, it’s worth noting Stock Advisor’s total average return is 897% — a market-crushing outperformance compared to 213% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 29, 2026.
Isac Simon has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Lockheed Martin and Northrop Grumman. The Motley Fool has a disclosure policy.
Recommended Articles


