


Pound Sterling exhibits firm-footing ahead as traders pare BoE rate cut bets
- The Pound Sterling holds gains near 1.2750 as a slower-than-expected decline in UK inflation weakens the BoE rate-cut case.
- Investors await the UK/US preliminary S&P Global PMI data for May.
- The US Dollar stays firm as the Fed emphasize wait and watch approach on interest rates.
The Pound Sterling (GBP) clings to gains above the crucial support of 1.2700 in Thursday’s London session. The GBP/USD pair remains firm as traders pare bets that were leaned towards the Bank of England (BoE) shifting to policy-normalization in the June meeting after remaining hawkish for more than two years on interest rates.
The expectations favoring the BoE that it will start reducing interest rates from the June meeting have diminished as the Consumer Price Index (CPI) report for April showed that inflation softened at a slower pace than expected.
According to the CPI report, annual headline and core inflation declined to 2.3% and 3.9%, respectively. The inflation measure that dashed hopes of BoE rate cuts in June is the service price index, which declined modestly to 5.9% from the prior reading of 6.0%. UK’s stubborn service inflation has remained a major barrier in the progress of disinflation, which is driven by wage growth.
Daily digest market movers: Pound Sterling remains firm despite upbeat US Dollar
- The Pound Sterling exhibits strength against the US Dollar as investors expect that rate cuts from the BoE will be delayed due to a slower-than-expected decline in the UK inflation for April. Before the June meeting, the BoE will be having one more employment and inflation data, which could strengthen the case of a rate cut if it comes in line with the central bank’s forecasts.
- Meanwhile, investors await the UK preliminary S&P Global/CIPS PMI data for May that will provide cues about nations’ economic health, which will be published at 08:30 GMT. The Manufacturing PMI is forecasted to have improved to 49.5 from 49.1 but will remain the 50.0 thresholds, which separates expansion from contraction. The Services PMI is estimated to have declined to 54.4 from 55.0 in April.
- The Pound Sterling is expected to remain in action on Friday, too, as the UK Office for National Statistics (ONS) will report the Retail Sales data for April. The Retail Sales data represents household spending, which provides significant cues about the inflation outlook. On a month-on-month basis, Retail Sales are estimated to have declined by 0.4% after remaining stagnant last month. Annually, Retail Sales are expected to have contracted by 0.2% against a growth of 0.8% in March.
- On the other side of the Atlantic, the US Dollar holds gains induced by fears that progress in the United States inflation declining towards the 2% target has stalled. The Federal Open Market Committee (FOMC) minutes for the May meeting, released on Wednesday, suggested that the confidence needed for them to consider rate cuts has been dented due to disappointment from recent inflation data.
- Going forward, investors will focus on the preliminary S&P Global PMI for May and the Initial Jobless Claims data for the week ending May 17. For last two weeks, number of individuals claiming jobless benefits have remained more than expected, which have indicated that the labor market strength is easing.
Technical Analysis: Pound Sterling extends winning spree
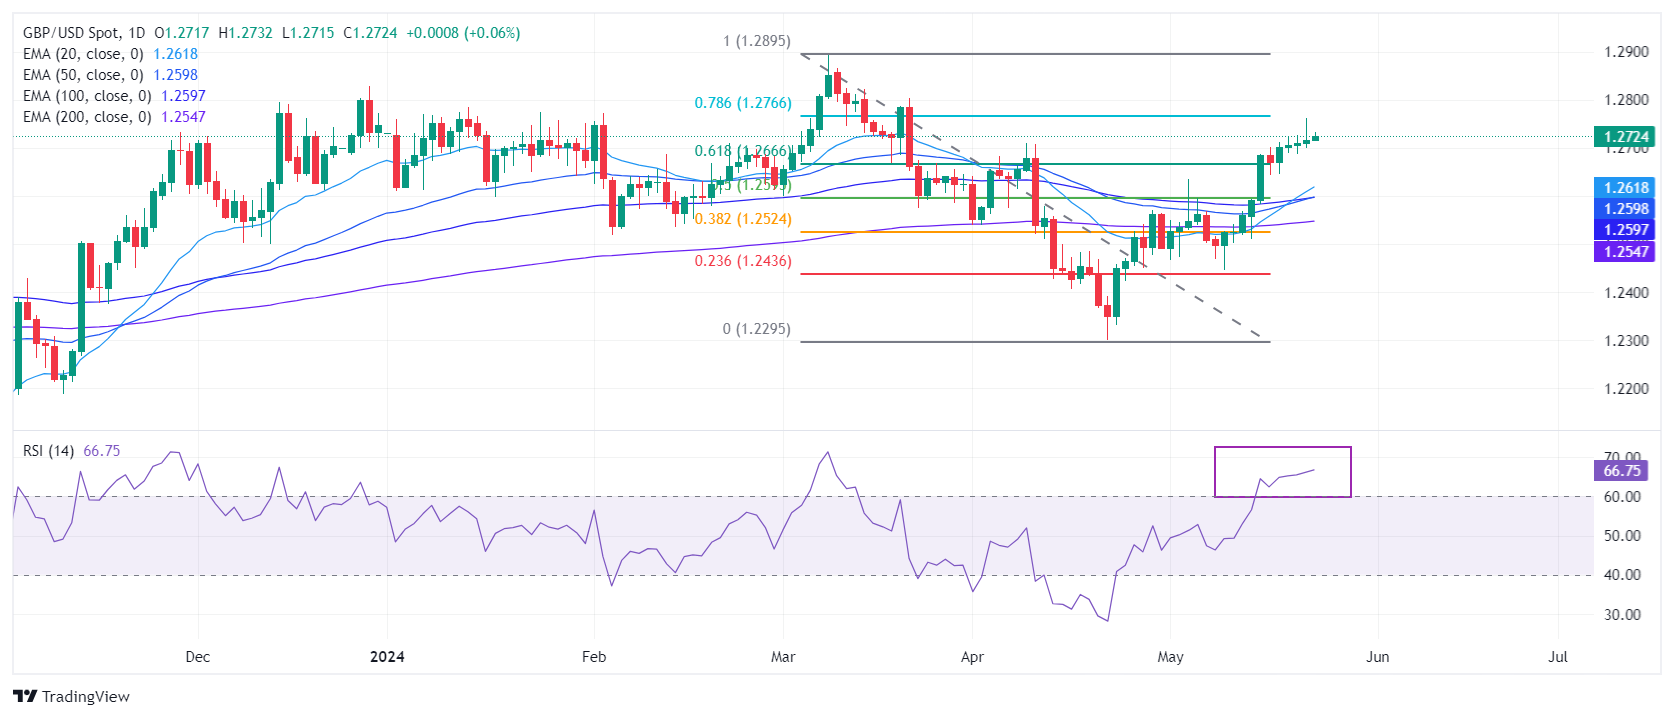
The Pound Sterling extends its winning spell for the fifth trading session on Thursday due to a sharp decline in the BoE rate cut bets for June. The GBP/USD pair has comfortably stabilized above the 61.8% Fibonacci retracement (plotted from the March 8 high of 1.2900 to the April 22 low at 1.2300) at 1.2667.
The Cable is expected to remain in the bullish trajectory as all short-to-long-term Exponential Moving Averages (EMAs) are sloping higher, suggesting a strong uptrend.
The 14-period Relative Strength Index (RSI) has shifted into the bullish range of 60.00-80.00, suggesting that the momentum has leaned toward the upside.
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, aka ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Recommended Articles


