




My Former Hedge Fund Portfolio Manager Just Shorted Berkshire Hathaway and SpaceX. Is It Time to Sell the Stocks?
Key Points
Berkshire stock's valuation has gotten a little pricey.
Could Space Exploration Technologies stock actually be overowned?
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Before becoming a contributing Motley Fool stock market analyst, I worked as a senior equity analyst for a long-short hedge fund for several years. While the fund has since closed, my former portfolio manager, Bill Martin, now runs his own investments and has made a name for himself by correctly predicting the collapse of Silicon Valley Bank in 2023. However, I was surprised to see on the social media platform X that he has decided to short both Berkshire Hathaway (NYSE:BRKB) (NYSE:BRKA) and Space Exploration Technologies (NASDAQ:SPCX).
Berkshire is getting a bit pricey
Berkshire, of course, is the insurance conglomerate that was previously run by famed investor Warren Buffett, who recently stepped down from the company at the start of this year. Buffett is widely regarded as one of the world's best investors and has grown Berkshire into one of the world's largest companies.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
Through his Raging Capital Ventures X account, Martin wrote that he recently bought Berkshire Hathaway B-share March $550 puts for a little over $10 to short the stock. He noted that the out-of-the-money puts were a cheap way to get short a large amount of notional exposure to the name (in other words, he's putting up a relatively small amount of money to take a large short position).
His short thesis is pretty simple: He thinks the stock's valuation looks stretched after a nice rally, while the conglomerate's insurance business is showing signs that it is starting to weaken. He also has not been impressed with Buffett's successor, Greg Abel.
While my former portfolio manager has a strong track record in shorting stocks, I would never recommend it to individual investors, given the risks and the fact that, over time, good stocks tend to move up.
Data by YCharts.
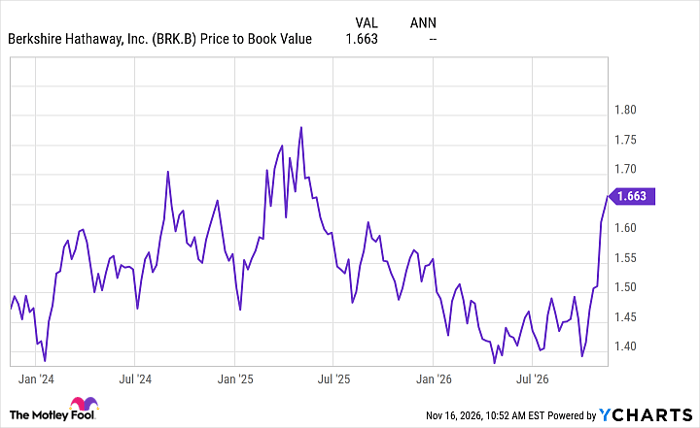
Berkshire's stock has shot up, and its price-to-book (P/B) ratio has risen from around 1.4 earlier this year to 1.6. That's a bit high in my view, but not inconsistent with where the stock has traded in the past three years. Berkshire is often viewed as a market safe haven, especially now, given its still-large cash hoard. As such, while I wouldn't be a buyer at current levels, I think long-term investors can feel comfortable holding the stock.
SpaceX: An overcrowded long
At the same time that he discussed his Berkshire short, Martin also revealed that he was short SpaceX. His short thesis was quite simple. One of the biggest reasons he is bearish on the stock is that he believes SpaceX is already over-owned. He joked that "everyone and their brother" owns the stock, including endowment funds and venture capital firms. The argument here is that without incremental buyers, it becomes difficult for a stock to climb higher.
At the same time, he pointed out how capital-intensive SpaceX's growth initiatives are and how most are aimed at already competitive markets. He also noted how the midterm elections were a big setback for CEO Elon Musk, who poured money into largely losing Republican candidates. This likely won't provide SpaceX with any needed political capital as it pursues ventures that will require government approval.
That last point is particularly poignant, as SpaceX relies heavily on government approvals, environmental and land permits, and federal agency sign-offs. The company's largest growth engine is terrestrial data centers, where the permitting environment is expected to become much tougher. Meanwhile, SpaceX would need FCC approvals to build out a U.S. mobile network, and it needs FAA launch licenses for its space business.
Interestingly, though, an overall slower AI build-out may be good for SpaceX. The company is getting premium pricing for its short-term AI infrastructure rentals, giving it quick payback periods. If overall industry compute capacity grows more slowly than previously expected, this could keep short-term GPU rental prices high to the company's benefit.
While I think SpaceX faces a number of risks that could derail the stock, I think betting against Musk and the company at this stage is also pretty risky.
Should you buy stock in Berkshire Hathaway right now?
Before you buy stock in Berkshire Hathaway, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Berkshire Hathaway wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 17, 2026.
Geoffrey Seiler has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Berkshire Hathaway and Space Exploration Technologies. The Motley Fool has a disclosure policy.
Recommended Articles


