




Weekly Market Wrap: Nvidia Lost Its CEO, but AI Stocks Found New Leaders
US shares snapped a four-week losing streak, but the late-week story was not a broad return to technology. It was a sudden change in AI leadership.
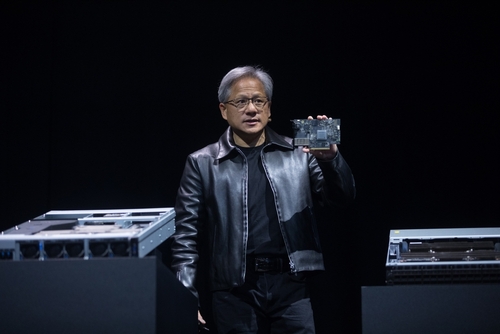
The S&P 500 gained 2.5%, the Nasdaq added 2.3% and the Dow rose 2.1% for the week. Nvidia, however, fell almost 13% after Jensen Huang resigned as chief executive, leaving CFO Colette Kress as interim CEO ahead of one of the company’s most important earnings reports.
The fallout exposed how concentrated the AI trade had become around Nvidia. AMD and Broadcom rose strongly earlier in the week as investors considered which rivals could benefit from a period of uncertainty at the sector’s dominant company, although both gave back ground in Friday’s broader chip sell-off.
Australian shares held up, but only just. The ASX 200 finished 0.2% higher at 9,082.2, with financials offsetting pressure on miners, gold stocks and small caps. The Small Ordinaries fell 1.2%, a more accurate reflection of weakening risk appetite below the largest local companies.
Higher US yields added a second complication. October producer prices rose 6.5% from a year earlier, while the 10-year Treasury yield moved above 5%. That pressure hit gold, property stocks and longer-duration growth shares, even as the broad US indices retained their weekly gains.
The Week in Markets
CFDs allow traders to take a long or short view on global indices and selected shares as earnings, company news and interest-rate expectations change. Stop-loss and take-profit orders can help define risk around major announcements.
“Trade CFDs with an ASIC-regulated broker. Fast AUD funding via PayID. ”
Nvidia’s Leadership Crisis Has Reopened the AI Trade
Jensen Huang’s departure has made Nvidia’s next earnings report much more than a quarterly update on chip sales. Nvidia remains the central supplier to the AI infrastructure boom, but investors now need clarity on succession, customer relationships, product strategy and the company’s ability to maintain its lead without the founder who became the public face of the industry.
The sell-off did not spread evenly across the sector. AMD and Broadcom gained during the week as investors looked at the potential for customers to diversify chip orders and reduce reliance on Nvidia. That does not mean Nvidia’s competitive position has disappeared. Its technology, software ecosystem and supply agreements remain formidable. But the leadership change has created a rare opening for competitors to make a stronger case to investors and customers.
The split also makes the broader AI market more tradeable. Nvidia’s result will shape sentiment, but AMD, Broadcom, Marvell and other infrastructure stocks may not move in the same direction. A strong Nvidia update could stabilize the sector. A cautious outlook or unclear succession message could encourage investors to favor rival chipmakers and less Nvidia-dependent parts of the technology complex.
Nvidia’s shares are now trading at their lowest forward valuation since 2012, according to LSEG data. The fall has made the stock look cheaper, but it also reflects the scale of the uncertainty investors are being asked to absorb before earnings.
Hot Inflation Put Yields Back in the Stock Story
The US market’s weekly gain came despite a less friendly inflation picture. October’s producer-price report was softer than economists expected on a monthly basis, but annual PPI inflation reached 6.5%, its highest reading since November 2022. Treasury yields moved higher, with the 10-year yield holding above 5% and the 30-year yield moving further above 5.4%.
Higher yields are not automatically negative for equities. Banks and some value-oriented shares can benefit from a firmer rate environment, helping explain why the Dow kept pace with the S&P 500 despite the late-week technology weakness.
The pressure is greater on shares priced on earnings far into the future. Technology stocks, A-REITs and small companies tend to be more sensitive when bond yields rise because higher rates reduce the present value investors place on future profit growth.
That divide appeared on the ASX. Financials provided support, while gold fell more than 5% during the week and small caps lagged. Investors were prepared to own profitable large companies, but were less willing to pay up for commodity producers, early-stage growth businesses and interest-rate-sensitive property stocks.
The ASX Held Up, but the Rally Was Narrow
The ASX 200’s 0.2% weekly gain concealed a more cautious market underneath. Financials helped offset weakness in materials, while the Small Ordinaries lost 1.2%. Gold stocks were also under pressure as bullion fell 5.2%, while miners faced weaker copper prices and concern that the global AI pullback could soften demand expectations for industrial metals.
The recent RBA rate rise to 4.85% remains the domestic backdrop. Australian banks may receive some support from higher lending margins, but the trade becomes harder if mortgage stress increases or credit growth slows. Retailers, A-REITs and smaller companies face the opposite challenge, with higher borrowing costs arriving at a time when investors are already becoming more selective.
Oil offered less support than in prior weeks. Brent finished only modestly higher as renewed Middle East attacks and Strait of Hormuz disruption offset earlier hopes that tensions could ease. Energy shares may remain volatile, but the bigger local question is how long financials can cushion the ASX if miners and small caps remain under pressure.
Three Markets to Watch This Week
Nvidia: Can Earnings Steady the AI Trade?
Nvidia reports on Tuesday with more at stake than the usual revenue and guidance numbers. Investors will be looking for reassurance from interim CEO Colette Kress on customer demand, supply agreements, capital allocation and the timetable for appointing a permanent successor.
A strong data-center outlook could stabilize the wider chip sector. Any uncertainty around leadership, product execution or customer financing may keep pressure on the shares and revive the rotation toward AMD, Broadcom and other rivals.
US 30: Can Financials and Industrials Keep Carrying the Broader Market?
The US 30 gained 2.1% during the week as investors favored parts of the market with more immediate earnings and less dependence on AI spending. Higher yields have helped banks and some industrial companies while creating pressure for high-growth technology stocks.
US retail sales, industrial production and major retail earnings will show whether the strength outside Big Tech has a durable economic base. A resilient consumer would support the broader market rotation. Weaker data could pull investors back towards defensives.
Australia 200: Are Banks Strong Enough to Offset Miners and Small Caps?
The Australia 200 has now recorded three consecutive weekly gains, but Friday’s decline showed the index remains vulnerable to offshore technology weakness and rising bond yields.
RBA minutes and wage data will shape expectations for domestic rates after the cash rate reached 4.85%. Banks remain the local cushion, but miners need copper and iron ore to stabilize if the index is to maintain momentum. Further weakness in resources or A-REITs would leave the market increasingly dependent on a small group of large financial stocks.
What Is on the Calendar?
Nvidia’s results will dominate the technology story, but the broader market will also need to absorb higher yields and fresh evidence on consumer spending. The strongest opportunity may sit in the gap between the companies still delivering current earnings and those whose valuations depend on distant AI returns.
Trade the Markets That Matter This Week With Mitrade
The latest week showed that AI stocks are no longer moving as a single group. Nvidia’s leadership crisis hurt the sector’s largest name, while AMD and Broadcom attracted buying interest. At the same time, financials supported the US and Australian indices as higher yields reshaped sector leadership.
Mitrade gives traders access to global indices, commodities, forex and selected shares from one platform. CFDs can be used to take a long or short position as earnings, central-bank policy and market conditions evolve.
Start Trading Global Markets in Three Steps
Nvidia’s report could redraw the AI trade again, while higher yields are creating new winners and losers across global equity markets. Open your Mitrade account today and position for the next major market catalyst.
CFDs are leveraged products and carry a high risk of losing money rapidly. Consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
1. Why did AMD rise while Nvidia fell?
Nvidia’s leadership change raised questions about its future strategy and customer relationships. Some investors moved into AMD and Broadcom on the view that major cloud companies may seek to diversify their chip supply.
2. Why are higher Treasury yields a problem for technology stocks?
Higher yields reduce the present value investors assign to future profits. The effect tends to be greatest for high-growth companies whose valuations depend heavily on earnings expected several years ahead.
3. Why did the ASX 200 rise while small caps fell?
Large financial stocks helped support the ASX 200, while smaller companies remained more exposed to higher borrowing costs and weaker risk appetite. The difference shows that the local market rally has been narrow.
4. Why are Nvidia’s earnings unusually important this quarter?
The report arrives days after Jensen Huang resigned. Investors will want updates on AI-chip demand, the company’s outlook and how interim management plans to handle the leadership transition.
Disclaimer: The content presented above, whether from a third party or not, is considered as general advice only. CFD trading involves significant risk of loss. Past performance does not guarantee future results. This article serves informational purposes only and does not constitute financial advice. Consider your risk tolerance before trading.


