




Alphabet Gets Kicked Out of the $4 Trillion Club After Its Record $505 Billion Drop. Here's What History Says Could Come Next
Key Points
Alphabet just underwent a historic drawdown.
During past sell-offs, it was easier to make the case for buying Alphabet given its strong fundamentals and free cash flow.
Investors who believe in Alphabet’s long-term vision may want to consider buying the stock now.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL) made history for all the wrong reasons on Thursday. It shed a staggering $505 billion in market cap after falling 12.6% in the session.
The sell-off was both the largest nominal loss in Alphabet's history and its largest single-session percentage decline.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Alphabet is now out of the $4 trillion club and was just surpassed by Microsoft for the world's third most valuable company behind Apple and Nvidia.
Here's how Alphabet fared during past sell-offs, why a historically powerful valuation metric no longer applies, and what could come next for the communication services stock.

Image source: Alphabet.
Alphabet's FCF yield has plummeted to 0.6%
Buying Alphabet stock today is far riskier than in the past because much of its future earnings growth depends on its artificial intelligence (AI) investments paying off.
Alphabet is investing in the entire AI stack, from its in-house-built Tensor Processing Unit chips (designed by Broadcom) to its frontier Gemini large language models powered by Google DeepMind to Google Cloud infrastructure to AI use cases at the consumer and enterprise application levels. This is a completely different company from the one that last experienced a steep, prolonged downturn.
Let's take a trip back to 2022, when the Nasdaq Composite (NASDAQINDEX: ^IXIC) fell by 33.1% -- the worst decline since the index fell 40.5% in 2008. At the worst point, on Nov. 3, 2022, Alphabet closed at a split-adjusted $83.43 per share -- marking a 44.3% drawdown from its all-time high. But the price-to-earnings ratio was just 16.6 -- a dirt cheap valuation for such a high-quality company. And even more importantly, Alphabet's free cash flow (FCF) yield was 5.6%.
Similar to how dividend yield is simply the dividend per share divided by the stock price, FCF yield is the FCF per share divided by the stock price. Like dividend yields, FCF yields increase when a stock's price falls or FCF outpaces the growth rate of the stock price. A FCF yield of 5.6% is incredibly strong -- meaning that if Alphabet wanted to, it could theoretically support a 5.6% dividend purely on FCF. Or use that cash to buy back stock, reinvest in the business, or bet big on its best ideas without harming its balance sheet.
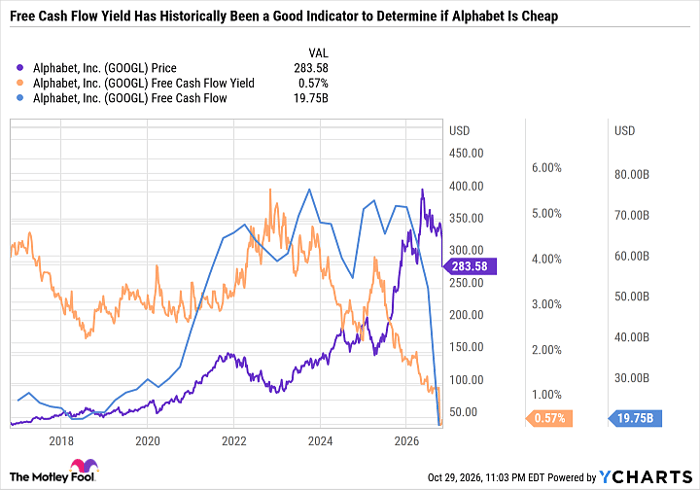
GOOGL data by YCharts
During that 2022 sell-off, Alphabet's FCF yield was at its lowest level in a decade. But as Alphabet began investing heavily in AI, its FCF stagnated and eventually declined sharply. A one-two punch of Alphabet's declining FCF and its rising stock price has taken a sledgehammer to its FCF yield. Given Alphabet's cash burn rate, its FCF yield will likely turn negative in early 2027.
Alphabet is a buy for AI investors
Alphabet used to be a beautifully boring business with multiple high-margin segments and a virtually endless runway for moderate but dependable growth. Alphabet's stock buybacks regularly exceeded its stock-based compensation, bringing down the outstanding share count. And Alphabet even began paying a dividend in 2024 -- reflecting its capital-light business model.
Under that framework, if Alphabet sold off too far, the stock would simply become too cheap to ignore. Like pushing a volleyball underwater, the buoyant force rockets the ball out of the water the second you loosen your grip, which is similar to how sellers can only push an excellent stock down for so long.
The Alphabet of today isn't a submerged volleyball waiting to shoot up. It has a lot more uncertainty. And therefore requires a higher-risk appetite. That may appeal to growth investors, but the days of Alphabet being a high-margin value stock are on hold.
With Alphabet's capex expected to increase in 2027, it's hard to value the company using traditional metrics such as price-to-FCF or price-to-earnings. Therefore, investors who don't have high conviction in Alphabet, or who simply want to wait to see how AI spending pays off, may want to keep it on a watch list for now.
At the same time, investors who believe in Alphabet's ability to convert its long-term investments into future cash flows are getting a compelling opportunity to buy the stock at a much lower price.
Should you buy stock in Alphabet right now?
Before you buy stock in Alphabet, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Alphabet wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $334,793!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,257,420!*
Now, it’s worth noting Stock Advisor’s total average return is 874% — a market-crushing outperformance compared to 209% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 1, 2026.
Daniel Foelber has positions in Broadcom and Nvidia. The Motley Fool has positions in and recommends Alphabet, Apple, Broadcom, Microsoft, and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


