


3 Artificial Intelligence (AI) Stocks to Buy on the Post-Election Dip and Hold for 5 Years
Key Points
Apple’s business could be somewhat insulated from the headwinds facing the AI industry.
Alphabet and Microsoft have diversified businesses beyond their AI segments.
- 10 stocks we like better than Apple ›
The results of the recent U.S. midterm elections have rocked equity markets. Artificial intelligence (AI) stocks are being particularly affected, since voters overwhelmingly adopted measures that could lead to more restrictions on data center expansion. That's bad news for many AI leaders, but despite this setback, my view is that the AI industry will continue to expand over the long run.
Let's consider three stocks that could be great buys following post-election dips: Apple (NASDAQ:AAPL), Alphabet (NASDAQ:GOOG) (NASDAQ:GOOGL), and Microsoft (NASDAQ:MSFT). All three may still beat the market over the next five years. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »

Image source: Getty Images.
1. Apple
Apple operates its own data centers to support its digital services. However, the company hasn't poured nearly as much money into data center construction as some of its similarly sized tech peers racing to meet the massive demand for AI services. What's more, Apple has outsourced some cloud computing workloads to third-party providers. In other words, the company is somewhat less exposed to the risk that increased regulatory scrutiny will lead to a slowdown in the construction of data centers than many of its peers.
Meanwhile, the company's financial results remain pretty strong, as the latest iPhone continues to drive a strong renewal cycle. During Apple's fourth quarter of 2026, for the period ended Sept. 26, Apple reported $114.5 billion in sales, up 12% year over year. Apple has now recorded double-digit sales growth for four consecutive quarters, after spending a long time in single digits.
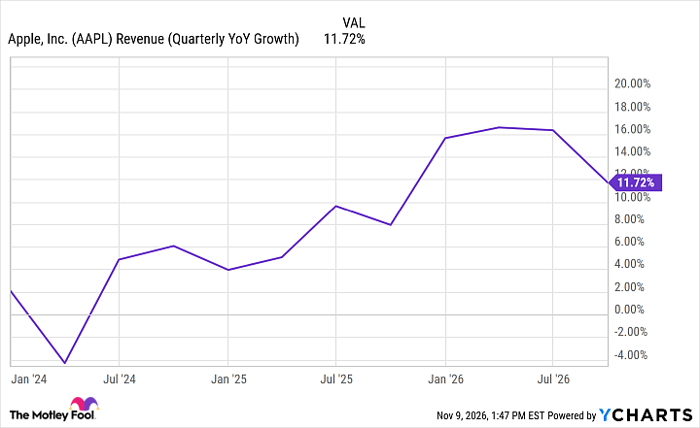
AAPL Revenue (Quarterly YoY Growth) data by YCharts
Apple could continue to perform well over the next year or two, especially as the recently launched iPhone Duo, the company's first foldable smartphone, has been a hit so far. Over the long run, expect Apple to continue expanding its installed base, growing its subscription revenue, and posting consistent revenue and earnings growth.
2. Alphabet
The regulatory impact of the midterm elections could weigh on Alphabet, one of the biggest hyperscalers. The company is pouring significant sums into its AI-related ambitions, so much so that its free cash flow has turned negative in the past two quarters. The tech leader's plans may have to be scaled back if lawmakers crack down on data center expansion.
However, there are several reasons why Alphabet could perform well regardless. Let's discuss three. First, the company has a diversified business. True, cloud and AI have been performing the best in recent quarters, but Alphabet still generates most of its revenue from its advertising business, thanks to its Google search engine and YouTube video-sharing platform, both of which are among the undisputed leaders in these markets.
Second, if there is a halt, or at least a slowdown, in data center construction while demand for the compute capacity new facilities could provide remains strong, it could mean increased pricing power and margins for owners of existing capacity. And few corporations have more available capacity than Alphabet.
Of course, the increased demand and higher prices for existing capacity might not be enough to offset the losses from being unable to expand. But the point is, Alphabet is in a much better position to navigate the uncertainty ahead than it appears at first. And the company's outlook over the next five years remains attractive as it taps into multiple fast-growing industries.
3. Microsoft
Microsoft is in a similar boat. It is one of the biggest hyperscalers and may experience increased demand for existing compute capacity over the next couple of years if regulators impose increased restrictions on the AI industry's expansion plans.
Microsoft is also a fairly diversified company that generates significant revenue from long-term contracts with millions of clients that rely on its software services in their day-to-day activities. The company had $677 billion in commercial remaining performance obligations as of Sept. 30, up 73% year over year.
Microsoft expects to recognize about 30% of that in the next 12 months. Microsoft is well positioned to benefit if the AI industry continues to expand without a hitch, but it is also well equipped to navigate the various headwinds it might encounter. And continued demand for its legacy services could help drive sales and earnings higher either way.
Finally, Microsoft is an excellent dividend stock compared to most of its similarly-sized tech peers. Reinvesting the dividend will help boost returns over the next five years.
Should you buy stock in Apple right now?
Before you buy stock in Apple, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Apple wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $341,157!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,037,753!*
Now, it’s worth noting Stock Advisor’s total average return is 834% — a market-crushing outperformance compared to 207% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 11, 2026.
Prosper Junior Bakiny has positions in Alphabet. The Motley Fool has positions in and recommends Alphabet, Apple, and Microsoft. The Motley Fool has a disclosure policy.
Recommended Articles


