


【US Pre-Market】Google, Marvell Both Fall Over 11%, Lumentum Rises Over 6%; Amazon, Intel to Report Earnings After the Close
TradingKey - In pre-market trading on October 29 ET, futures on the three major U.S. stock indexes weakened across the board. As of press time, Dow futures fell slightly by about 0.08%, S&P 500 futures dropped about 0.28%, and Nasdaq 100 futures slid roughly 1%.
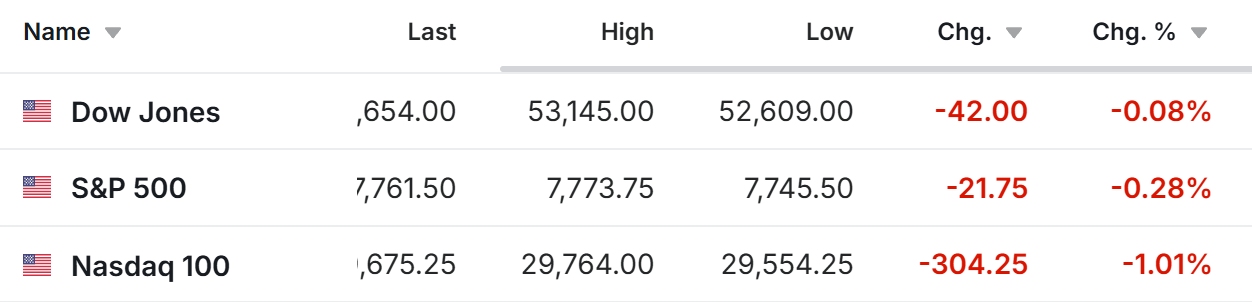
[Source: Investing]
Alphabet (GOOGL) fell short of market expectations, and concerns over cash flow pressure caused by AI infrastructure investments weighed on tech stocks. Meanwhile, Microsoft (MSFT) rose 1.6% on solid cloud business growth and steady cash flow performance.
Investors will also focus on the preliminary reading of U.S. Q3 GDP, September PCE inflation data, as well as post-market earnings reports from Amazon (AMZN) and Intel (INTC).
In commodities, as of press time, Brent crude (UKOIL) was trading at $109.7 per barrel, while WTI crude (USOIL) stood at $101.33 per barrel.
Gold (XAUUSD) was trading at $4,029 per ounce. Bitcoin (BTCUSD) fluctuated around the $80,000 mark, currently trading at $80,174.
Market Moves
Alphabet (GOOGL) fell over 11% in pre-market trading, with earnings and AI investment spending raising concerns.
Alphabet's third-quarter revenue increased 25% year-over-year to $127.6 billion, but fell slightly below market expectations. Google Cloud revenue grew 103% year-over-year to $30.7 billion, reflecting strong demand for cloud services. However, as overall performance failed to meet market expectations, coupled with increased investments in AI infrastructure and cash flow pressure, investors are turning greater focus to whether the company can translate AI demand into sustained revenue and profit growth.
Microsoft (MSFT) rose over 1% in pre-market trading, with Azure growth and cash flow performance drawing attention.
Microsoft's first-fiscal-quarter revenue grew 19% year-over-year to $92.3 billion. On a GAAP basis, diluted earnings per share came in at $4.92; Azure revenue increased 48% year-over-year, and Microsoft Cloud revenue grew 30% to $63.9 billion.
In contrast to Alphabet's stock decline, Microsoft's cloud growth and cash flow performance received a positive market response. Investors will continue to focus on whether Azure's growth can be sustained, as well as the impact of AI-related spending on future profitability and cash flow.
Marvell Technology (MRVL) fell over 11% in pre-market trading, while Lumentum rose on potential acquisition news.
According to Reuters, Marvell is in advanced talks to acquire Lumentum (LITE), a data center optical communication equipment maker. Following the news, Lumentum rose over 6% in pre-market trading, while Marvell fell over 11%.
If a deal is reached, it could further expand Marvell's footprint in optical communications for AI data centers. However, the potential transaction still carries financing and integration risks, with neither party having announced a formal agreement, and the transaction value and final arrangements remaining to be confirmed.
Fortinet (FTNT) fell over 26% in pre-market trading, showing a clear divergence between stock price and financial performance.
Fortinet's third-quarter revenue grew 20% year-over-year to $2.08 billion, product revenue rose 37% to $765 million, and adjusted earnings per share were $0.91. The company also raised its full-year revenue guidance for 2026 and raised its full-year billings guidance for the third time.
Despite reporting revenue growth and raised guidance in the financial report, the stock still tumbled 26%.
ServiceNow (NOW) fell nearly 20% in pre-market trading, dragged down by quarterly profit failing to meet expectations.
ServiceNow's third-quarter total revenue increased 20.5% year-over-year to $4.106 billion, with subscription revenue growing 21% to $3.988 billion. The company raised its full-year outlook for subscription revenue and free cash flow margin, and increased its 2026 AI annual contract value target to $1.7 billion.
Due to quarterly profit missing analysts' expectations and slowing growth in fourth-quarter order guidance, the stock plunged approximately 20% in pre-market trading.
Market News
U.S. Q3 GDP and September PCE inflation data are set for release, with market attention focused on the interest rate outlook.
The U.S. Bureau of Economic Analysis is scheduled to release the preliminary estimate for third-quarter GDP as well as the September Personal Income and Outlays report, which includes the Fed's preferred PCE price index, at 8:30 a.m. ET on October 29.
The GDP data will reflect U.S. economic growth, while the PCE data will help gauge inflation trends. If economic growth remains strong and inflation stays higher than expected, market expectations for rate cuts could be suppressed; if inflation cools, it may ease concerns about rates remaining higher for longer.
The Federal Reserve holds interest rates steady, with future policy remaining data-dependent.
The Federal Reserve concluded its policy meeting on October 28 and kept interest rates unchanged. Moving forward, the market will assess the future rate trajectory in light of inflation, employment, and economic growth data.
As major tech companies increase their investment in AI, changes in interest rates will also affect corporate financing costs and stock valuations. For highly valued tech stocks, the market is focusing not only on earnings growth, but also evaluating whether future profitability can support current valuations.
Amazon and Intel to report earnings after the bell, with cloud computing and semiconductor businesses in focus.
Amazon and Intel are scheduled to report quarterly results after the market close on October 29 ET. Attention will be on Amazon's AWS revenue growth, capital expenditure on AI infrastructure, and e-commerce margins, while Intel will need to disclose its data center performance, product and manufacturing progress, as well as revenue and margin guidance for the next quarter.
Amazon's performance and capital expenditure plans will shape market expectations regarding cloud computing and AI infrastructure demand, while Intel's financial report will provide fresh insights into data center chip demand and the competitive landscape of the semiconductor industry.
Major Events Preview
US Eastern Time | Event |
Oct 29, 8:30 AM | US Q3 advance GDP estimate released |
Oct 29, 8:30 AM | US September personal income and spending report and PCE inflation data released |
Oct 29 after market | Amazon reports quarterly results |
Oct 29 after market | Intel reports Q3 results |
Recommended Articles


