

S&P 500 kicks off 2024 with a bearish tone on Tuesday, slips back towards $4,700

Source Fxstreet
  • Tuesday drew the S&P’s rally to a sharp end as risk appetite reverses direction.
  • Equities were largely dragged lower by poor showings in tech stocks.
  • US data turns red once again, crimping investor confidence.

The Standard & Poor’s (S&P) 500 major equity index closed Tuesday sharply lower after falling just short of making all-time highs in December. Risk appetite reversed course and turned sharply lower to kick off 2024, drawing the S&P’s recent rally to a quick close as investors pulled back on US economic data misses.

US equities closed out 2023 with a stall in the recent stock rally which helped close out the year with firm gains across major indexes, with the S&P etching in a nine-straight-week upside swing before sinking back on Tuesday as overextended market flows pull back.

The S&P 500 declined over half of a percent on Tuesday, closing down 27 points at $4,742.83. The tech-heavy NASDAQ saw the largest losses on the day, slipping over 1.6% to close at $14,765.94, down nearly 250 points. The Dow Jones Industrial Average (DJIA) stumped Tuesday’s risk-off flows, closing marginally flat at $37,715.04, rising a scant 0.07% to close 25.5 points higher.

Tech stocks led the charge down the charts as investors pulled back from tech darling Apple (AAPL), which shed 4% on the day following disappointing demand for their latest products, leading Barclay’s to downgrade their outlook on AAPL.

The US S&P Global Manufacturing PMI missed the mark on Tuesday, declining to a four-month low of 47.9 in December versus the market forecast of a steady print of 48.2. Economic data continues to soften in the US, increasing the risk of a “soft landing” economic scenario that threatens to crimp growth and hobble employment, but the Fed will need a bigger push on the inflation front before rates can start coming down.

Wednesday’s US ISM Manufacturing PMI is expected to improve from 46.7 to 47.1 for December, and markets will be keeping a close eye on the Fed’s latest Meeting Minutes due to publish at 19:00 GMT. Investors will be tearing open the Open Market Committee’s latest minutes to try and draw a bead on how steeply Fed policymakers are leaning towards rate cuts, with some particularly eager market participants anticipating the next rate-cutting cycle to begin as soon as March.

2024’s first trading week will wrap up with US Nonfarm Payrolls (NFP), slated for Friday. December’s NFP is expected to show US jobs additions easing back slightly from 199K to 168K.

NFP watchers will first have to survive the midweek hump, with ISM Manufacturing and the Fed’s latest Meeting Minutes releasing on Wednesday, followed by Thursday’s ADP Employment Change and Initial Jobless Claims for the week ending December 29.

S&P 500 Technical Outlook

Despite Tuesday’s bearish 2024 kickoff, the S&P remains firmly entrenched in bull country, trading within reach of fresh all-time-highs beyond $4,814.68, and it would take an 8% decline before the major equity index even reached the 200-day Simple Moving Average (SMA) near $4,363.

$4,600 remains a key technical barrier, providing a technical floor for any extended downturns with the 50-day SMA rising into $4,500 to provide additional technical support.

S&P 500 Daily Chart
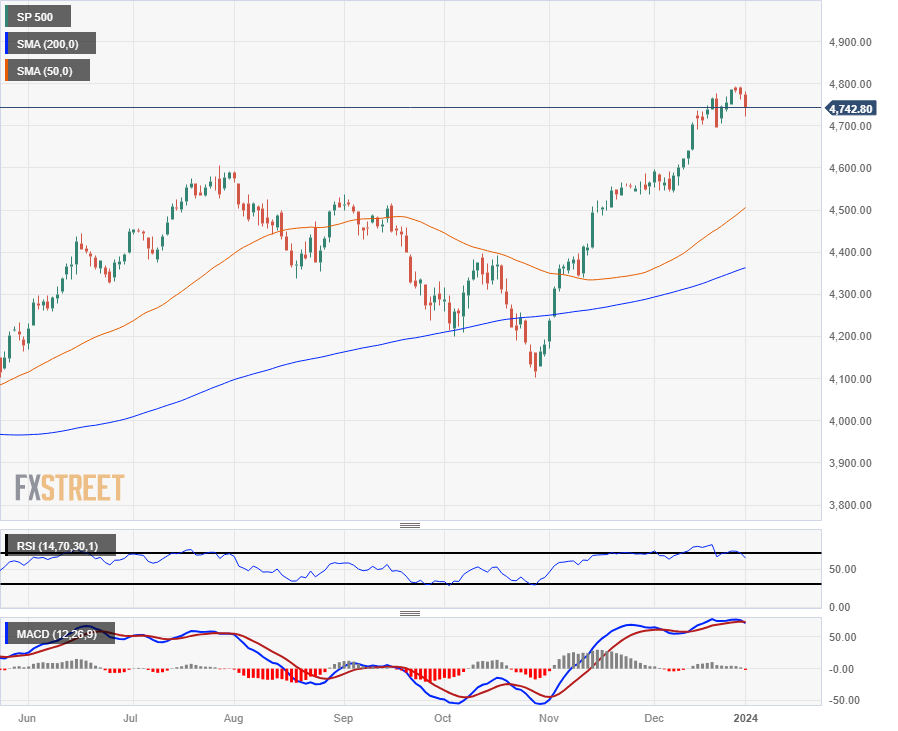
S&P 500 Technical Levels


Disclaimer: For information purposes only. Past performance is not indicative of future results.
placeholder
Gold Price Analysis Today | Forex Gold Analysis | XAU/USD Analysis - November 11, 2026Get the latest gold price analysis, forex gold insights, and XAU/USD analysis for November 11, 2026. Read on for the details.
Author  Mitrade
Nov 11, Wed
Get the latest gold price analysis, forex gold insights, and XAU/USD analysis for November 11, 2026. Read on for the details.
placeholder
Bitcoin lost its 200-day average — but the exit started three sessions before the CPIBitcoin fell 2.5% to about $73,400 on 11 November, an 11-week low, breaking its 200-day moving average near $73,100. The 24-hour liquidation tally reached $632 to $705 million, roughly 82% of it longs. But spot ETF outflows began three sessions earlier and USDT's market cap has shrunk $6.6 billion in 60 days — the leveraged length left before the inflation print did. A double top at 81,890 and 81,080 leaves a measured target of 69,366.
Author  Suzie
Nov 11, Wed
Bitcoin fell 2.5% to about $73,400 on 11 November, an 11-week low, breaking its 200-day moving average near $73,100. The 24-hour liquidation tally reached $632 to $705 million, roughly 82% of it longs. But spot ETF outflows began three sessions earlier and USDT's market cap has shrunk $6.6 billion in 60 days — the leveraged length left before the inflation print did. A double top at 81,890 and 81,080 leaves a measured target of 69,366.
placeholder
Nvidia slid 7.7% after hours while AMD and Broadcom rose — the AI trade changed hands, it didn't breakNvidia closed Wednesday at 173.73, up 2.87%, then fell as much as 8.1% to 159.44 after reports that its board was preparing for a possible leadership change. The same session, the Philadelphia Semiconductor Index rose 5.7% with all 30 components higher, CoreWeave jumped 24.7% on 168% revenue growth, and Micron added 11.9%. If AI demand were being repriced, AMD and Broadcom would not be bid. This is a governance discount on one name, and 204.54 — the 200-day average — is the level that settles it.
Author  Irene Q.
Nov 12, Thu
Nvidia closed Wednesday at 173.73, up 2.87%, then fell as much as 8.1% to 159.44 after reports that its board was preparing for a possible leadership change. The same session, the Philadelphia Semiconductor Index rose 5.7% with all 30 components higher, CoreWeave jumped 24.7% on 168% revenue growth, and Micron added 11.9%. If AI demand were being repriced, AMD and Broadcom would not be bid. This is a governance discount on one name, and 204.54 — the 200-day average — is the level that settles it.
placeholder
Gold hit a one-year low while central banks bought 321 tonnes — the sellers were never the ones you thinkSpot gold closed at 3,876 on Thursday, down 2.8% and its lowest close in more than a year, with an intraday low near 3,852. The dollar is at a 19-month high of 103.21 and the 10-year yield is at 5.10%, so the price move is easy to explain. What is harder to explain is who sold: central banks bought 321 tonnes in Q3, the PBoC added for a 24th straight month, ETF holdings are near a record 4,256 tonnes, and roughly 95% of the futures selling came from non-reportable and sovereign-type accounts rather than hedge funds. This piece separates the two books that have to balance.
Author  Irene Q.
Yesterday 02: 40
Spot gold closed at 3,876 on Thursday, down 2.8% and its lowest close in more than a year, with an intraday low near 3,852. The dollar is at a 19-month high of 103.21 and the 10-year yield is at 5.10%, so the price move is easy to explain. What is harder to explain is who sold: central banks bought 321 tonnes in Q3, the PBoC added for a 24th straight month, ETF holdings are near a record 4,256 tonnes, and roughly 95% of the futures selling came from non-reportable and sovereign-type accounts rather than hedge funds. This piece separates the two books that have to balance.
placeholder
Brent rose 3.3% and US crude stocks built 4.66 million barrels in the same weekBrent January settled at 95.82, up 3.3%, and WTI at 88.74, up 2.55%, after the US signalled it would not pursue a deal with Iran and attacks on Gulf shipping continued. In the same week, EIA data showed US crude inventories rising 4.657 million barrels against expectations of a 1.1 million draw, with gasoline up another 1.799 million. OPEC output also rebounded 1.96 million barrels a day to 27.16 million in October, led by Saudi Arabia at 10.56 million. This piece separates the geopolitical premium from the physical balance and lays out where each side of the trade is anchored.
Author  Irene Q.
Yesterday 03: 06
Brent January settled at 95.82, up 3.3%, and WTI at 88.74, up 2.55%, after the US signalled it would not pursue a deal with Iran and attacks on Gulf shipping continued. In the same week, EIA data showed US crude inventories rising 4.657 million barrels against expectations of a 1.1 million draw, with gasoline up another 1.799 million. OPEC output also rebounded 1.96 million barrels a day to 27.16 million in October, led by Saudi Arabia at 10.56 million. This piece separates the geopolitical premium from the physical balance and lays out where each side of the trade is anchored.
Related Instrument
goTop
quote