ADP Report expected to show a mild rebound in employment in October

Mitrade
coverImg
Source: DepositPhotos
  • The ADP Employment Change report is expected to show a modest improvement in private sector payrolls in October.

  • The ADP report will gain relevance in the absence of other labor market data releases.

  • The US Dollar is trading firm following the Fed’s hawkish pivot last week. 

The Automatic Data Processing (ADP) Research Institute will release its monthly report on private-sector job creation for October on Wednesday. The so-called ADP Employment Change report is expected to show that the United States (US) economy created 24,000 new positions, following a 32,000 net decline in September.

These figures will attract particular interest this month, as the US Government shutdown extends for the fifth week already, and is highly likely to deprive the market and the Federal Reserve (Fed) of the closely watched JOLTS Job Openings and the key Nonfarm Payrolls (NFP) report this week. 

ADP Jobs Report: Employment and the Federal Reserve

The mounting evidence of the US labour market’s deterioration has been a key factor in prompting the Federal Reserve to cut rates by 25 basis points on October 29, and remains a major concern for the dovish members of the Monetary Policy Committee (MPC), which keeps pushing for a more supportive policy.

Against this background, October’s ADP report seems unlikely to give reasons to celebrate. Private sector payrolls are expected to have bounced up, almost fully reverting September’s decline, but still showing numbers consistent with a weak labour market.
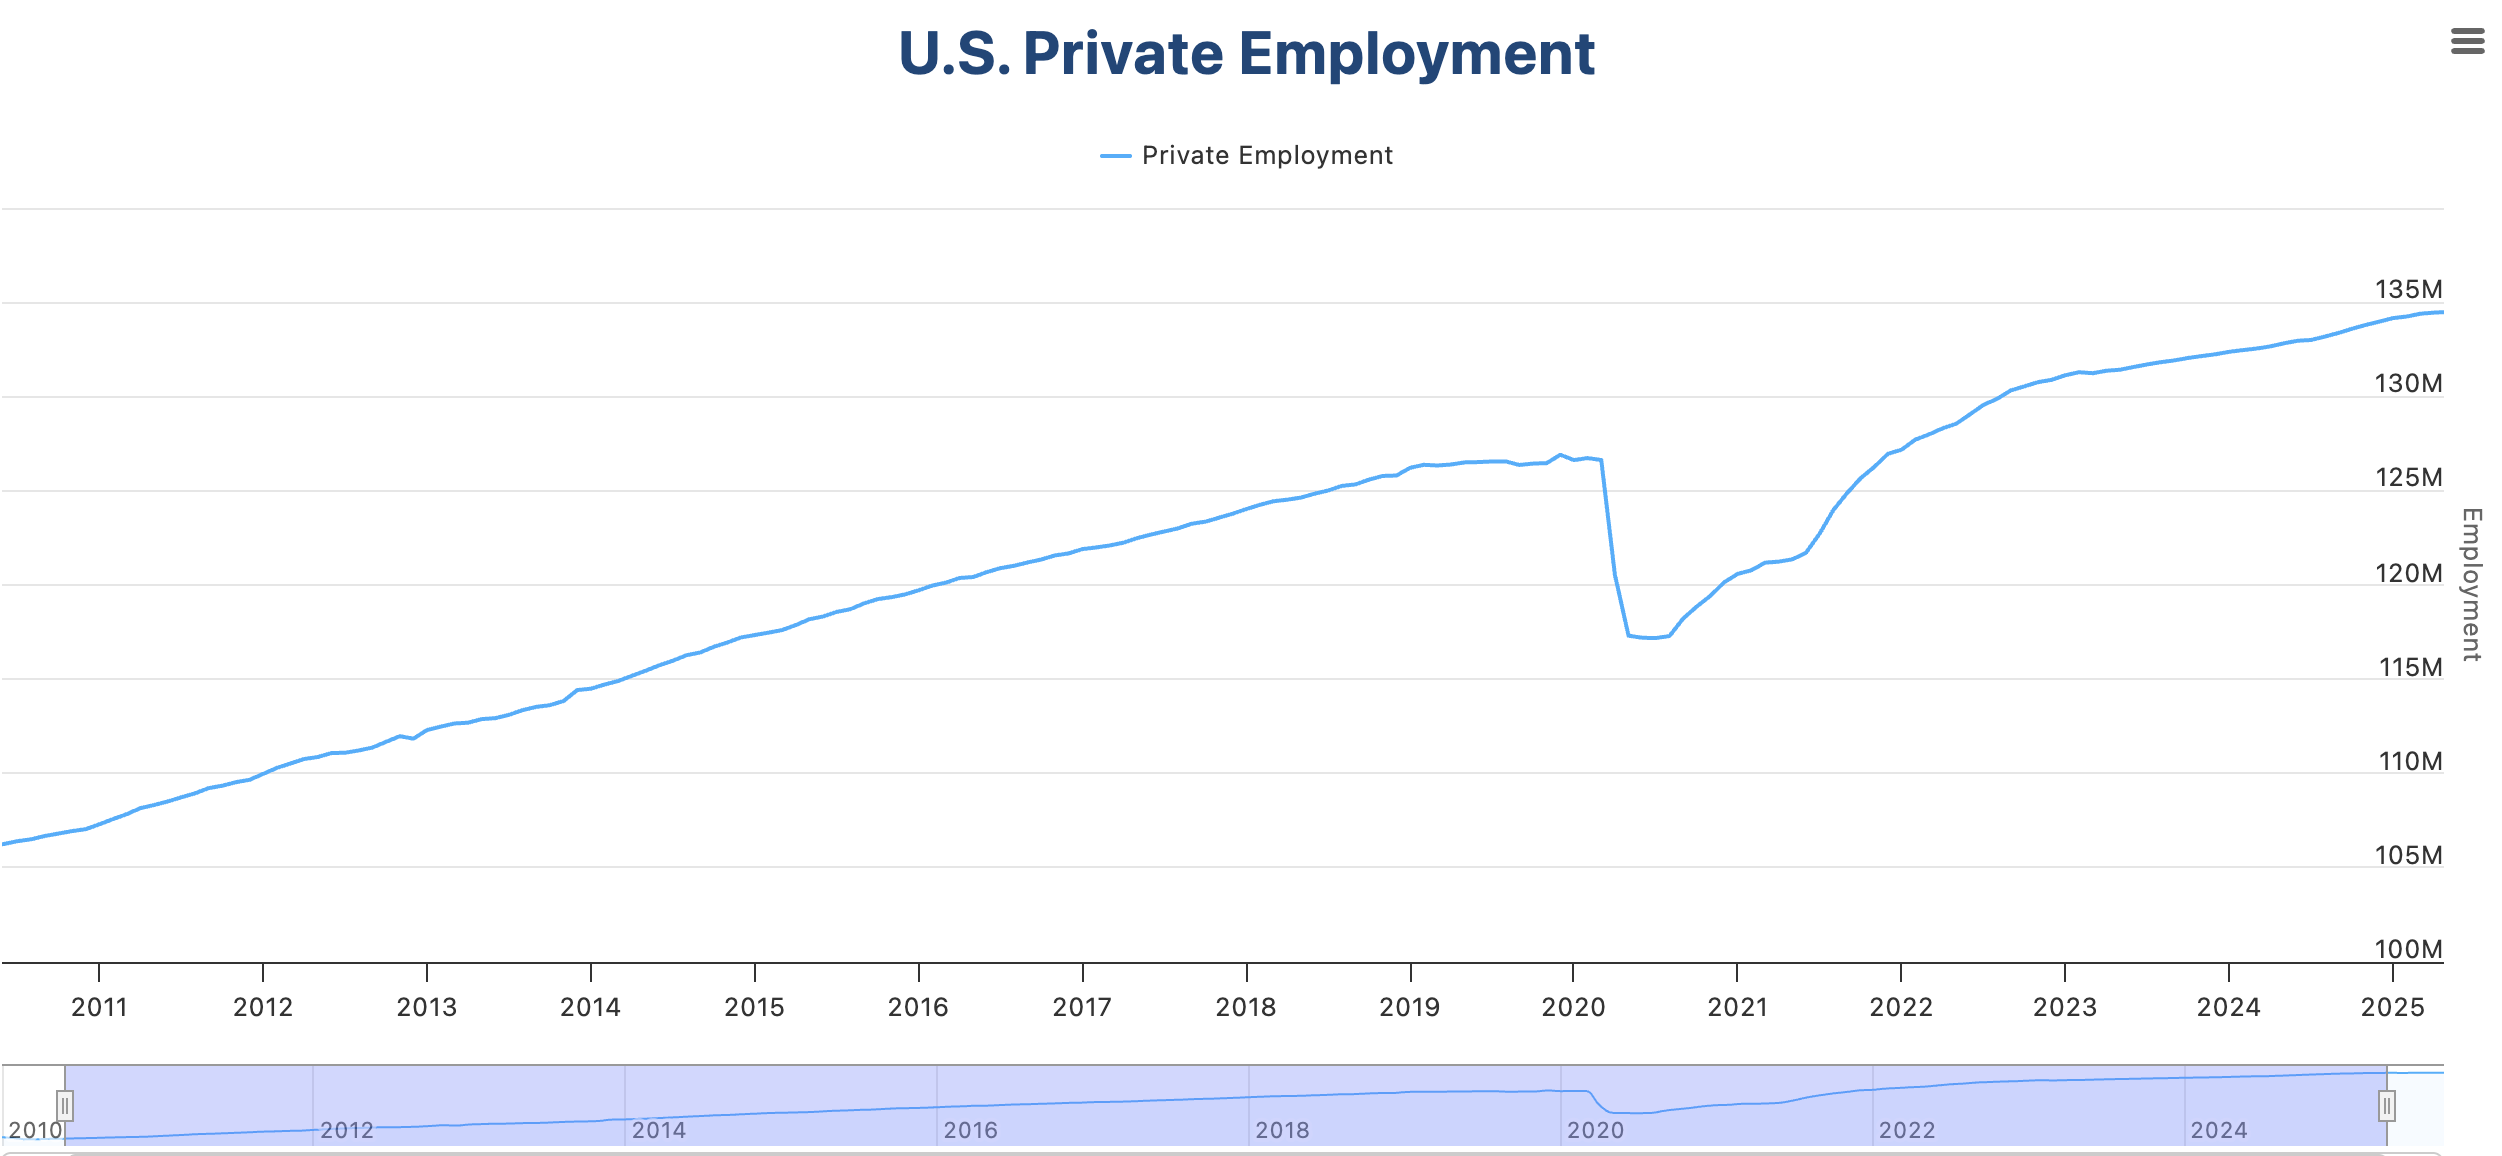
Evolution of US Employment

Preliminary estimates released by ADP last week revealed that net employment showed an average growth of 14,250 jobs in the four weeks ending on October 11, and the market consensus anticipates 24,000 new jobs in October. These figures would partially offset the 32,000 decline witnessed in September, yet they stand at levels well below the 150,000 average new jobs created per month over the last 15 years.

From the monetary policy perspective, the ADP is highly likely to confirm the challenging situation ahead for the Fed, which will have to fine-tune its monetary policy between a weak labor market and higher inflationary risks. This situation has created a wide divergence among policymakers, which was pointed out by Fed Chairman Jerome Powell as the main reason for cooling hopes of further monetary easing in December.

As it stands, chances of a 25 basis points rate cut in December have declined to 64% from above 90% last week. This has been one of the main drivers for the recent US Dollar (USD) recovery. In this case, a strong ADP reading might ease fears about employment and shift the focus back to inflation, endorsing Powell’s hawkish view and providing an additional impulse to the US Dollar.

Another disappointment, on the other hand, and especially if there is a further decline in net jobs, would likely boost pressure on the central bank to keep lowering borrowing costs and, in turn, send the US Dollar lower.

When will the ADP Report be released, and how could it affect the USD Index?

ADP will release the US Employment Change report on Wednesday at 13:15 GMT, and it is expected to show that the private sector added 24,000 new positions in October.

Heading into the release, the US Dollar appreciated against its main peers after the “hawkish cut” delivered by the Federal Reserve last week. The US Dollar Index (DXY) has rallied nearly 1.3% since then, reaching the 100.00 psychological level.
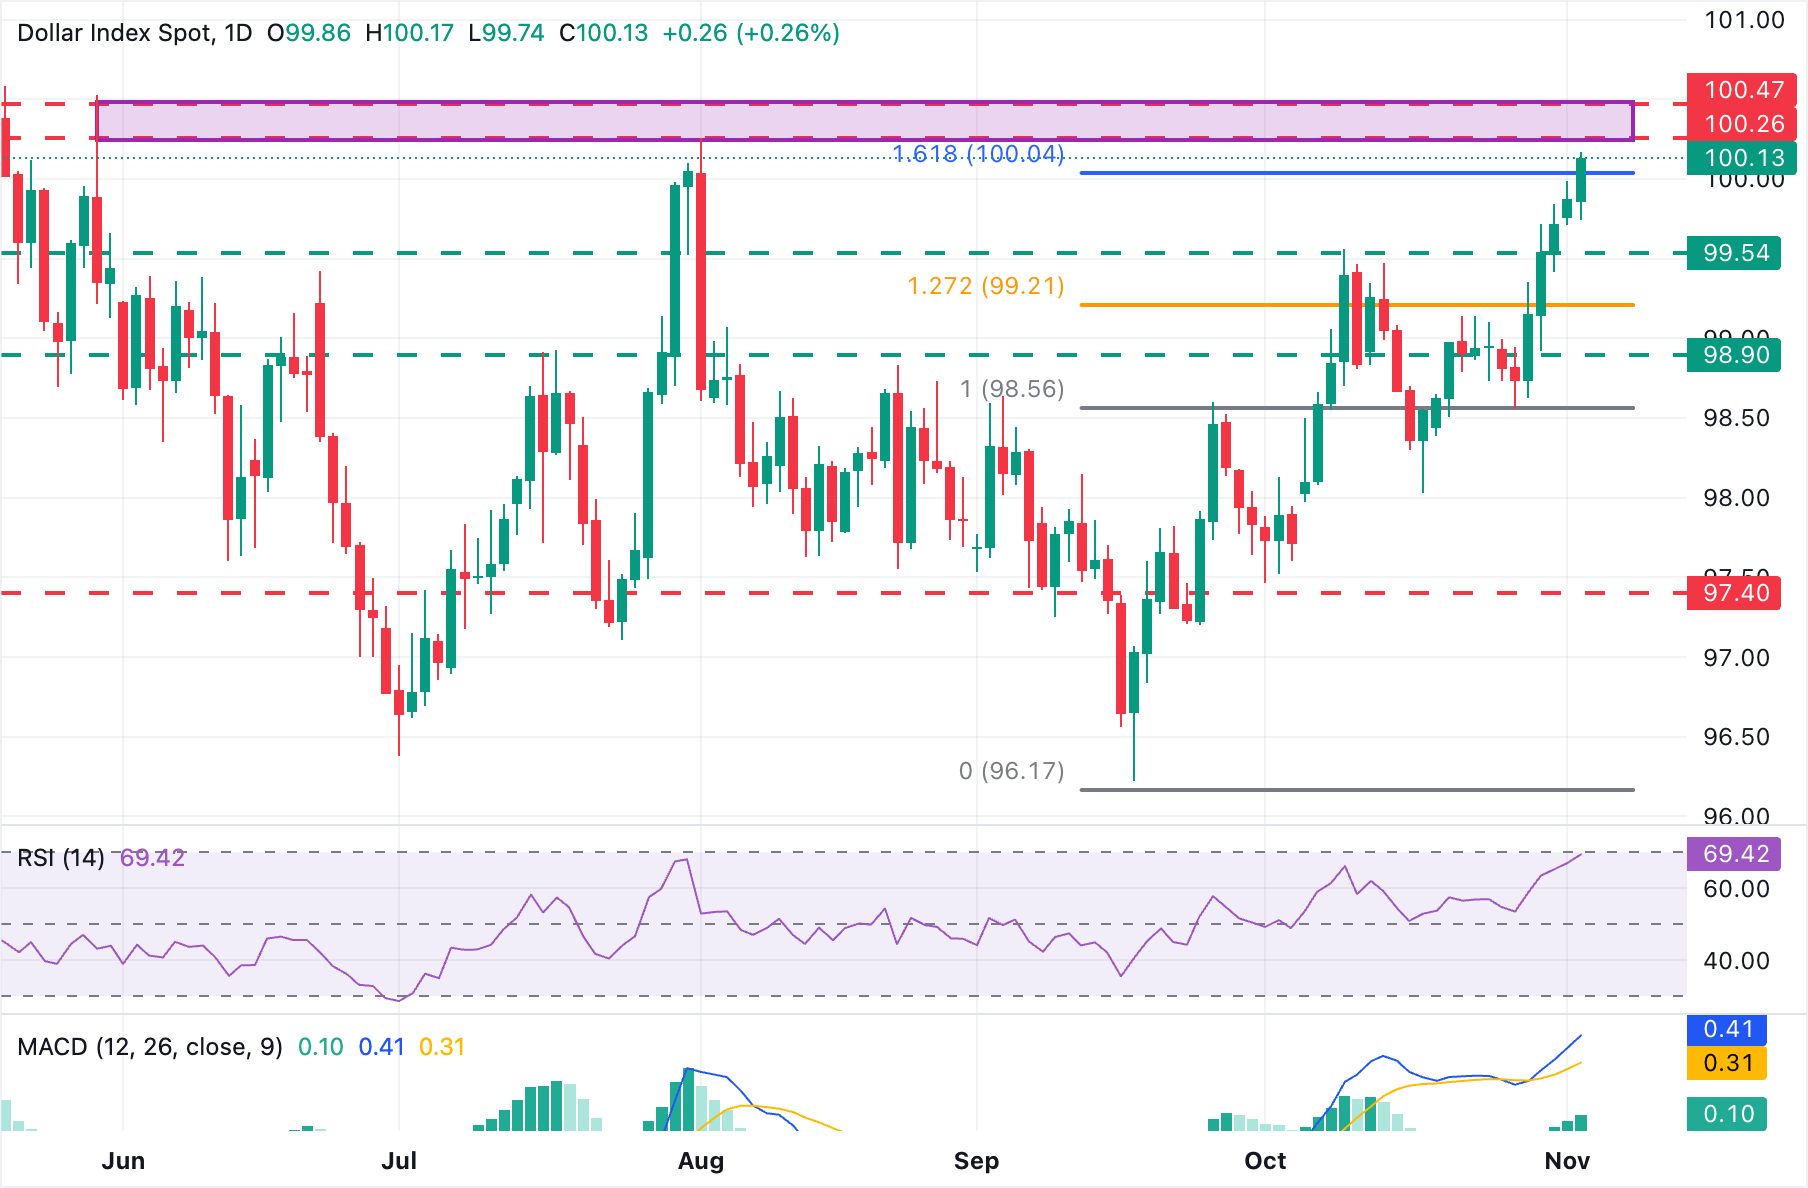
USD Index Chart

From a technical perspective, Guillermo Alcala, Analyst at FXStreet, highlights the resistance area above the 100.00 pshycholkigical level: “The US Dollar Index is on a bullish cycle amid dwindling hopes of Fed interest rate cuts but the Relative Strength Index (RSI) is approaching overbought levels in most timeframes as price action nears an important resistance level between 100.00 and August’s peak, at 100.25. A bearish correction from these levels should be considered.”

Downside attempts, however, are likely to remain limited, says Alcala: “A potential pullback from current levels is likely to find support at the October 9 high near 99.55 or the October 30 low, at the 98.90 area. To the upside, above 100.25, the targets are the May 29 high near 100.55, and the May 16 high, at 101.25.”

Read more

  • Spot Gold Breaches Four Key Levels, Putting $3,500 at Risk as Technicals Enter Oversold Alert Zone
  • * The content presented above, whether from a third party or not, is considered as general advice only.  This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.

    goTop
    quote
    Related Articles
    placeholder
    Core CPI stuck at 0.3% for a third straight month — and BLS couldn't publish the number that would explain itOctober headline CPI rose 0.4% m/m against a 0.3% consensus, and core rose 0.3% for a third consecutive month against 0.2% expected. BLS published no year-on-year figures because October 2025 collection was lost to the government shutdown. Energy cooled to 0.7% from 5.2% — shelter, food and transport services did the rest. The 2-year yield jumped 18 to 21 basis points, the 10-year added 12, and the dollar closed at 102.25.
    Author  Irene Q.
    Nov 11, Wed
    October headline CPI rose 0.4% m/m against a 0.3% consensus, and core rose 0.3% for a third consecutive month against 0.2% expected. BLS published no year-on-year figures because October 2025 collection was lost to the government shutdown. Energy cooled to 0.7% from 5.2% — shelter, food and transport services did the rest. The 2-year yield jumped 18 to 21 basis points, the 10-year added 12, and the dollar closed at 102.25.
    placeholder
    China's factories are pricing in 5.7%. Its shoppers are pricing in 0.7%.China's October PPI rose 5.7% year on year, the fastest since June 2022, while CPI slowed to 0.7% and core CPI to 0.8%. Input prices rose faster than factory-gate prices, squeezing mid-stream margins by roughly five percentage points. The Hang Seng fell 0.13% on a day the S&P 500 rose 2.35%, the only major market to sit out the risk-on session.
    Author  Irene Q.
    Nov 10, Tue
    China's October PPI rose 5.7% year on year, the fastest since June 2022, while CPI slowed to 0.7% and core CPI to 0.8%. Input prices rose faster than factory-gate prices, squeezing mid-stream margins by roughly five percentage points. The Hang Seng fell 0.13% on a day the S&P 500 rose 2.35%, the only major market to sit out the risk-on session.
    placeholder
    The CPI that has no year-over-year number is the one that decides DecemberOctober CPI lands on Nov 10 at 13:30 GMT, and it will be published without a year-over-year figure: BLS never collected October 2025 prices during the federal shutdown. Consensus is +0.3% headline and +0.2% core month-on-month, against +0.6% and +0.3% in September. With December hike odds at 77%, the month-on-month print is now the whole story, and $4,197–4,202 on gold and 4.86% on the 10-year are the levels that price it.
    Author  Irene Q.
    Nov 09, Mon
    October CPI lands on Nov 10 at 13:30 GMT, and it will be published without a year-over-year figure: BLS never collected October 2025 prices during the federal shutdown. Consensus is +0.3% headline and +0.2% core month-on-month, against +0.6% and +0.3% in September. With December hike odds at 77%, the month-on-month print is now the whole story, and $4,197–4,202 on gold and 4.86% on the 10-year are the levels that price it.
    placeholder
    The Fed will sit still on October 28 — but 100 of 100 economists now expect a December hikeA Reuters poll run October 16-20 found 94 of 100 economists expecting the Fed to hold at 3.75-4.00% on October 28 — and all 100 expecting a hike in December, against less than half a month earlier. The market is close to the same price, with CME FedWatch at roughly 17% for October and 82.8% for December. With the Fed in blackout since October 17, here are the five dates that decide the rest of the year, what each one is priced for, and the two directions each can take.
    Author  Irene Q.
    Oct 22, Thu
    A Reuters poll run October 16-20 found 94 of 100 economists expecting the Fed to hold at 3.75-4.00% on October 28 — and all 100 expecting a hike in December, against less than half a month earlier. The market is close to the same price, with CME FedWatch at roughly 17% for October and 82.8% for December. With the Fed in blackout since October 17, here are the five dates that decide the rest of the year, what each one is priced for, and the two directions each can take.
    placeholder
    Housing starts fell to the second-lowest since the pandemic shutdown — with the 10-year at 5.12%, who is left to buy?US housing starts dropped 5.2% to 1.221 million in September, the second-lowest pace since the 2020 pandemic shutdown, and building permits hit a three-and-a-half-year low of 1.400 million. Both figures are worse than they look because July and August were revised up. With the 10-year Treasury at 5.117% — only 19bp below its October 5 peak of 5.311% — and the NAHB builder confidence index at 2012 levels, here are the three numbers, the transmission chain from rates to permits, and the two scenarios into the October 28 FOMC.
    Author  Irene Q.
    Oct 21, Wed
    US housing starts dropped 5.2% to 1.221 million in September, the second-lowest pace since the 2020 pandemic shutdown, and building permits hit a three-and-a-half-year low of 1.400 million. Both figures are worse than they look because July and August were revised up. With the 10-year Treasury at 5.117% — only 19bp below its October 5 peak of 5.311% — and the NAHB builder confidence index at 2012 levels, here are the three numbers, the transmission chain from rates to permits, and the two scenarios into the October 28 FOMC.
    Live Quotes
    Name / SymbolChart% Change / Price
    USDOLLAR-F
    USDOLLAR-F
    0.00%0.00
    XAUUSD
    XAUUSD
    0.00%0.00