The Great Hawkish Pivot: Global Central Banks Push Back Against Rate Cuts
Mitrade
coverImg
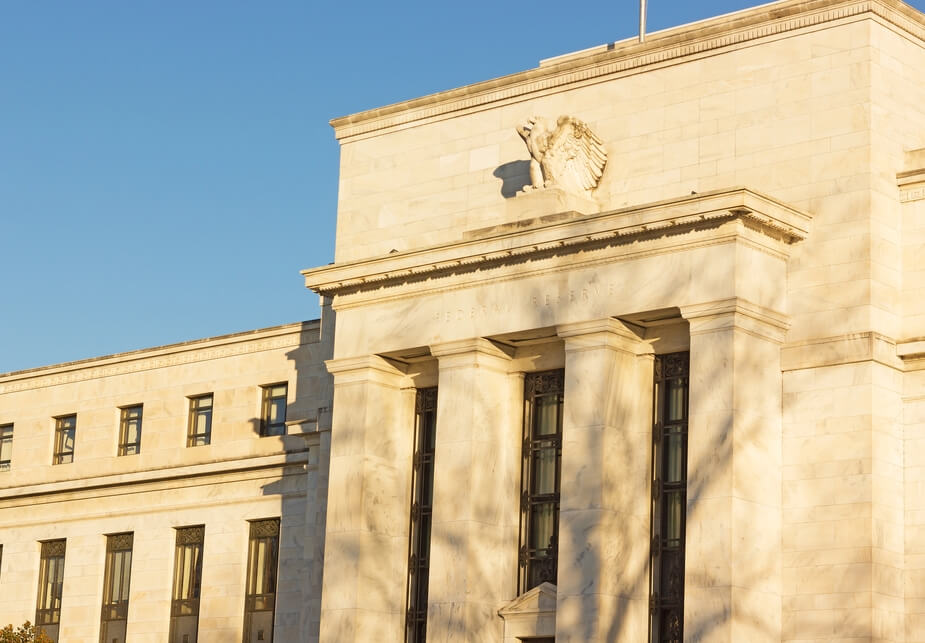
Source: DepositPhotos

TradingKey - With the Federal Reserve’s “hawkish cut,” the European Central Bank (ECB) pausing for a third time, the Bank of Canada signaling the end of easing, and other major central banks turning cautious on rate cuts, global monetary policy may be approaching a turning point. 

As inflation across major economies shows signs of stabilizing near long-term targets, and amid President Donald Trump’s protectionist trade policies, the delicate balance of recent accommodative monetary policies is shifting. The necessity for further rate cuts is now being questioned.

In this week’s round of key central bank decisions, the Fed, Bank of Canada, ECB, and Bank of England all sent more hawkish-than-expected signals about future rate paths. 

Not long ago, the Reserve Bank of Australia (RBA), Norges Bank, Sveriges Riksbank, and Swiss National Bank (SNB) signaled that room for additional cuts is extremely limited.

Pauses and Delays: Fed, BoE, RBA, Norges Bank

The U.S. Federal Reserve, the most watched central bank globally, delivered its second rate cut of 2025 this week — but not without a strong hawkish twist.

One policymaker — Jeffrey Schmid, President of the Kansas City Fed — dissented by voting to hold rates steady, while Governor Stephen Miran pushed for a 50-basis-point cut. This rare two-way split in dissenting votes marks the first such occurrence in six years, highlighting growing internal division.

Chair Jerome Powell added to the hawkish tone, stating bluntly that a further reduction in the policy rate at the December meeting is not a foregone conclusion.

This directly contradicted market expectations and the September dot plot, which pointed to one more 25bp cut in December.

The Bank of England maintained its rate at 4% last month, citing persistent upside risks to medium-term inflation. It emphasized that the path to returning inflation to the 2% target remains uncertain and fragile.

Markets now expect the BoE to hold again in November, with a 60% probability of delaying any cut until December.

The Reserve Bank of Australia also paused in September, expressing concern over higher-than-expected inflation and stressing the need for data-dependent caution. 

The Commonwealth Bank of Australia forecasts no further cuts in 2025, and traders are pricing in a resumption of easing only by February 2026 at the earliest.

Norges Bank cut rates for the second time in three months last month, but Governor Ida Wolden Bache made clear that future rate declines will not be substantial.

Signaling the End of Easing: BoC, ECB, SNB, Riksbank

The Bank of Canada cut rates by 25 bps for the second consecutive meeting. However, despite lowering its growth outlook due to U.S. trade tensions, the bank hinted that the easing cycle may be nearing its end.

The European Central Bank held rates steady for the third consecutive meeting in October, noting that despite uncertainty from U.S. tariffs, the eurozone economy has shown resilience, making current rates appropriate.

Many ECB officials and economists now believe the ECB’s rate-cutting cycle is effectively over. President Christine Lagarde said that current policy rates are in a good place — and they will do what it takes to keep them there.

Market data shows traders now assign only a ~40% chance of another cut before June 2026.

After cutting its policy rate to 0% in June, the Swiss National Bank held steady in September — its first pause since early 2024.

With the Swiss franc appreciating, further cuts could push Switzerland back into negative interest rate territory. But SNB officials warned that reintroducing negative rates would harm financial stability, setting a higher bar for such a move.

Since launching its easing cycle in May 2024, Sveriges Riksbank has cut rates eight times. The central bank now expects to hold rates steady, waiting for clearer signs of economic recovery.

According to its official rate path, Sweden will stop cutting by end-2028. Traders price in less than a 20% chance of further cuts before 2026.

Wild Card: Trump’s Influence

Tom Orlik, Bloomberg economist, noted that central banks’ jobs are getting harder.

He cited:

  • Tariffs potentially hurting growth

  • Political interference in monetary policy

  • Declining data reliability

Together, these factors create greater uncertainty. Orlik expects the Fed to stick to a gradual cutting path, while most other central banks follow suit — unless:

“If President Trump gets his way, the path down for the Fed will be more abrupt, and the cross currents for other central banks fiercer.”

Read more

  • Spot Gold Breaches Four Key Levels, Putting $3,500 at Risk as Technicals Enter Oversold Alert Zone
  • * The content presented above, whether from a third party or not, is considered as general advice only.  This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.

    goTop
    quote
    Related Articles
    placeholder
    Gold hit a one-year low while central banks bought 321 tonnes — the sellers were never the ones you thinkSpot gold closed at 3,876 on Thursday, down 2.8% and its lowest close in more than a year, with an intraday low near 3,852. The dollar is at a 19-month high of 103.21 and the 10-year yield is at 5.10%, so the price move is easy to explain. What is harder to explain is who sold: central banks bought 321 tonnes in Q3, the PBoC added for a 24th straight month, ETF holdings are near a record 4,256 tonnes, and roughly 95% of the futures selling came from non-reportable and sovereign-type accounts rather than hedge funds. This piece separates the two books that have to balance.
    Author  Irene Q.
    Nov 13, Fri
    Spot gold closed at 3,876 on Thursday, down 2.8% and its lowest close in more than a year, with an intraday low near 3,852. The dollar is at a 19-month high of 103.21 and the 10-year yield is at 5.10%, so the price move is easy to explain. What is harder to explain is who sold: central banks bought 321 tonnes in Q3, the PBoC added for a 24th straight month, ETF holdings are near a record 4,256 tonnes, and roughly 95% of the futures selling came from non-reportable and sovereign-type accounts rather than hedge funds. This piece separates the two books that have to balance.
    placeholder
    Core CPI stuck at 0.3% for a third straight month — and BLS couldn't publish the number that would explain itOctober headline CPI rose 0.4% m/m against a 0.3% consensus, and core rose 0.3% for a third consecutive month against 0.2% expected. BLS published no year-on-year figures because October 2025 collection was lost to the government shutdown. Energy cooled to 0.7% from 5.2% — shelter, food and transport services did the rest. The 2-year yield jumped 18 to 21 basis points, the 10-year added 12, and the dollar closed at 102.25.
    Author  Irene Q.
    Nov 11, Wed
    October headline CPI rose 0.4% m/m against a 0.3% consensus, and core rose 0.3% for a third consecutive month against 0.2% expected. BLS published no year-on-year figures because October 2025 collection was lost to the government shutdown. Energy cooled to 0.7% from 5.2% — shelter, food and transport services did the rest. The 2-year yield jumped 18 to 21 basis points, the 10-year added 12, and the dollar closed at 102.25.
    placeholder
    The CPI that has no year-over-year number is the one that decides DecemberOctober CPI lands on Nov 10 at 13:30 GMT, and it will be published without a year-over-year figure: BLS never collected October 2025 prices during the federal shutdown. Consensus is +0.3% headline and +0.2% core month-on-month, against +0.6% and +0.3% in September. With December hike odds at 77%, the month-on-month print is now the whole story, and $4,197–4,202 on gold and 4.86% on the 10-year are the levels that price it.
    Author  Irene Q.
    Nov 09, Mon
    October CPI lands on Nov 10 at 13:30 GMT, and it will be published without a year-over-year figure: BLS never collected October 2025 prices during the federal shutdown. Consensus is +0.3% headline and +0.2% core month-on-month, against +0.6% and +0.3% in September. With December hike odds at 77%, the month-on-month print is now the whole story, and $4,197–4,202 on gold and 4.86% on the 10-year are the levels that price it.
    placeholder
    NAB's 13% profit fall was mostly accounting — the bad-debt line wasn'tNAB's full-year cash earnings fell 13% to A$6.1bn, about 4% below Macquarie's forecast. A A$1.3bn software amortisation charge did most of that; excluding it, earnings were flat at A$7.1bn and the dividend was held at A$1.70. The shares fell as much as 7.9% to A$37.91 before trading 6.19% lower at A$38.62 in Sydney.
    Author  Irene Q.
    Nov 05, Thu
    NAB's full-year cash earnings fell 13% to A$6.1bn, about 4% below Macquarie's forecast. A A$1.3bn software amortisation charge did most of that; excluding it, earnings were flat at A$7.1bn and the dividend was held at A$1.70. The shares fell as much as 7.9% to A$37.91 before trading 6.19% lower at A$38.62 in Sydney.
    placeholder
    The Fed held at 3.75%–4.00% — and two officials voted to hike. December is now 85% pricedThe FOMC held by a 10–2 vote, with Governor Cook and Cleveland Fed President Hammack dissenting for a 25bp hike. Chair Warsh offered no forward guidance and no dot plot, the 2-year yield fell 8bp to 4.70%, and the dollar slipped to 101.84 even as markets moved December hike odds to 85%–87%. Tonight's Q3 GDP and September core PCE are the next referee.
    Author  Irene Q.
    Oct 29, Thu
    The FOMC held by a 10–2 vote, with Governor Cook and Cleveland Fed President Hammack dissenting for a 25bp hike. Chair Warsh offered no forward guidance and no dot plot, the 2-year yield fell 8bp to 4.70%, and the dollar slipped to 101.84 even as markets moved December hike odds to 85%–87%. Tonight's Q3 GDP and September core PCE are the next referee.
    Live Quotes
    Name / SymbolChart% Change / Price
    EURUSD
    EURUSD
    0.00%0.00
    USDCAD
    USDCAD
    0.00%0.00
    GBPUSD
    GBPUSD
    0.00%0.00
    AUDUSD
    AUDUSD
    0.00%0.00
    XAUUSD
    XAUUSD
    0.00%0.00