




Prediction: Amazon Stock Will Skyrocket After Oct. 29 Thanks to AWS Growth
Key Points
AWS growth is starting to accelerate due to huge investment.
Amazon's stock isn't all that expensive.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Amazon (NASDAQ: AMZN) has been a poor stock to own recently. While it rose following its Q2 earnings release, the stock has slowly sold off since then and is now up about 8% for the year, trailing the S&P 500 (SNPINDEX: ^GSPC). However, I think this could all turn around once again after Oct. 29, when Amazon reports Q3 earnings.
The reason is fairly clear, and investors have already seen it cause Amazon's price tag to spike once already this year: cloud computing growth.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: The Motley Fool.
Amazon is the industry leader in cloud computing
Amazon may not be the first name you think of when discussing huge tech companies, but it should be high on the list. While most consumers are familiar with Amazon's commerce site and delivery platform, Amazon Web Services (AWS) really steers the business. In fact, AWS -- which supplies cloud computing -- accounted for 60% of Amazon's operating income in Q2, despite making up only 21% of revenue.
How? AWS's operating margins are far superior to those of its commerce business, which is a notoriously razor-thin-margin industry.
While commerce still affects Amazon's investment picture, investors must realize that Amazon doesn't care much about it right now. Amazon is spending about $220 billion this year to expand its computing infrastructure and fuel AWS growth. It seems content with its current dominance in commerce and sees a major opportunity in cloud computing right now, thanks to booming demand for running AI workloads.
These investments have so far paid off, as AWS's growth rate has significantly climbed over the past few quarters. Rewinding to Q4 2025, AWS's growth was 24% year over year. Then it accelerated to 28% in Q1 2026. Amazon surprised investors by reporting impressive 37% growth in Q2, which caused shares to skyrocket earlier this year before eventually selling off.
If Amazon continues to meaningfully accelerate its AWS growth rate, say to the mid-40% range, it could ignite another run-up in stock price, as it would have a positive effect on Amazon's operating margins. This, in turn, will cause earnings per share to rise faster, which the market will love.
If it can do that, Amazon's stock should be primed to rise, because it's actually pretty reasonably valued right now, at least compared to historical levels.
Amazon's stock isn't that expensive
Valuing Amazon's stock is a bit tricky. While the price-to-earnings (P/E) ratio is the gold standard for valuing stocks like Amazon, it's currently not applicable.
Amazon has been a major investor in private company Anthropic, whose valuation has risen substantially over the past year. Accounting rules require Amazon to report these investment gains as profits, even if it hasn't sold them yet. So, Amazon has a lot of profits on paper, but not as many in real life.
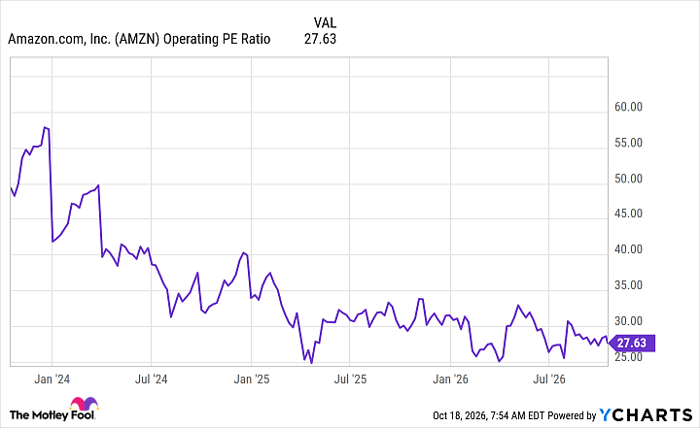
To adjust for this, I value Amazon on its operating income, which is one line item above net income. This metric doesn't account for gains on investment, taxes, depreciation, or other factors that could skew the results. It's just how the business itself is doing. From this standpoint, Amazon's price-to-operating-income ratio has declined substantially over the past few years.
AMZN Operating PE Ratio data by YCharts
While it has been slightly cheaper a handful of times this year, it is still pretty reasonably valued. I think now is the perfect time to load up on shares, as its valuation could increase following strong Q3 results likely be highlighted by impressive AWS growth.
I'm bullish on Amazon's future, and AWS will be the division that takes it to the next level as an investment.
Should you buy stock in Amazon right now?
Before you buy stock in Amazon, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Amazon wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 25, 2026.
Keithen Drury has positions in Amazon. The Motley Fool has positions in and recommends Amazon. The Motley Fool has a disclosure policy.
Recommended Articles


