


You Won't Believe How Wingstop Generated Over 70% of Its Orders Last Quarter
Wingstop (NASDAQ: WING) is riding the popularity of chicken wings as it aggressively expands its restaurant concept. While growth is the name of the game for the company, there's a subtle, but important, trend that's also helping to propel its success. Here's why opening 349 new locations in 2024 was big and, at the same time, not nearly as notable as how 70% of the company's sales originated in the fourth quarter.
Wingstop's growth has been incredible
Before getting to the 70% figure, it is important to highlight just how impressive Wingstop's growth has been. In 2024 it opened 349 locations, which is nearly one new store every day of the year. That's a pretty massive level of activity and it increased the restaurant's store count by nearly 16%.
Where to invest $1,000 right now? Our analyst team just revealed what they believe are the 10 best stocks to buy right now. Learn More »

Image source: Getty Images.
Each new store contributes materially to the top line, which is why it is so important to track such activity. In 2024, Wingstop's sales rose a huge 36% over their 2023 level.
But there is a risk to opening lots of new locations if management lets that effort consume too much of its attention. It isn't uncommon for small, fast growing restaurants to see performance at existing locations fall off. Only that didn't happen at Wingstop, at least not in 2024. Same-store sales, which measures performance at locations open for at least a year, rose nearly 20% in the United States, by far the company's largest market. So not only is Wingstop executing well on its expansion plans, but it is also keeping the core strong.
The future could be bright for two reasons
Wingstop isn't backing down on the growth front. It is expecting to increase its store count by another 14% to 15% in 2025. And while it is calling for same-store sales to drop to the low- to mid-single-digit range, that's more than enough, when combined with new store openings, to keep the company's top line growing at a rapid clip.
The sleeper number from the company's fourth-quarter 2024 financial results, however, was that 70.3% of systemwide sales were digital. "Digital" has many components to it, from the website, to the app, to a kiosk at a store. But there are multiple, and material, benefits to consider here.
From an operations perspective, digital orders don't require a human being to stop and take a manual order. It doesn't require an employee to take payment or make change. Both of those things happen digitally, reducing costs for Wingstop.
From a customer acquisition perspective, Wingstop's reach is far broader than it would be in the physical world. Advertisements, flyers, and locations are all limited in their reach. The internet in particular can reach people that other forms of advertising would never touch.
From a customer relationship perspective, any purchase from the web or the app is more valuable than a customer who just walks into a Wingstop and buys some food. Simply put, Wingstop can reach out to digital customers more easily to entice them to come back in with deals.
Going digital can be a powerful tool for a company and Wingstop has clearly both embraced this fact and excelled with regard to its digital execution. The company's digital strength doesn't change the fact that it needs to keep customers interested in chicken wings. If fickle consumers move on to a different type of food Wingstop's business will suffer. There's no way around that.
However, having a strong digital presence can help the company support its same-store sales as it continues to aggressively open new locations. That will be particularly important if broader demand for eating out comes under pressure. Which is exactly the environment that appears to be unfolding in the restaurant industry in the first quarter of 2025.
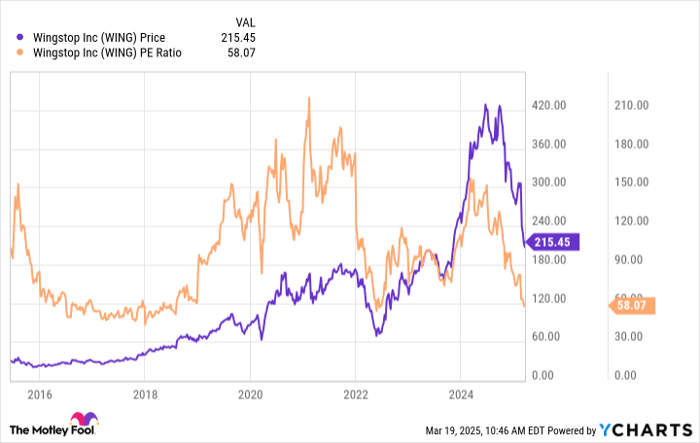
WING data by YCharts
Wingstop's stock has come back down
Wingstop is not a stock that a value investor will find attractive because the price-to-earnings ratio of 57 is high on an absolute basis. But that P/E is actually toward the low end of its historical range, so more aggressive and growth-minded investors might want to take a look at the shares.
The company's strong growth in 2024 and its plans for more store growth in 2025 are key reasons to be interested. But don't forget about the 70% of sales that are digital. Those sales save money, increase the reach of its brand, and create a customer relationship that can help drive future sales. Add that to the store expansion and it looks like Wingstop has its ducks lined up for a continuation of its strong recent business performance.
Don’t miss this second chance at a potentially lucrative opportunity
Ever feel like you missed the boat in buying the most successful stocks? Then you’ll want to hear this.
On rare occasions, our expert team of analysts issues a “Double Down” stock recommendation for companies that they think are about to pop. If you’re worried you’ve already missed your chance to invest, now is the best time to buy before it’s too late. And the numbers speak for themselves:
- Nvidia: if you invested $1,000 when we doubled down in 2009, you’d have $305,226!*
- Apple: if you invested $1,000 when we doubled down in 2008, you’d have $41,382!*
- Netflix: if you invested $1,000 when we doubled down in 2004, you’d have $517,876!*
Right now, we’re issuing “Double Down” alerts for three incredible companies, and there may not be another chance like this anytime soon.
Continue »
*Stock Advisor returns as of March 24, 2025
Reuben Gregg Brewer has no position in any of the stocks mentioned. The Motley Fool recommends Wingstop. The Motley Fool has a disclosure policy.
Recommended Articles


