


US Dollar hovers around 10-week high as markets rebuff aggressive Fed rate cuts
- The US Dollar hits several important levels against most major G10 currencies.
- Markets brace for three Fed speakers lined up to speak.
- The US Dollar Index orbits broke above important upside levels, though struggles to move higher.
The US Dollar (USD) broadly consolidates on Tuesday after reaching a 10-week high on Monday, fuelled by investors’ views that the Federal Reserve won’t cut interest rates as quickly and aggressively as previously expected. Moreover, markets seem to be betting on a possible win for former President Donald Trump in the November 5 presidential election after several betting websites and polls showed the Republican nominee starting to lead.
The US economic calendar is again rather light on Tuesday. Besides the NY Empire State Manufacturing Index for October, there is not much with the potential to thrill markets. Rather look for some moves coming from the three Fed officials that are scheduled to speak.
Daily digest market movers: Fed speakers have their work cut out
- At 12:30 GMT, the NY Empire State Manufacturing Index for October is due. Economists expect it to fall to 2.3 from 11.5 previously.
- At 15:30 GMT, Federal Reserve Bank of San Francisco President Mary Daly delivers keynote remarks and participates in a moderated conversation and an audience Q&A in an event hosted by NYU Stern School of Business.
- Around 17:00 GMT, Federal Reserve Governor Adriana Kugler participates in a webcast about career opportunities and diversity in Economics.
- Federal Reserve Bank of Atlanta President Raphael Bostic will close off this trading day with comments while participating in a moderated conversation at the Gathering Spot on how the economy affects small businesses near 23:00 GMT.
- Equities are all over the place, with Chinese stocks having closed substantially lower, while Japan was up on the day. European equities look sluggish while US futures are rather flat.
- The CME Fed rate expectation for the meeting on November 7 shows an 86.8% probability of a 25 basis point rate cut, while the remaining 13.2% is pricing in no rate cut. Chances for a 50 bps rate cut have been fully priced out.
- The US 10-year benchmark rate is trading at 4.07%, a touch softer than the high from last week at 4.11% on Thursday.
US Dollar Index Technical Analysis: Careful now!
The US Dollar Index (DXY) is facing some resistance with a second false break and rejection at the 100-day Simple Moving Average (SMA) at 103.23. The risk is that, with the second rejection, the DXY sees sellers coming in and defend that 100-day SMA. A broad fade in search of support could play out with a return to 101.90 as first pivotal support level.
The first resistance level at 103.18 is under pressure, with the DXY trading around it for a second day in a row. Once above there, a very choppy area emerges, with the mentioned 100-day Simple Moving Average (SMA) at 103.23, the 200-day SMA at 103.78, and the pivotal 103.99-104.00 levels.
On the downside, the 55-day SMA at 101.90 is the first line of defence, backed by the 102.00 round level to catch any bearish pressure and trigger a bounce. If that level does not work out, 100.62 also acts as support, which was the low of December 28th 2023. Further down, a test of the year-to-date low of 100.16 should take place before more downside. Finally, and that means giving up the big 100.00 level, the July 14, 2023, low at 99.58 comes into play.
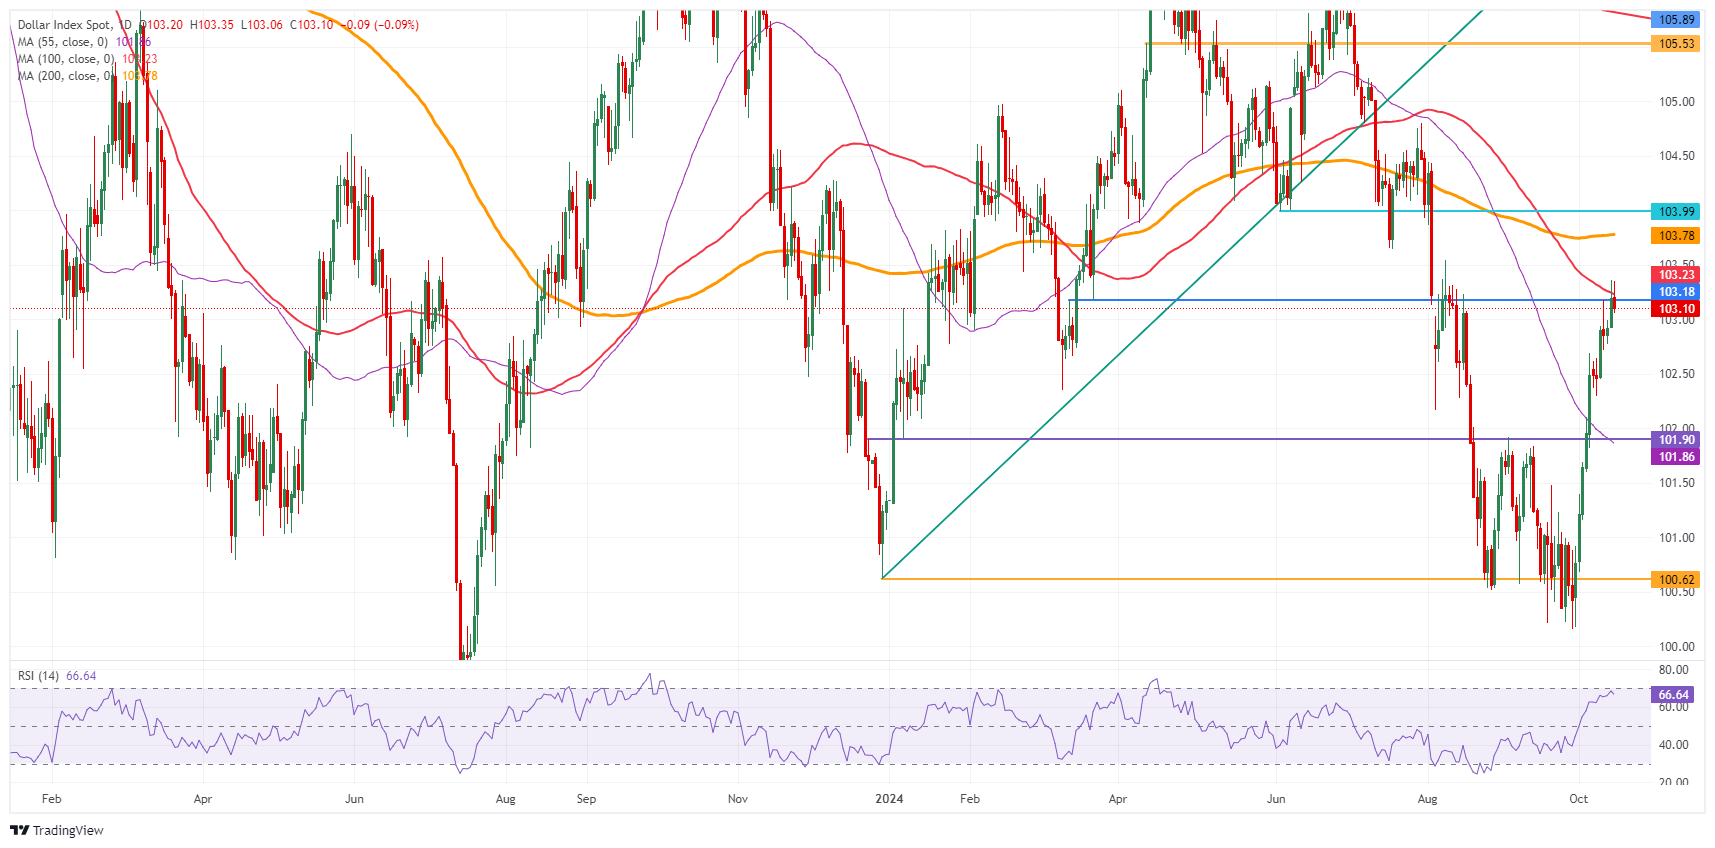
US Dollar Index: Daily Chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Recommended Articles


