




Not Micron. Not Broadcom. This Artificial Intelligence (AI) Stock Will Skyrocket in December After the Latest Sell-Off
Key Points
Shares of Ciena have declined sharply over the past three months, presenting investors with a terrific buying opportunity.
Ciena's earnings are growing at a phenomenal pace, driven by tight supply conditions in the optical networking market.
Ciena's stock could jump more than 2x over the next two years.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
The recent sell-off in the semiconductor sector has weighed heavily on shares of Micron Technology and Broadcom.
While Micron has lost 26% of its value over the past three months, Broadcom stock has dropped 15%. The PHLX Semiconductor Sector index, for comparison, is down 23% over the same period. Both companies will be looking to win back investor confidence when they release their quarterly results in December.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Broadcom will release its fiscal 2026 results on Dec. 9, while Micron is expected to report results later next month. I won't be surprised to see both semiconductor stocks deliver stronger-than-expected results and provide healthy guidance, as they are benefiting from bottlenecks in the artificial intelligence (AI) infrastructure space.
However, there is another AI infrastructure company -- Ciena (NYSE:CIEN) -- which will release its quarterly results on Dec. 10, and its shares could get a nice shot in the arm following its report. Let's see why that's likely to be the case.

Image source: Getty Images.
Ciena is capitalizing on the next big bottleneck in AI
It is well known that a scarce memory supply has been a tailwind for Micron. Meanwhile, Broadcom has benefited from the shift to custom AI processors in data centers and from the need for fast networking chips. The demand for Broadcom's chips has been exceeding supply, driving solid growth in its revenue and earnings.
Similarly, Ciena has been delivering phenomenal growth on the back of strong demand for optical networking components in AI data centers. The company expects $1.75 billion in revenue in the fourth quarter of fiscal 2026, implying a 30% increase over the prior year. Even better, it predicts non-GAAP operating margin climbing to 20% from 13.2% in the year-ago period. As a result, analysts are forecasting a 128% increase in Ciena's earnings per share for fiscal Q4.
The substantial uptick in Ciena's margins is attributable to "an extraordinary industry demand environment" that's exceeding supply. Healthy demand and the accompanying supply constraint are pushing up prices for Ciena's optical networking components. Importantly, Ciena expects strong demand for optical networking to drive up its margins over the next three years.
At its investor forum held in September this year, the company pointed out that its addressable market will increase at a 24% compound annual growth rate (CAGR) between 2026 and 2029, reaching $52 billion after three years. Ciena, meanwhile, is predicting a 30% revenue CAGR over this period, suggesting it is on track to outpace the broader market's growth.
More importantly, the company estimates that its operating margin will jump to a 25%-27% range in fiscal 2027 and then increase to 32%-35% in 2029. For comparison, Ciena's operating margin was 22.5% in the third quarter of fiscal 2026. However, I won't be surprised if Ciena's growth exceeds its own expectations, as demand for optical networking is poised to take off.
Ciena is receiving far more orders than it can fulfill, as evidenced by its book-to-bill ratio of "significantly greater than 1." In fact, management noted on Ciena's September earnings call that its order inflow in the first month of fiscal Q4 was approaching the orders it booked in entirety of Q3.
As a result, Ciena expects to end fiscal 2026 with more than $10 billion in backlog. The company anticipates its top line to increase by more than 30% in fiscal 2027 to $8.3 billion to $8.4 billion. However, it could do better than that as the optical networking market's revenue could jump by more than 10x between 2026 and 2028, according to Goldman Sachs, reaching $154 billion in 2028.
Now is the right time to buy this AI stock
Ciena stock has lost almost 40% of its value over the past three months. It trades at 25 times forward earnings, which is quite attractive for a company whose earnings per share (EPS) are predicted to jump substantially over the long run.
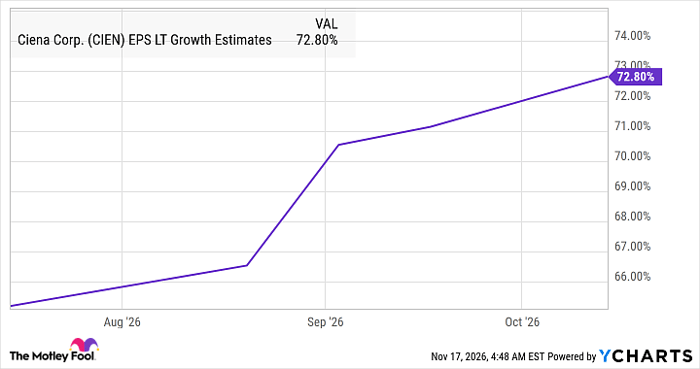
CIEN EPS LT Growth Estimates data by YCharts
Ciena is expected to deliver $7.17 in EPS for the recently concluded fiscal 2026. Its bottom line could more than double over the next two years.
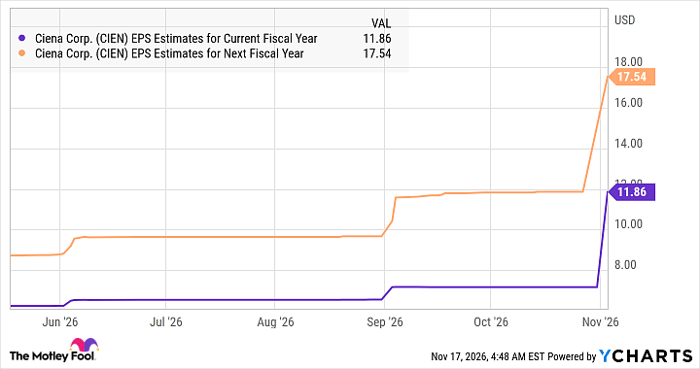
CIEN EPS Estimates for Current Fiscal Year data by YCharts
Assuming Ciena trades at 30 times earnings at the end of fiscal 2028, its stock price could reach $526 in two years (based on the $17.54 EPS estimate). That implies a 104% jump, which is why investors should consider buying this AI stock following its recent slide, before it makes a parabolic move after it releases results next month.
Should you buy stock in Ciena right now?
Before you buy stock in Ciena, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Ciena wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $327,620!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $959,410!*
Now, it’s worth noting Stock Advisor’s total average return is 802% — a market-crushing outperformance compared to 205% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 18, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Broadcom, Ciena, Goldman Sachs Group, and Micron Technology. The Motley Fool has a disclosure policy.
Recommended Articles


