




Nvidia Stock Might Have a Bigger Problem Than Replacing Jensen Huang. What Happens If It Loses 15% of Its Revenue?
Key Points
Analyst Dan Ives estimates that scrutiny of Nvidia's China-linked sales could put 10% to 15% of revenue "up in the air."
That could mean $11 billion to $16 billion a quarter, based on Nvidia's own forecast for this period.
Even if earnings fell by the same 15%, the stock would trade at only about 12 times one analyst's 2028 estimate.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
The recent headlines about Nvidia (NASDAQ:NVDA) have largely focused on who will replace Jensen Huang, who resigned as CEO last week, and for good reason. But Wall Street is also starting to worry about something that could matter more to the stock: China.
Shares fell about 2% to roughly $160 on Monday morning, a day before Nvidia reports quarterly results. The stock has cratered 33% since early October. As investors gear up for the release, here's what the China-centric fears could mean for the tech giant.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
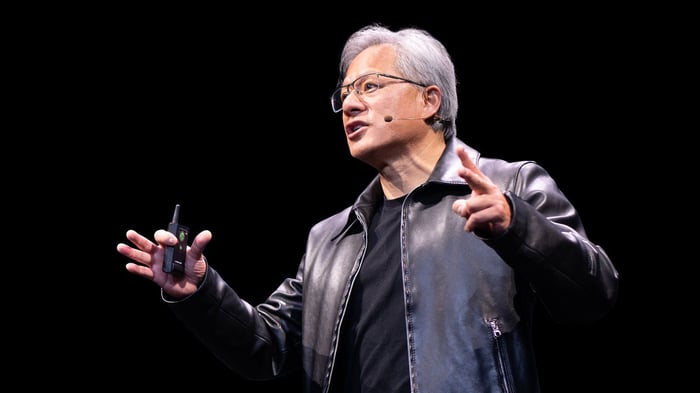
Jensen Huang. Image source: Nvidia.
Where the 15% comes from
In a note published Sunday, analyst Dan Ives said scrutiny of Nvidia's China business and "possible loopholes in the region" could put about 10% to 15% of revenue "up in the air." He named Singapore as one of the loopholes.
That's different from losing direct sales to China. Nvidia already expects to sell no data center chips there this quarter, and its forecast reflects that. The new worry is sales to customers in other countries, like Singapore, whose chips may have ended up in China anyway. If regulators clamp down on those buyers, Nvidia could lose revenue it currently counts as coming from outside China.
Washington, meanwhile, is pushing hard. Treasury Secretary Scott Bessent has called on Nvidia to explain whether its most advanced chips reached China, and Huang has agreed to closed-door testimony before Congress.
UBS is already adjusting its guidance. On Monday, it cut its 2028 revenue and earnings estimates for Nvidia by 10%, citing potential export restrictions and data center delays, and lowered its price target to $240 from $300. It kept its Buy rating.
Running the numbers
Nvidia guided for about $108 billion in revenue this quarter. If 10% to 15% of that disappeared, the company would lose roughly $11 billion to $16 billion a quarter, or about $43 billion to $65 billion a year at that pace.
That's a lot of money, but Nvidia would still be enormous without it. Even losing $16 billion, it would bring in about $92 billion this quarter, close to the $96.2 billion it reported in the second quarter, when revenue rose 106%.
As for the stock, Ives estimates Nvidia will earn $15.67 per share on an adjusted basis in fiscal 2028. At about $160, that's roughly 10 times earnings. If you cut his estimate by 15% to about $13.32, the stock would trade at about 12 times earnings.
Of course, that's a simplification (given that lost revenue doesn't translate perfectly into lost profit), but it shows how much bad news the price already reflects. Ives points out that peers trade at about 19 times next-year earnings.
Wall Street is cutting, not quitting
UBS wasn't alone among firms that lowered their price targets but kept buy-equivalent ratings. Mizuho cut its price target to $220 from $250, saying the stock's roughly 33% drop from its October peak reflects a lost Jensen Huang premium. It called Nvidia "set up attractively with a strong roadmap." TD Cowen cut to $200 from $275. With a "still-strong demand backdrop, it's hard to see Street numbers coming down materially in the near term," the firm said, but it warned the uncertainty could leave the AI infrastructure trade "in limbo."
Ives kept his $225 target and Outperform rating.
What to watch Tuesday
The biggest risk could be what investors don't know yet. Nvidia has been hit by export policy before: Ives notes that charges tied to its H20 chip last fiscal year showed "how rapidly policy can strand inventory."
On Tuesday's call, listen for whether the $108 billion forecast held, how much revenue management ties to Singapore and other parts of Asia (if mentioned), and whether next quarter's guidance sets aside more.
If the hit lands near 15%, the math suggests Nvidia still isn't expensive. For long-term investors interested in semiconductor stocks, that makes this a stock worth buying in stages, keeping some cash available in case Tuesday brings more bad news.
Missed AI’s "Act 1"? Act 2 Could Be 14x Bigger
Most investors think they missed the AI boat because they didn't buy Nvidia in 2005.
But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout, a massive technology build-out that Google’s CEO says could be more profound than fire or electricity.
While everyone watches the chip designers, one "backbone" company provides the critical technology that Nvidia and AMD literally cannot function without. We’ve detailed this under-the-radar player in our new AI Playbook.
Continue »
Jonathan Ponciano has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


