




1 Red Flag That AMD Investors Should Be Aware Of Now
Key Points
The chipmaker is still growing at a slower rate than Nvidia.
But its stock has a lot of 2027's growth priced into it already.
- 10 stocks we like better than Advanced Micro Devices ›
Adanced Micro Devices (NASDAQ: AMD) investors have enjoyed some incredible gains during 2026. Currently, AMD is the ninth-best-performing component of the S&P 500, returning about 160% so far this year. While that figure was closer to 200% before the most recent sell-off, I think this is a wake-up call for most investors.
The reality is that AMD's stock got way too ahead of itself, and its valuation far outpaces its growth expectations. That is a major red flag for investors, and there are a few items investors need to keep an eye on as to when AMD could be a good buy again (hint: It won't be for a while).
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
AMD is gaining ground, but not fast enough
The entire AMD investment thesis circles around AMD catching up to Nvidia (NASDAQ: NVDA) and taking market share. On the surface, it appears that AMD is making headway. It has huge projects like OpenAI's computing cluster, which is starting to be delivered, and is powering Meta Muse from Meta Platforms (NASDAQ: META). This has all led to stronger growth for AMD, with its data center division reporting $6.7 billion in revenue and growing by 107%. Overall, this helped the company grow its revenue 50% year over year to $11.5 billion in Q2.
Those are strong results that should be celebrated, but the problem is, it just isn't enough to catch Nvidia. During Q2, Nvidia's data center revenue reached $89 billion, up 117% year over year. Overall revenue rose to $96.2 billion, up 106% year over year. While AMD appears on the surface to be doing better, the reality is that Nvidia's lead is widening.
What makes matters worse is that Nvidia's Q2 results don't include any revenue from its upcoming generation of Vera Rubin architecture chips. This new generation promises major improvements, and they also cost more than previous generations. This will further exaggerate Nvidia's lead over AMD and eliminate the thesis that AMD is catching up.
But don't tell AMD's stock that, because according to it, AMD has won the AI arms race.
AMD's stock has uncoupled from its business
Over the long term, stocks and business growth are highly correlated. Over the short term, any number of factors can influence a stock's price. This is why long-term investing is easier for individual investors, as we can afford to wait for the business results to influence the stock price as long as we've found a company with a great long-term growth thesis.
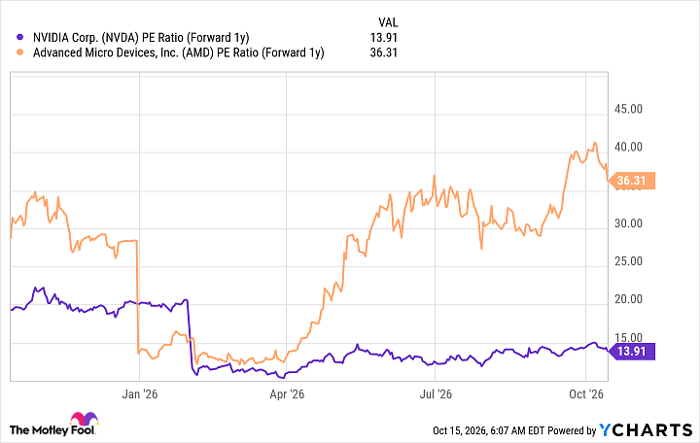
AMD clearly has a great growth rate and a strong growth thesis over the long term; the problem is that the stock has gotten so far ahead of itself that all future returns have been priced in. For both AMD and Nvidia, I'd say a fair forward price-to-earnings ratio to pay is around 30 times forward earnings. If we stretch this projection and look at next year's forward earnings, AMD still isn't even close, while Nvidia is far below this threshold.
NVDA PE Ratio (Forward 1y) data by YCharts
So, even after 2027's growth is accounted for in the stock prices, AMD is still above the valuation threshold. I'd be comfortable paying for the stock. Meanwhile, Nvidia is about half the price. Remember, Nvidia is actually growing faster and is much larger than AMD, so this major uncoupling of valuations doesn't make a lot of sense.
I think this reveals an obvious statement: AMD has gotten overvalued after its incredible run in 2026. I think the smart move is to take gains in AMD stock, then invest them in Nvidia, as it's a far cheaper stock and, frankly, doing better as a business.
Should you buy stock in Advanced Micro Devices right now?
Before you buy stock in Advanced Micro Devices, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Advanced Micro Devices wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $380,363!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,315,732!*
Now, it’s worth noting Stock Advisor’s total average return is 919% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 17, 2026.
Keithen Drury has positions in Meta Platforms and Nvidia. The Motley Fool has positions in and recommends Advanced Micro Devices, Meta Platforms, and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


