


Applied Materials vs. Taiwan Semiconductor Manufacturing: Which Tech Stock Is a Better Buy for 2027?
Key Points
Applied Materials maintains a dominant position in materials engineering for the next generation of logic and memory chips.
Taiwan Semiconductor Manufacturing serves as the world's primary foundry for advanced semiconductors with high net margins.
Which semiconductor stock deserves a spot in your portfolio?
- 10 stocks we like better than Applied Materials ›
Investors are eyeing the semiconductor boom as artificial intelligence demands faster, more efficient hardware. Choosing between Applied Materials (NASDAQ:AMAT) and Taiwan Semiconductor Manufacturing (NYSE:TSM) requires weighing equipment leadership against foundry dominance.
Applied Materials provides the specialized equipment and software needed to fabricate advanced semiconductors and displays. Taiwan Semiconductor Manufacturing operates as a pure-play foundry, manufacturing chips for nearly every major tech giant globally. While both sit at the heart of the tech supply chain, they offer different entry points into the silicon market.
The case for Applied Materials
Applied Materials sells the systems, services, and software that enable global manufacturers to build advanced chips and displays. Its materials engineering solutions are essential for creating the complex structures found in modern semiconductors used in everything from smartphones to data centers. Two major customers account for roughly 19% and 15% of its net revenue, respectively, and such customer concentration adds a layer of risk to the business.
In the 12 months ended Oct. 25, 2026, revenue reached nearly $34.4 billion, reflecting growth of approximately 21.4% over the previous period. The company generated net income of about $10.1 billion during this time frame. This growth highlights the rising demand for sophisticated production tools as global chipmakers race to increase their manufacturing capacity and transition to smaller, more powerful transistor designs.
As of Applied Materials' October 2026 balance sheet, the debt-to-equity ratio, which compares total debt to shareholders' equity, is approximately 0.3. The current ratio, which measures a company's ability to cover short-term debts with short-term assets, sits at close to 2.3. In the fiscal year ended Oct. 25, 2026, free cash flow was roughly $6.2 billion, providing the company with significant capital to reinvest in research and development.
The case for Taiwan Semiconductor Manufacturing
Taiwan Semiconductor Manufacturing operates as the world's largest dedicated semiconductor foundry, meaning it manufactures chips for other companies rather than designing its own. It serves hundreds of clients worldwide from its facilities in Taiwan, the United States, Japan, and Europe. This dominant position makes it a critical partner for businesses throughout the semiconductor stocks landscape as they transition to advanced nodes.
In the 12 months ended Sept. 30, 2026, revenue reached approximately $150.4 billion, which resulted in net income of close to $76.9 billion. The company saw significant revenue growth of about 36.1%, reflecting its ability to capture a massive share of the high-end chip market. This expansion was largely driven by the surging need for high-performance computing and artificial intelligence accelerators.
As of Taiwan Semi's December 2025 balance sheet, the current ratio is nearly 2.5, suggesting the company maintains ample liquidity for its complex global operations. Its debt-to-equity ratio is roughly 0.2, indicating that total liabilities are low compared to shareholder equity. In the fiscal year ended Dec. 31, 2025, free cash flow was approximately $30.2 billion, calculated as cash from operations minus capital expenditures.
Risk profile comparison
Applied Materials faces challenges from the cyclical nature of the equipment market and volatile global demand. The company is particularly exposed to complex geopolitical trade policies and U.S. export controls on shipments to China. These regulatory hurdles led to a $252 million settlement with the U.S. Department of Commerce in February 2026, illustrating the potential for legal and financial penalties.
Taiwan Semiconductor Manufacturing operates in a highly capital-intensive industry where it must spend billions annually to maintain its technological lead. While it dominates the foundry market, it faces competition from rivals such as Intel (NASDAQ:INTC) and Samsung (OTC:SSNLF), which are investing heavily in their own fabrication capabilities. Geopolitical tensions surrounding Taiwan also remain a persistent concern for investors evaluating the long-term stability of the supply chain.
Valuation comparison
Applied Materials has a lower forward P/E based on earnings estimates and a lower P/S ratio, which uses sales over the past 12 months.
| Metric | Applied Materials | Taiwan Semiconductor Manufacturing |
|---|---|---|
| Forward P/E | 20.2 | 24.4 |
| P/S ratio | 8.8 | 14.0 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
Which stock would I buy for 2027?
Both Taiwan Semiconductor Manufacturing and Applied Materials reported respectable revenue growth over the past 12 months or so. However, it's worth pointing out that Taiwan Semi has a consistently higher gross profit margin:
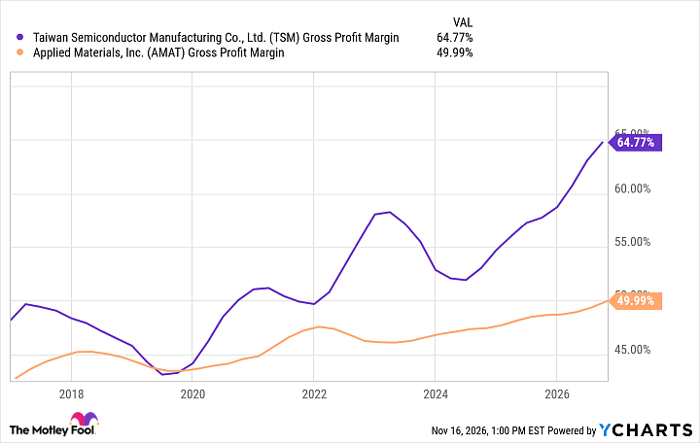
TSM Gross Profit Margin data by YCharts
Now, let's check out their historical performance:
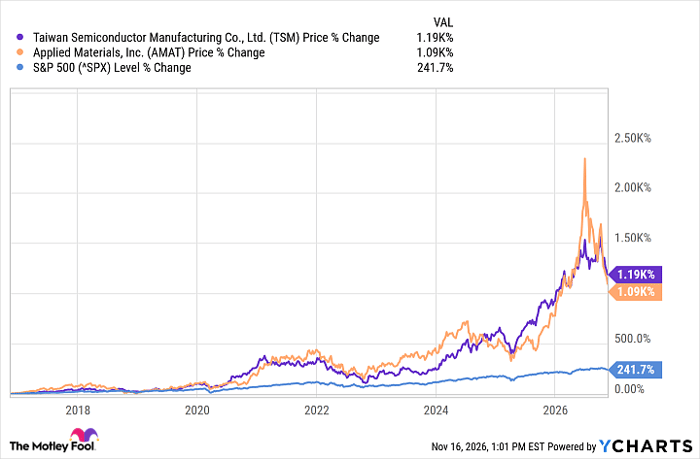
TSM data by YCharts
Taiwan Semi has bested Applied Materials' stock over the past decade, but not by much. Shares of both companies have left the S&P 500 (SNPINDEX:^GSPC) in the dust. Of course, past performance is no indication of future results.
I've owned shares of Taiwan Semi since 2022, and it's been a solid performer in my portfolio. I don't intend to sell anytime soon. However, just because Taiwan Semi was a good investment in 2022 doesn't mean it's a good investment now. With a market cap of $1.75 trillion, it's reasonable to question how much more the company can grow, especially as the law of large numbers begins to take hold.
As a result, I think Applied Materials looks like a more attractive buy for 2027 and beyond.
Should you buy stock in Applied Materials right now?
Before you buy stock in Applied Materials, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Applied Materials wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $327,620!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $959,410!*
Now, it’s worth noting Stock Advisor’s total average return is 802% — a market-crushing outperformance compared to 205% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 17, 2026.
Erin Kennedy has positions in Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Applied Materials, Intel, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


