


Canadian Dollar edges lower on Wednesday as risk appetite stumbles
- Canadian Dollar is broadly softer as CAD loses defensive posture.
- Canada brings only low-tier data until Friday’s Retail Sales.
- US Home Sales disappoint, Fitch warns of sticky inflation.
The Canadian Dollar (CAD) slipped on Wednesday as broader market sentiment weakened. This dragged the CAD lower and sent bids into the US Dollar (USD). The Canadian Dollar fell to its lowest price against the Greenback in a week, setting up the USD for its third consecutive gain against the CAD.
Canada delivers strictly mid-tier data for the remainder of the trading week, and CAD investors will have to wait until Friday for March’s Canadian Retail Sales. US data will be the key for the rest of the week.
Daily digest market movers: Canadian Dollar eases back, Greenback finds room up top
- The Federal Reserve’s (Fed) latest Meeting Minutes will be released on Wednesday, and investors will be scrambling for signs of a dovish tilt to the Federal Open Market Committee’s (FOMC) internal dialogue concerning interest rates.
- US Existing Home Sales fell for a second straight month to 4.14 million, missing the forecast 4.21 million and declining from the previous 4.22 million (revised up slightly from 4.19 million).
- Fitch Ratings warned on Wednesday that services inflation across the globe is likely to remain sticky. The ratings agency cautioned that stubborn prices will likely slow the pace of rate cuts.
- US Purchasing Managers Index (PMI) data is due on Thursday, investors are hoping for a flat print.
- Canadian Retail Sales, US Durable Goods Orders to wrap up the trading week on Friday.
Canadian Dollar PRICE Today
The table below shows the percentage change of Canadian Dollar (CAD) against listed major currencies today. Canadian Dollar was the strongest against the Australian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.11% | -0.27% | 0.22% | 0.05% | 0.39% | -0.31% | 0.33% | |
| EUR | -0.11% | -0.37% | 0.08% | -0.03% | 0.28% | -0.41% | 0.19% | |
| GBP | 0.27% | 0.37% | 0.48% | 0.29% | 0.66% | -0.04% | 0.58% | |
| JPY | -0.22% | -0.08% | -0.48% | -0.18% | 0.16% | -0.51% | 0.09% | |
| CAD | -0.05% | 0.03% | -0.29% | 0.18% | 0.34% | -0.31% | 0.25% | |
| AUD | -0.39% | -0.28% | -0.66% | -0.16% | -0.34% | -0.67% | -0.06% | |
| NZD | 0.31% | 0.41% | 0.04% | 0.51% | 0.31% | 0.67% | 0.59% | |
| CHF | -0.33% | -0.19% | -0.58% | -0.09% | -0.25% | 0.06% | -0.59% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Canadian Dollar from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent CAD (base)/USD (quote).
Technical analysis: Canadian Dollar sheds another fifth of a percent against Greenback
The Canadian Dollar (CAD) was broadly lower on Wednesday, falling four-tenths of one percent against both the New Zealand Dollar (NZD) and the Pound Sterling (GBP). However, the CAD was up one-quarter of one percent against the Australian Dollar (AUD) as the Aussie fell to the bottom of the board in the midweek market session.
USD/CAD is on pace for a third straight daily gain as the pair firms up on a technical recovery from the 50-day Exponential Moving Average (EMA) at 1.3637. The 1.3640 level remains a key technical barrier, and buyers will be looking to launch another leg higher if bids fall back to the middle zone.
Daily candles continue to hold on the north side of the 200-day EMA at 1.2550, keeping the Greenback’s bullish stance against the Canadian Dollar.
USD/CAD hourly chart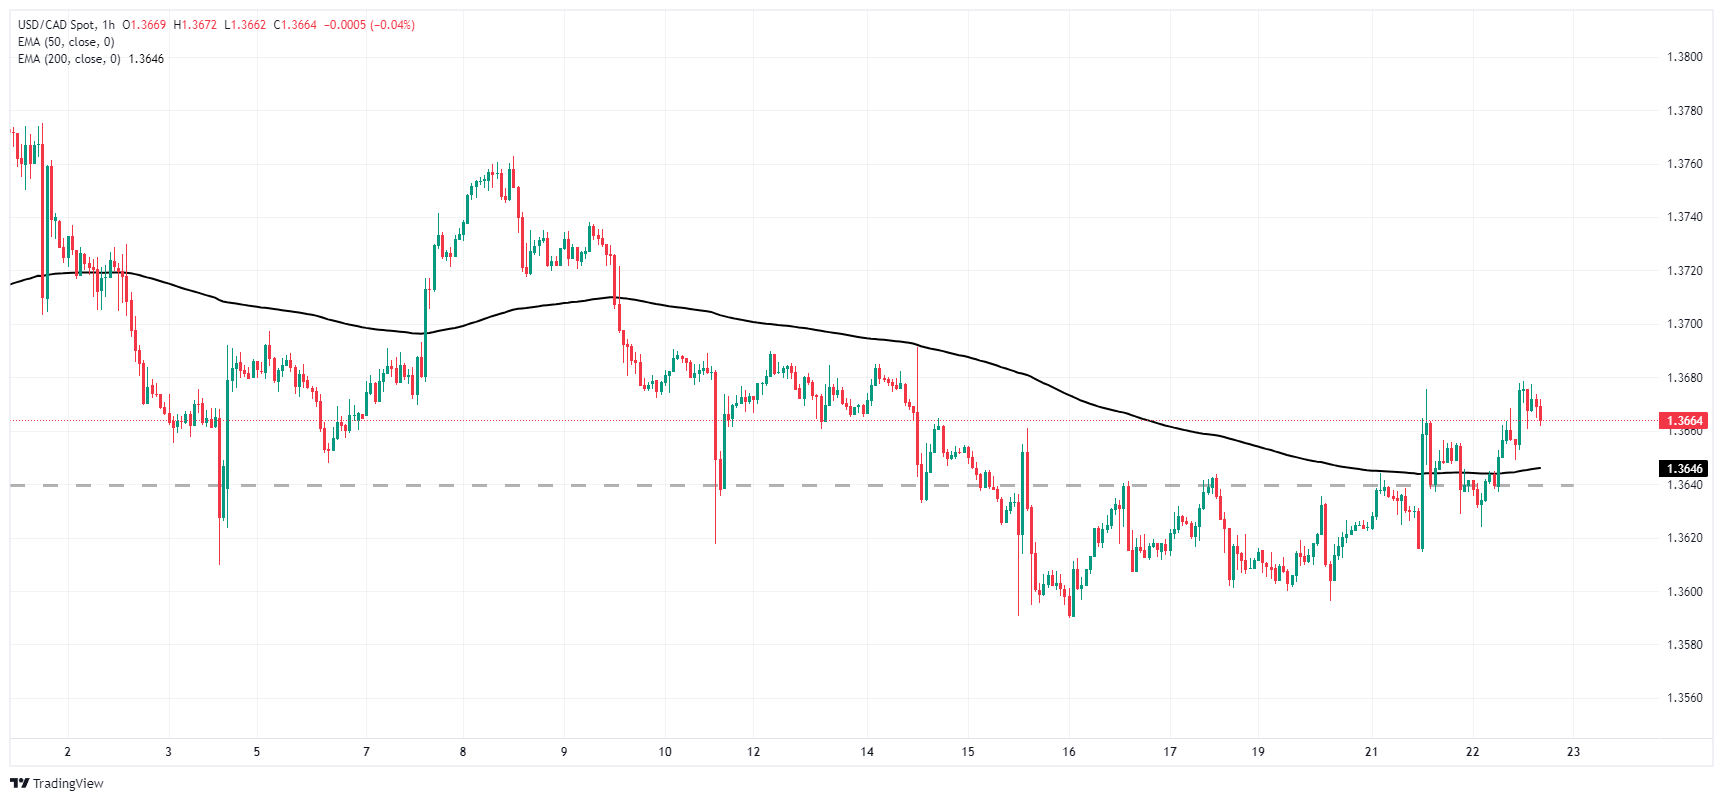
USD/CAD daily chart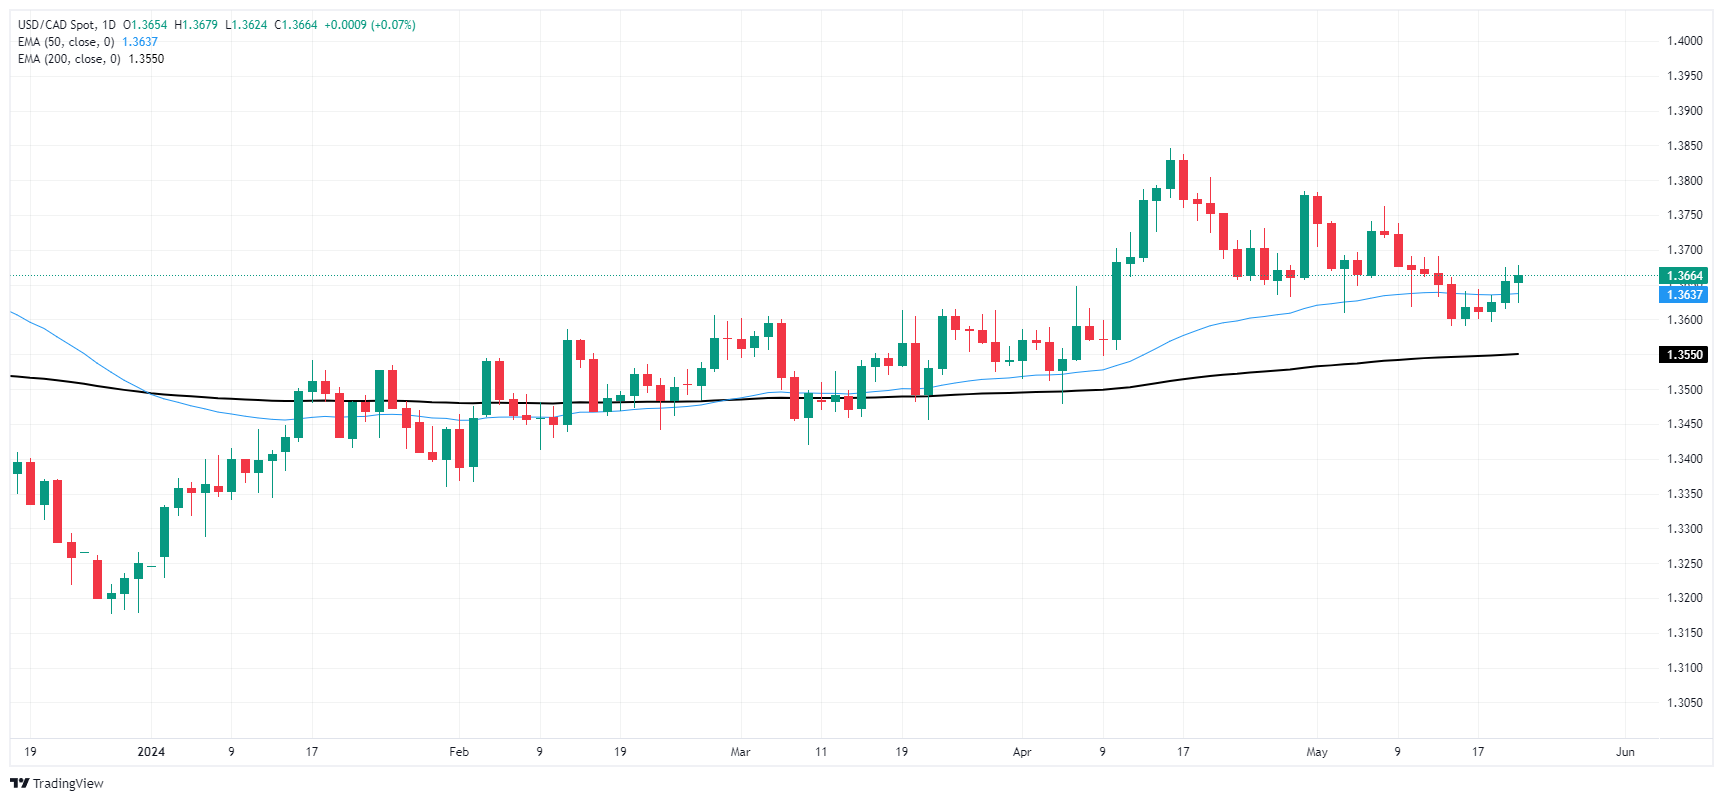
Canadian Dollar FAQs
The key factors driving the Canadian Dollar (CAD) are the level of interest rates set by the Bank of Canada (BoC), the price of Oil, Canada’s largest export, the health of its economy, inflation and the Trade Balance, which is the difference between the value of Canada’s exports versus its imports. Other factors include market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – with risk-on being CAD-positive. As its largest trading partner, the health of the US economy is also a key factor influencing the Canadian Dollar.
The Bank of Canada (BoC) has a significant influence on the Canadian Dollar by setting the level of interest rates that banks can lend to one another. This influences the level of interest rates for everyone. The main goal of the BoC is to maintain inflation at 1-3% by adjusting interest rates up or down. Relatively higher interest rates tend to be positive for the CAD. The Bank of Canada can also use quantitative easing and tightening to influence credit conditions, with the former CAD-negative and the latter CAD-positive.
The price of Oil is a key factor impacting the value of the Canadian Dollar. Petroleum is Canada’s biggest export, so Oil price tends to have an immediate impact on the CAD value. Generally, if Oil price rises CAD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Oil falls. Higher Oil prices also tend to result in a greater likelihood of a positive Trade Balance, which is also supportive of the CAD.
While inflation had always traditionally been thought of as a negative factor for a currency since it lowers the value of money, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Higher inflation tends to lead central banks to put up interest rates which attracts more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in Canada’s case is the Canadian Dollar.
Macroeconomic data releases gauge the health of the economy and can have an impact on the Canadian Dollar. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the CAD. A strong economy is good for the Canadian Dollar. Not only does it attract more foreign investment but it may encourage the Bank of Canada to put up interest rates, leading to a stronger currency. If economic data is weak, however, the CAD is likely to fall.
Recommended Articles


