


Australian Dollar depreciates as riskier assets fall on escalated tensions in Middle East
- The Australian Dollar loses ground on heightened risk aversion as Israeli missiles struck a site in Iran.
- Australia’s equity market falls to a two-month low of 7,489 on Friday.
- The US Dollar gains ground after hawkish remarks from Fed officials made on Thursday.
The Australian Dollar (AUD) extends losses for the second consecutive day on Friday, as riskier assets face pressure due to heightened risk aversion across financial markets. This sentiment intensified following confirmation from ABC News that Israeli missiles had struck a site in Iran, exacerbating tensions in the Middle East.
The Australian Dollar (AUD) faces challenges alongside a decline in the ASX 200 Index on Friday, nearing its two-month low of 7,489. This trend was influenced by weak cues from Wall Street overnight. Additionally, Australia’s 10-year government bond yield fell below 4.3%, retracting from over four-month highs, as investors anticipated a dovish outlook from the Reserve Bank of Australia (RBA) regarding monetary policy.
The US Dollar Index (DXY), which measures the US Dollar (USD) against six major currencies, advances amid heightened concerns over the potential escalation of the Israel-Gaza conflict in the Middle East. This has attracted investors seeking safe-haven assets. Furthermore, hawkish remarks from Federal Reserve (Fed) officials on Thursday triggered a surge in US Treasury yields and the US Dollar, subsequently exerting downward pressure on the AUD/USD pair.
Traders are expected to closely monitor upcoming speeches from Federal Reserve officials. Atlanta Fed President Raphael Bostic is set to partake in a moderated discussion regarding the US economic outlook at the University of Miami, Florida. Additionally, Chicago Fed President Austan Goolsbee is anticipated to participate in a moderated Q&A session at the Association for Business Journalists 2024 SABEW Annual Conference in Chicago.
Daily Digest Market Movers: Australian Dollar depreciates on risk aversion, dovish RBA’s outlook
- According to Reuters, citing Iran’s Fars News Agency, locals reported hearing explosions at the central Isfahan airport. However, the cause of these explosions remains unknown. Investigations are underway to ascertain the precise details of the incident.
- Atlanta Fed President Raphael Bostic highlighted that US inflation is excessively high and emphasized that the Fed still needs to make progress on addressing inflation. Meanwhile, New York Fed President John Williams stressed the Fed's commitment to being data-dependent and expressed that he does not currently perceive an immediate need to lower interest rates.
- US Initial Jobless Claims reported a figure of 212,000 for the week ending on April 12, compared to the expected 215,000.
- US Philadelphia Fed Manufacturing Survey showed an improvement in the manufacturing sector trends with a higher reading of 15.5 for April, exceeding the expected 1.5 and 3.2 prior.
- US Existing Home Sales Change (MoM) reduced by 4.3% in March, swinging from the previous increase of 9.5%.
- Australia’s Employment Change posted a reading of -6.6K for March, against the expected 7.2K and 117.6K prior. Unemployment Rate rose to 3.8% in March, lower than the expected 3.9% but higher than the previous reading of 3.7%.
Technical Analysis: Australian Dollar falls below the psychological level of 0.6400
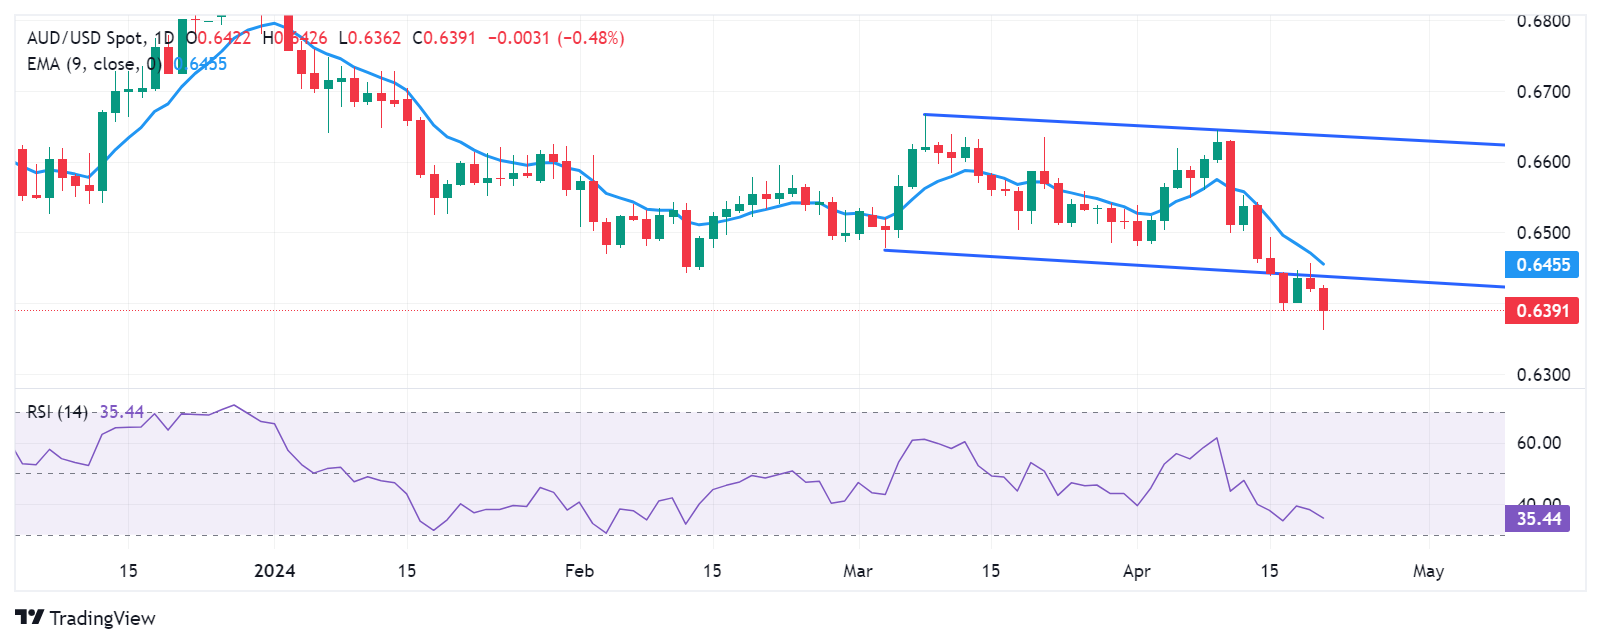
The Australian Dollar trades around 0.6390 on Friday. The latest break below the descending channel on the daily chart denotes a strengthening of the bearish bias. Additionally, the 14-day Relative Strength Index (RSI) suggests a bearish sentiment for the AUD/USD pair as it remains below the 50 level. Notable support is identified at the major level of 0.6350, following the psychological level of 0.6300. On the upside, immediate resistance for the AUD/USD pair is anticipated at the psychological level of 0.6400. A breakthrough above the latte could lead the pair to explore the region around the major level of 0.6450 and the nine-day Exponential Moving Average (EMA) at 0.6455.
AUD/USD: Daily Chart
Australian Dollar price today
The table below shows the percentage change of Australian Dollar (AUD) against listed major currencies today. Australian Dollar was the weakest against the Swiss Franc.
| USD | EUR | GBP | CAD | AUD | JPY | NZD | CHF | |
| USD | 0.05% | 0.11% | 0.05% | 0.44% | -0.17% | 0.38% | -0.52% | |
| EUR | -0.05% | 0.08% | 0.00% | 0.40% | -0.19% | 0.30% | -0.54% | |
| GBP | -0.11% | -0.06% | -0.06% | 0.33% | -0.28% | 0.23% | -0.63% | |
| CAD | -0.03% | 0.02% | 0.08% | 0.41% | -0.19% | 0.35% | -0.55% | |
| AUD | -0.49% | -0.45% | -0.38% | -0.45% | -0.66% | -0.11% | -1.01% | |
| JPY | 0.15% | 0.23% | 0.29% | 0.20% | 0.61% | 0.53% | -0.35% | |
| NZD | -0.38% | -0.31% | -0.23% | -0.31% | 0.10% | -0.50% | -0.85% | |
| CHF | 0.51% | 0.57% | 0.62% | 0.56% | 0.95% | 0.34% | 0.85% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Euro from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent EUR (base)/JPY (quote).
Australian Dollar FAQs
One of the most significant factors for the Australian Dollar (AUD) is the level of interest rates set by the Reserve Bank of Australia (RBA). Because Australia is a resource-rich country another key driver is the price of its biggest export, Iron Ore. The health of the Chinese economy, its largest trading partner, is a factor, as well as inflation in Australia, its growth rate and Trade Balance. Market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – is also a factor, with risk-on positive for AUD.
The Reserve Bank of Australia (RBA) influences the Australian Dollar (AUD) by setting the level of interest rates that Australian banks can lend to each other. This influences the level of interest rates in the economy as a whole. The main goal of the RBA is to maintain a stable inflation rate of 2-3% by adjusting interest rates up or down. Relatively high interest rates compared to other major central banks support the AUD, and the opposite for relatively low. The RBA can also use quantitative easing and tightening to influence credit conditions, with the former AUD-negative and the latter AUD-positive.
China is Australia’s largest trading partner so the health of the Chinese economy is a major influence on the value of the Australian Dollar (AUD). When the Chinese economy is doing well it purchases more raw materials, goods and services from Australia, lifting demand for the AUD, and pushing up its value. The opposite is the case when the Chinese economy is not growing as fast as expected. Positive or negative surprises in Chinese growth data, therefore, often have a direct impact on the Australian Dollar and its pairs.
Iron Ore is Australia’s largest export, accounting for $118 billion a year according to data from 2021, with China as its primary destination. The price of Iron Ore, therefore, can be a driver of the Australian Dollar. Generally, if the price of Iron Ore rises, AUD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Iron Ore falls. Higher Iron Ore prices also tend to result in a greater likelihood of a positive Trade Balance for Australia, which is also positive of the AUD.
The Trade Balance, which is the difference between what a country earns from its exports versus what it pays for its imports, is another factor that can influence the value of the Australian Dollar. If Australia produces highly sought after exports, then its currency will gain in value purely from the surplus demand created from foreign buyers seeking to purchase its exports versus what it spends to purchase imports. Therefore, a positive net Trade Balance strengthens the AUD, with the opposite effect if the Trade Balance is negative.
Recommended Articles


