




Not Nvidia. Not Broadcom. This Artificial Intelligence (AI) Chip Stock Could Be the Biggest Winner of 2027
Key Points
Cerebras Systems' revenue will multiply impressively next year, driven by a significant improvement in manufacturing capacity.
Major hyperscalers and AI companies are using Cerebras' chips, and the company's clientele continues to improve at a nice clip.
Wall Street expects Cerebras stock to outperform Nvidia and Broadcom over the next 12 months.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Nvidia and Broadcom are among the leading names in the artificial intelligence (AI) semiconductor ecosystem, dominating their respective niches and clocking terrific revenue and earnings growth in recent years.
However, both stocks have had a forgettable 2026. While Nvidia stock is down 20% this year, driven by recent developments at the company, Broadcom has clocked paltry gains of just 2%. Nvidia may remain under pressure as investors and Wall Street await whether the company's incredible growth can hold up in the post-Jensen Huang era.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Broadcom, meanwhile, could have a solid 2027 due to terrific growth in the company's AI semiconductor revenue. However, I think both Nvidia and Broadcom can be upstaged by another semiconductor stock in 2027 -- Cerebras Systems (NASDAQ:CBRS). Let's see why that may be the case.

Image source: Getty Images.
Cerebras Systems' exponential growth should be a tailwind for the stock
Cerebras Systems went public in May this year. The stock spiked 68% on the first day of trading following its initial public offering (IPO). However, the stock has slid significantly since then.
The stock's slide can be attributed to its expensive valuation when it went public, as well as concerns about the sustainability of the AI infrastructure build-out. However, Cerebras' growth and outlook clearly suggest that the market is underestimating its potential.
The company released third-quarter results on Nov. 12, reporting a 70% year-over-year increase in core revenue to $231 million. The figure was well ahead of the $214.7 million consensus estimate. Its adjusted loss of $0.12 per share was also lower than the Wall Street estimate of $0.14 per share. Importantly, Cerebras expects its business to take off substantially in 2027.
The company designs and builds wafer-scale AI chips, which are dinner-plate-sized silicon wafers used as a stand-alone processor. Nvidia and Broadcom, for comparison, offer smaller chips such as graphics cards and custom processors, which need to be connected to other chips, storage, and compute memory in rack-scale systems via high-speed networking cables to run AI workloads.
Cerebras' massive chip, on the other hand, integrates all the elements into a single platform. As a result, the company claims that its wafer-scale engine is significantly faster than traditional graphics cards. For instance, the company claimed in September last year that its CS-3 wafer-scale AI supercomputer is 21 times faster than Nvidia's DGX B200 Blackwell supercomputing system. What's more, Cerebras pointed out that the CS-3 costs 33% less and has equally lower power consumption.
It is worth noting that Cerebras doesn't just sell chips. It also operates a cloud service powered by its own chips, which allows customers to train AI models and run inference applications. The good news for investors is that Cerebras' business is poised for a significant lift-off next year.
The company has contracts with major hyperscalers, such as Oracle, Microsoft, Amazon, and OpenAI, among others. Cerebras has added three new hyperscalers to its clientele in the past six months. What's more, the company has also signed on neocloud customers who will offer inference services powered by Cerebras hardware in their data centers.
Cerebras management points out that it is on track to exit 2026 with 10x the manufacturing capacity it had at the beginning of the year. The company is also going to bring 700 megawatts (MW) of data center capacity online by late 2027 to bolster its cloud business. These factors explain why Cerebras expects its revenue to grow 3x in 2027.
The company expects $950 million in revenue this year, and the forecasts for the next couple of years suggest that Cerebras' business will grow significantly.
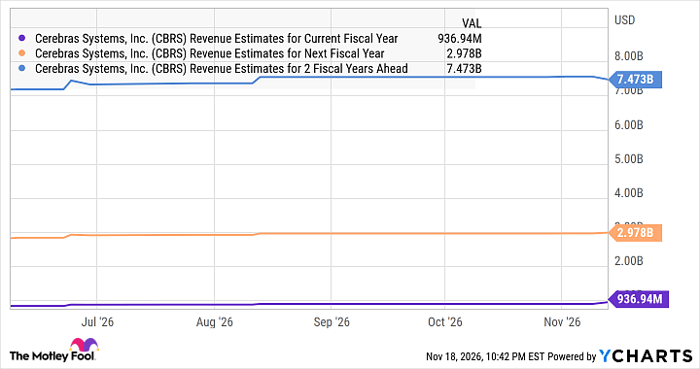
CBRS Revenue Estimates for Current Fiscal Year data by YCharts
Analysts expect a big jump in Cerebras stock, which it can indeed deliver
Cerebras has a 12-month median price target of $207, implying a 120% jump from current levels, according to CNN. What's more, 13 of the 14 analysts covering Cerebras rate it as a buy. I won't be surprised to see Cerebras achieving such solid growth.
Let's say Cerebras' revenue indeed reaches $3 billion in 2027, and it trades at 20 times sales then, lower than its current price-to-sales ratio of 23; its market cap will reach $60 billion. That's 137% higher than its current market cap. Of course, the U.S. tech sector has an average sales multiple of 6.3, and I am assuming that Cerebras will trade at a significant premium after a year. However, its stunning premium justifies the growth.
On the other hand, Nvidia and Broadcom are expected to deliver gains of 66% and 48%, respectively, based on their 12-month median price targets. So, even analysts expect Cerebras stock to outpace its well-established peers.
All this suggests that now is a good time for investors to buy Cerebras following its recent slide, as its outstanding growth prospects could help it outperform Nvidia and Broadcom over the coming year.
Should you buy stock in Cerebras Systems right now?
Before you buy stock in Cerebras Systems, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Cerebras Systems wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $322,605!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $927,581!*
Now, it’s worth noting Stock Advisor’s total average return is 790% — a market-crushing outperformance compared to 202% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 20, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Amazon, Broadcom, Microsoft, Nvidia, and Oracle. The Motley Fool has a disclosure policy.
Recommended Articles


